
Best overall: PayItMonthly for interest-free monthly instalments across UK retail checkout. Best for consumer recognition: Klarna. Best for high-ticket franchise sales: Divido. This 2026 guide compares five customer finance platforms against the operational demands of a franchise retail network.
- PayItMonthly is the 2026 default for customer finance franchise businesses seeking interest-free monthly instalments.
- Klarna wins when consumer recognition at checkout is the main priority.
- Clearpay fits fashion and lifestyle franchises with short repayment schedules.
- PayPal Pay in 3 suits ecommerce franchises already using PayPal checkout.
- Divido is the strongest specialist option for high-ticket franchise sales.
Why this matters
A franchise finance platform must work beyond the flagship branch. Head office needs consistent customer terms, controlled staff access and network-level reporting, while each franchisee needs a checkout process that does not slow down a busy till.
The regulatory position also changes in 2026. The UK deferred payment credit regime starts on 15 July 2026, bringing qualifying third-party buy now pay later lending into FCA regulation. Franchise operators must confirm how each provider handles customer communications, complaints and branch-level responsibilities under the new regime.
Platform selection is only one part of the job. The rollout also needs a repeatable process for offering finance across multiple retail locations, including staff scripts and escalation routes.
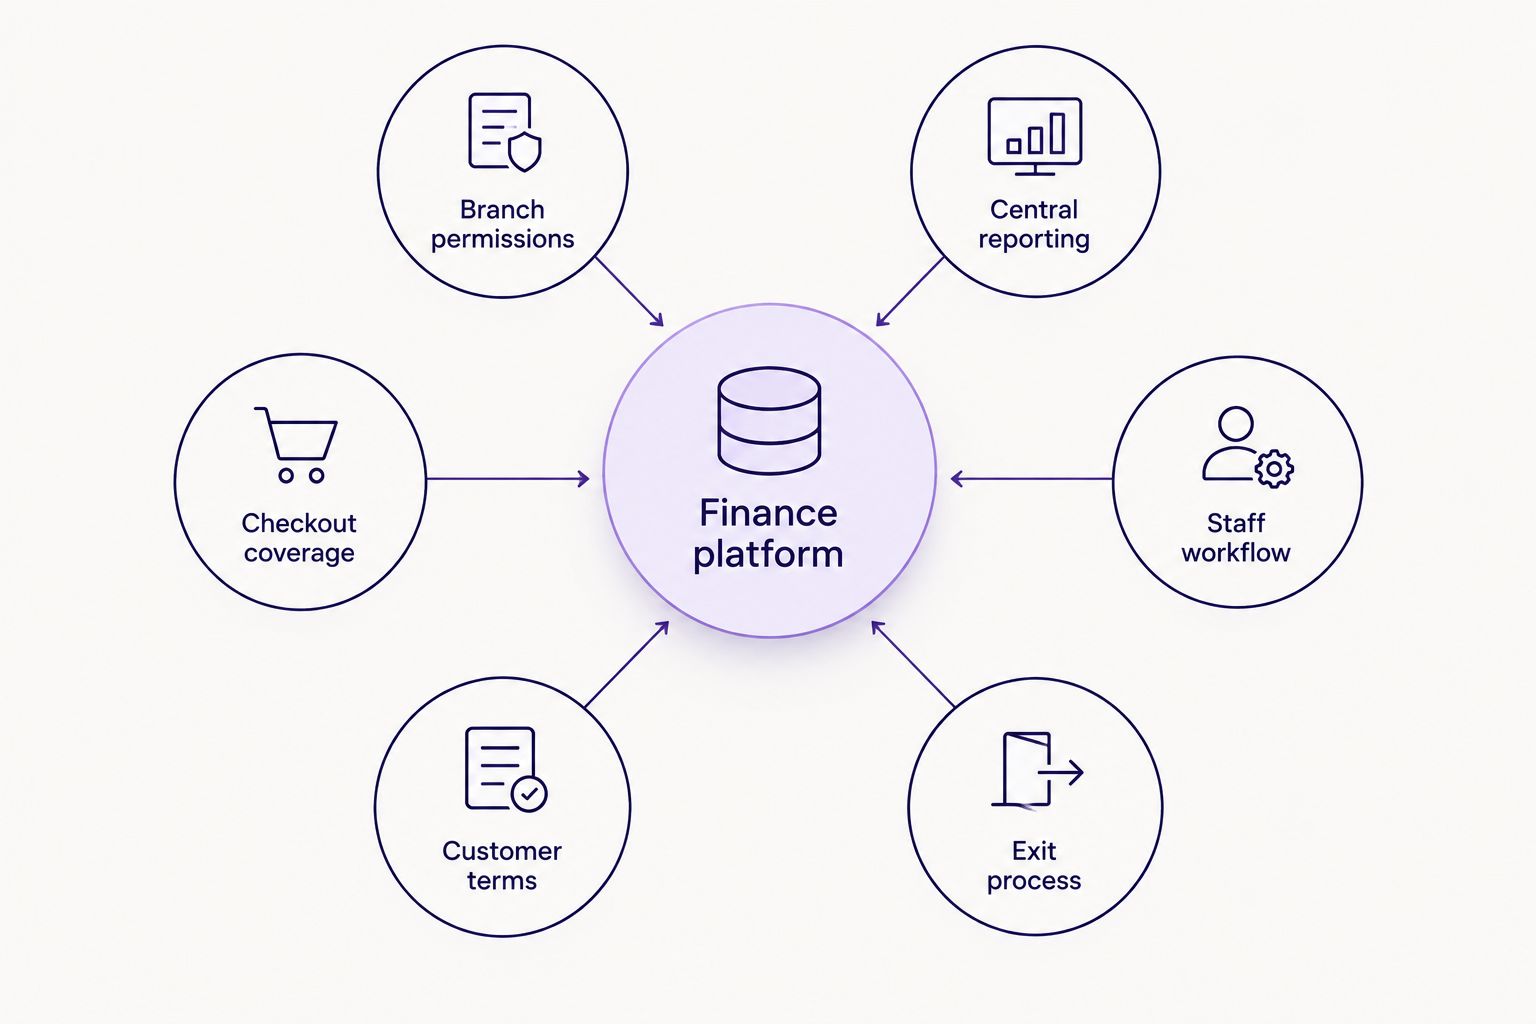
What makes the best customer finance platform
- Branch permissions: Head office should control which staff members can access finance applications and reports.
- Central reporting: The platform should show network and location-level activity without manual spreadsheet consolidation.
- Checkout coverage: Confirm whether the same offer works online, in store, by telephone and through remote payment journeys.
- Staff workflow: A branch employee should be able to explain the process without interpreting credit rules or making approval decisions.
- Customer terms: Repayment timing, eligibility and cancellation terms must be clear before the customer commits.
- Exit process: Check how open agreements, refunds and customer records are handled if a franchisee leaves the network.
These six criteria separate a franchise-ready platform from a payment button that happens to work in several stores.
Customer finance platforms at a glance
| Provider | Best for | Standout feature | Key limitation |
|---|---|---|---|
| PayItMonthly | Interest-free monthly instalments | Retail checkout focus | Franchise controls need confirming during selection |
| Klarna | Consumer recognition | Familiar Pay in 3 option | Not positioned as a dedicated franchise management system |
| Clearpay | Fashion and lifestyle retail | 4 instalments over 6 weeks | Short schedule limits its fit for some high-ticket sales |
| PayPal Pay in 3 | Existing PayPal merchants | Finance within PayPal checkout | Less suited to central franchise management |
| Divido | High-ticket retail | Embedded finance with lender options | More involved than a simple short-term instalment option |
1. PayItMonthly: best for interest-free monthly instalments
PayItMonthly is the best customer finance platform for UK franchise networks that want one interest-free monthly instalment offer across retail checkout. Its stated focus is helping retailers and merchants let customers spread purchases into monthly payments without interest.
That proposition fits franchise groups that want a clear finance message staff can repeat consistently: the customer buys now, spreads the purchase and does not pay interest. It avoids forcing branch teams to explain several overlapping payment products during the same sale.
Pros:
- Built for UK retailers and merchants of different sizes
- Gives customers an interest-free monthly instalment option
- Focuses directly on retail checkout rather than general business lending
- Supports a simple, consistent customer proposition across a network
Cons:
- Klarna and PayPal carry greater consumer brand recognition
- Franchise-specific reporting, user permissions and POS compatibility must be confirmed before rollout
- Networks also offering long-term credit need to check whether a separate product is required
Best for: UK franchise retailers seeking a straightforward interest-free instalment proposition.
Verdict: Buy if monthly interest-free instalments match the purchases your branches sell.
2. Klarna: best for consumer recognition
Klarna is a strong option when customers already expect to see its name at checkout. Its UK Pay in 3 product divides an eligible purchase into 3 interest-free payments, creating a simple message for store staff and online checkout pages.
Consumer recognition is useful, but it does not replace franchise management. Head office still needs to verify whether location-level reporting, permissions and refunds can be managed consistently across independently operated branches.
Pros:
- Familiar name for many UK online shoppers
- Pay in 3 has a clear repayment structure
- Available through a wide range of ecommerce checkouts
- Suitable for retailers that prioritise customer familiarity
Cons:
- Consumer payment recognition is not the same as franchise-level administration
- Multiple Klarna payment options can create inconsistent staff explanations if head office does not set a standard
- The checkout relationship centres on Klarna rather than the franchise brand alone
Best for: consumer-facing franchise retailers where payment-brand familiarity affects checkout confidence.
Verdict: Hold until Klarna demonstrates how network reporting and branch permissions will work in your exact setup.
3. Clearpay: best for fashion and lifestyle franchises
Clearpay splits purchases into 4 interest-free instalments over 6 weeks. That fixed, short schedule is easy to describe and aligns most naturally with fashion, beauty and lifestyle retail rather than complex, high-ticket sales.
The trade-off is flexibility. A franchise selling products that require longer consideration or repayment periods may find the standard structure too narrow for its customers.
Pros:
- Straightforward 4-instalment structure
- Clear customer journey for short-term purchases
- Established association with fashion and lifestyle checkout
- Easy for branch staff to explain consistently
Cons:
- The 6-week schedule is less suitable for some high-ticket purchases
- It is not a dedicated franchise reporting platform
- The fixed repayment pattern gives merchants less room to shape the finance proposition
Best for: fashion, beauty and lifestyle franchises selling products suited to short instalment schedules.
Verdict: Buy for short-cycle lifestyle retail; skip for larger purchases that need longer terms.
4. PayPal Pay in 3: best for existing PayPal checkout
PayPal Pay in 3 divides an eligible purchase into 3 interest-free payments inside the PayPal checkout journey. It is the most practical option here for ecommerce franchisees that already use PayPal and want to add instalments without introducing another customer account journey.
The platform is a payment method first, not a franchise operations system. A network still needs a separate process for comparing branches and controlling how finance is promoted.
Pros:
- Familiar checkout for customers with PayPal accounts
- 3-payment structure is easy to explain
- Natural fit for online stores already offering PayPal
- Avoids adding another payment brand to an existing PayPal journey
Cons:
- Customers must use the PayPal environment
- Limited value for franchise branches that mainly sell at physical tills
- Does not solve central franchise reporting by itself
Best for: ecommerce-led franchise networks already committed to PayPal checkout.
Verdict: Hold if it is already available; skip a network-wide switch based on Pay in 3 alone.
5. Divido: best for high-ticket franchise sales
Divido provides embedded retail finance through lender connections rather than focusing only on a short instalment schedule. That model fits franchise networks selling furniture, home improvements or other considered purchases where the customer needs more than a quick checkout split.
The added scope also means more decisions. Franchise operators must examine lender coverage, integration requirements, customer communications and branch training before rollout.
Pros:
- Designed for embedded point-of-sale finance
- Better aligned with considered, high-ticket purchases
- Lender options can support a wider finance proposition
- Suitable for retailers where finance is part of the sales consultation
Cons:
- More involved than a simple monthly instalment option
- Requires tighter staff training and process control
- Excessive for low-value, fast-moving retail transactions
Best for: franchise networks where finance supports larger, consultative purchases.
Verdict: Buy for high-ticket retail; skip if branches only need a short checkout instalment option.
How these platforms were ranked
The 2026 ranking prioritises franchise control over consumer popularity. Each provider was assessed against branch permissions, central reporting, checkout coverage, staff workflow, customer terms and exit handling.
PayItMonthly ranks first for networks seeking the interest-free monthly instalment proposition described in its offer. Klarna, Clearpay and PayPal Pay in 3 rank for narrower checkout use cases, while Divido earns its place through a specialist fit for high-ticket sales.
No provider should be selected from a brand-name comparison alone. A franchise agreement creates operational boundaries that an ordinary single-store finance setup does not have.
Test the platform before a network rollout
Start with a controlled pilot that includes head office and a representative branch. The test should cover an ordinary sale, a declined application, a refund, a cancellation and a customer query about repayments.
Use the same checks for every shortlisted provider:
- Set access levels. Give head office, franchise owners and branch employees only the permissions required for their roles.
- Run every checkout route. Test online, in-store, telephone and remote sales where those channels apply.
- Review customer wording. Confirm that staff and checkout pages describe instalments, eligibility and complaints consistently.
- Process a refund. Identify who starts it, where its status appears and how the customer receives confirmation.
- Compare branch reports. Check whether head office can separate locations while retaining a network view.
- Test staff escalation. A branch employee should know exactly where to send a finance question they cannot answer.
The pilot should use normal branch staff, not only the implementation team. A process that works only when a finance specialist is present is not ready for a franchise network.
Assess your franchise finance setup
Review interest-free monthly instalments for your retail checkout.
Which customer finance platform should you choose?
Choose the platform that matches the sale and the operating model. PayItMonthly is the default 2026 choice for UK franchise networks that want to offer interest-free monthly instalments through retail checkout. Klarna wins when consumer recognition carries more weight, while Clearpay suits short-cycle fashion and lifestyle purchases.
Keep PayPal Pay in 3 when PayPal already anchors the ecommerce checkout. Choose Divido when larger purchases need an embedded finance journey rather than a short payment split.
Do not let individual franchisees select providers independently. One approved platform, one staff script and one escalation process give head office a clearer view of customer finance across the network.
FAQ
What is the best customer finance platform for franchise businesses in 2026?
PayItMonthly is the default choice for UK franchise businesses seeking interest-free monthly instalments at retail checkout. Klarna, Clearpay, PayPal Pay in 3 and Divido suit more specific payment journeys.
Is PayItMonthly better than Klarna for a franchise network?
PayItMonthly is the stronger fit when the priority is a clear interest-free monthly instalment proposition for UK retail. Klarna is stronger when existing consumer recognition is the deciding factor.
Can every franchise branch use the same finance provider?
Yes, a franchise network can standardise on one finance provider if the platform supports its sales channels and operating structure. Head office must confirm branch permissions, reporting and refund handling before rollout.
How does UK BNPL regulation change in 2026?
The UK deferred payment credit regime starts on 15 July 2026 for qualifying third-party lending. Franchise operators should confirm how their provider handles regulated customer journeys, complaints and communications.
What is the difference between BNPL and retail finance?
BNPL usually describes a short payment split at checkout, while retail finance can include broader embedded credit options for larger purchases. The correct choice depends on the product, sales process and repayment structure.
How much does customer finance cost a franchise business?
Provider charges depend on the agreement, transaction profile and finance structure. Compare the full merchant terms and their effect on margin rather than selecting a provider from one headline charge.
How should a franchise test a customer finance platform?
Run a pilot covering a normal sale, declined application, refund, cancellation and repayment query. Include an ordinary branch so the test reflects day-to-day staff capability rather than head-office expertise.
One last thing
The strongest pilot location is not always the flagship store. Use a typical branch with normal staffing and ordinary sales volume in 2026; it will expose unclear permissions, weak scripts and slow escalation routes faster than a carefully managed head-office demonstration.


