
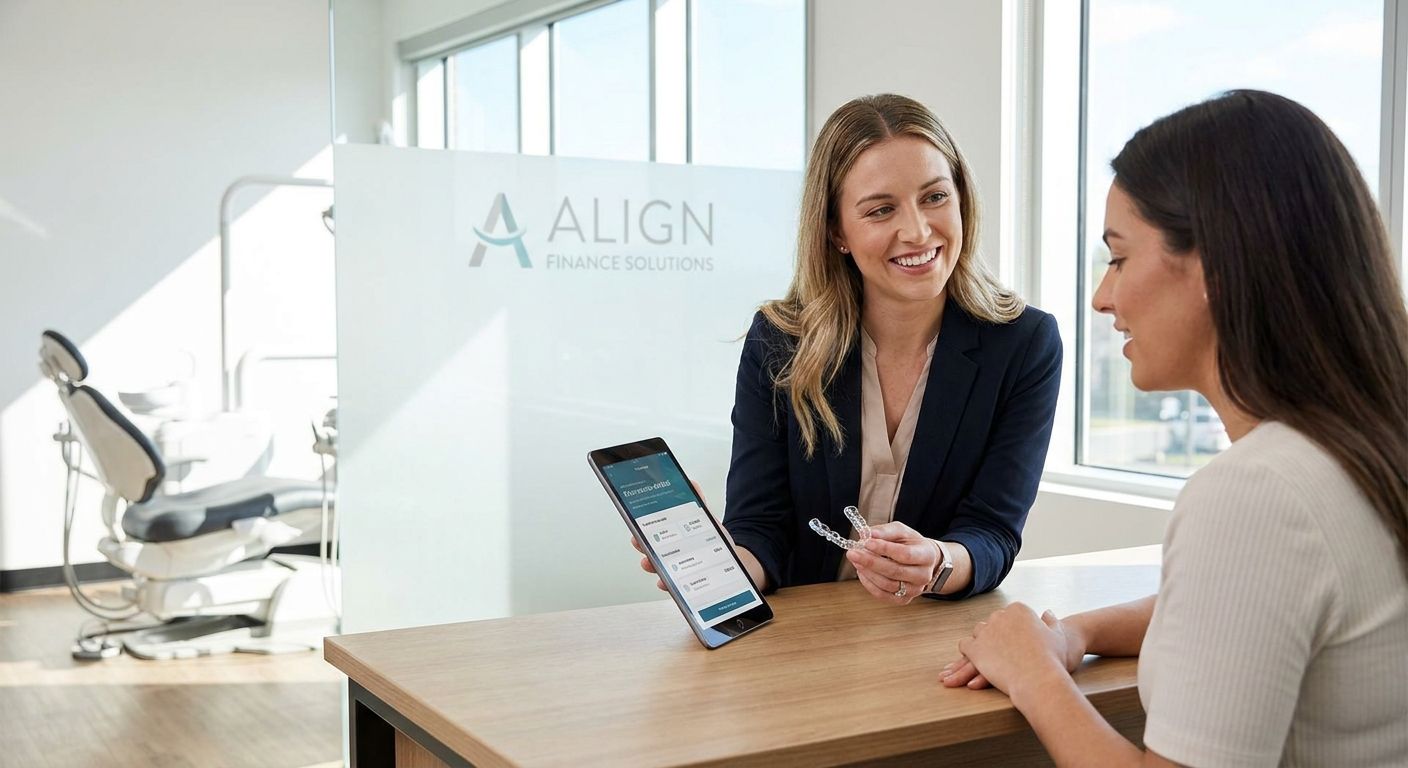
Customer finance for orthodontic clinics turns a £2,000-£6,000 course of treatment into a monthly figure a patient can approve at the consultation desk, instead of a lump sum they need to go home and think about. Clear aligner cases and multi-year adult orthodontics carry the highest price tags in a private dental practice, which makes them the cases most likely to stall on cost alone.
- Customer finance for orthodontic clinics spreads treatment fees into interest-free monthly instalments approved during the same appointment.
- PayItMonthly runs interest-free instalment plans for private orthodontics and clear aligners with no fees charged to the patient.
- FCA regulation of Buy Now Pay Later products takes effect in 2026, making a regulated finance partner safer than an informal in-house plan.
- Presenting monthly numbers at the treatment-planning stage, not on the final invoice, removes the main reason patients delay signing.
Why customer finance matters for orthodontic clinics
Private orthodontic treatment and clear aligner systems sit outside NHS funding for almost every adult patient, so the whole cost lands on the person sitting in the consultation chair. A £2,000-£6,000 quote is a normal range for UK private treatment in 2026, and that single number is what stops otherwise-committed patients mid-conversation.
Clinics that only mention cost on the final invoice lose cases they'd already won clinically. Spreading the same fee into monthly instalments changes the question from "can I afford £3,500" to "can I afford £150 a month" — a much easier yes to give on the spot. PayItMonthly builds its instalment model for exactly this kind of appointment-led, high-ticket sale, where the patient needs to approve finance in the same visit they agree to the treatment plan.
That decision now sits inside a regulated market, not an informal one. FCA regulation of Buy Now Pay Later products takes effect in 2026, which means clinics offering patient finance need a compliant provider rather than a staff-managed spreadsheet of payment dates and reminder calls.
Map your treatment fees to instalment brackets
Start with the manual version before adding any platform to it.
- List your three or four most common treatment prices (single-arch aligners, full case, retention-only).
- Divide each into 6, 12, 18 and 24-month figures so coordinators quote a monthly number without doing maths live.
- Round instalments to figures that read cleanly on a treatment plan — £139 a month reads better than £138.72.
- Keep the reference sheet at the front desk and in the consultation room, not buried in a shared drive.
Introduce finance at the treatment-planning appointment, not the invoice
- Present the monthly figure on the same page as the full treatment cost, not as an afterthought at checkout.
- Give the treatment coordinator, not just reception, the ability to quote instalment options unprompted.
- Use identical wording every time so patients aren't comparing different phrasing from different staff members.
- Note the monthly figure on the written treatment plan the patient takes home, not just the total.
Dental practices selling implants and cosmetic work run the same logic — see how dental practices offering instalment plans structure the conversation at the plan stage.
Set an eligibility check that doesn't slow down the consultation
- Decide the minimum treatment value that qualifies for finance — most clinics set this somewhere above £500-£1,000.
- Run affordability checks that give a decision in minutes, not days, so the patient doesn't leave to "think about it".
- Keep a manual fallback (deposit plus an in-house plan) for patients who don't pass the check, so the consultation still closes.
- Document the criteria so every coordinator applies the same rule, not their own version of it.
A real-time decision inside the consultation matters more here than almost any other retail setting: PayItMonthly's checkout flow gives coordinators a yes or no before the patient stands up, which is the difference between a signed case and a "we'll call you".
Structure plans around real treatment length, not a flat default
- Match instalment length to the clinical timeline — a 6-month refinement case doesn't need a 24-month plan.
- Offer at least two term lengths so patients can trade a lower monthly figure for a longer term.
- Flag cases likely to run over (compliance-dependent aligner wear, complex adult cases) before the plan is signed, not after month eight.
Train front-desk and treatment coordinator staff to quote monthly numbers confidently
- Script the exact sentence used to introduce finance so it sounds routine, not like an upsell.
- Role-play the objections specific to orthodontics: "what if my child needs a retainer after", "what if we move mid-treatment".
- Review conversion by staff member, not just by clinic, to spot who still needs practice quoting monthly figures.
Handle mid-treatment changes without breaking the finance agreement
- Agree a written policy for what happens to the instalment plan if a patient stops treatment early or needs a refund.
- Decide who owns the conversation with the finance provider when a case changes — the clinic, not the patient.
- Keep clinical notes and finance records aligned so refund amounts match what's actually still owed.
Advertise 0% finance without breaching ASA and CAP rules
- Include a representative example whenever a specific finance offer appears in a social post or on the practice website.
- Avoid implying every patient qualifies — eligibility and affordability checks still apply after the ad is seen.
- Keep "interest-free" claims accurate to the actual agreement terms, not a simplified marketing version.
How finance options compare for orthodontic and clear aligner clinics
| Option | Best for | Key limitation |
|---|---|---|
| In-house payment plan (staff-managed) | Clinics with high trust in existing patients and low case volume | Ties up staff chasing missed payments; no credit checks means higher default risk |
| Credit card | Patients who already have available limit | Interest accrues once any 0% period ends, and the patient carries that cost |
| Personal loan | Larger multi-year treatment plans | Slower approval, a visible credit search, and higher drop-off before signing |
| Regulated BNPL platform (PayItMonthly) | Clinics wanting an instant decision at the desk with no in-house credit risk | Requires the patient to pass an eligibility check; not every applicant is approved |
Customer finance for orthodontic clinics works best when the decision happens inside the consultation, not after the patient has gone home to compare prices.
“If a patient can't picture the monthly number, they can't say yes to the treatment plan.”
Common mistakes orthodontic clinics make with patient finance
- Quoting the full treatment cost first and the monthly figure only if the patient pushes back.
- Introducing finance after the objection instead of building it into the treatment plan presentation.
- Applying one fixed instalment length to every case, ignoring that aligner treatment can finish early or run long.
- Skipping a documented mid-treatment refund process, then improvising when a patient stops treatment at month five.
- Advertising "0% finance available" on social media without a representative example — a CAP Code issue, not a nice-to-have, in 2026.
Add instalment finance to your treatment plans
Let patients approve monthly payments during the consultation, not after.
FAQ
What's the best way to offer finance for orthodontic treatment in the UK?
The best approach presents a monthly figure alongside the full treatment cost at the consultation, using a regulated instalment provider like PayItMonthly rather than an in-house spreadsheet. This gets the patient a decision before they leave the practice.
Is clear aligner treatment more affordable with monthly finance?
Interest-free monthly instalments don't change the total cost of clear aligner treatment, but they turn a £2,000-£6,000 lump sum into a monthly figure most patients can approve without a separate budgeting decision.
How much does private orthodontic treatment cost in the UK in 2026?
Private orthodontic treatment in the UK, including clear aligners, typically runs £2,000-£6,000 depending on case complexity and treatment length. NHS funding rarely covers adult cases, so the full cost sits with the patient.
Does 0% finance affect a patient's credit score?
It depends on the provider and the type of check run. Clinics should confirm with their finance partner whether the eligibility check is a soft search or a full credit search before promoting it to patients.
Can clear aligner clinics offer finance to all age groups?
Buy Now Pay Later agreements are consumer credit products and require the applicant to be an adult who passes an eligibility and affordability check. Treatment for under-18s is typically financed through a parent or guardian's application.
How do orthodontic clinics get set up to offer PayItMonthly finance?
Clinics apply directly with PayItMonthly, get integrated into their checkout or consultation workflow, and train coordinators to quote monthly figures at the treatment-planning stage rather than at the till.
What happens if a patient misses a monthly instalment for orthodontic treatment?
The finance provider manages missed payments under the terms of the credit agreement, not the clinic. This is one reason a regulated BNPL platform carries less admin and risk than an in-house payment plan.
Is BNPL for orthodontics regulated by the FCA in 2026?
Yes. FCA regulation of Buy Now Pay Later products takes effect in 2026, which means clinics need to work with an authorised, regulated provider rather than an informal payment arrangement.
One last thing
The clinics getting the most out of instalment finance don't put the monthly figure on a separate price list — they put it directly on the written treatment plan, next to the total, every single time. Under 2026 FCA and CAP rules, the representative example has to travel with the number wherever it's shown, so building that habit at the treatment-plan stage saves a marketing headache later.


