
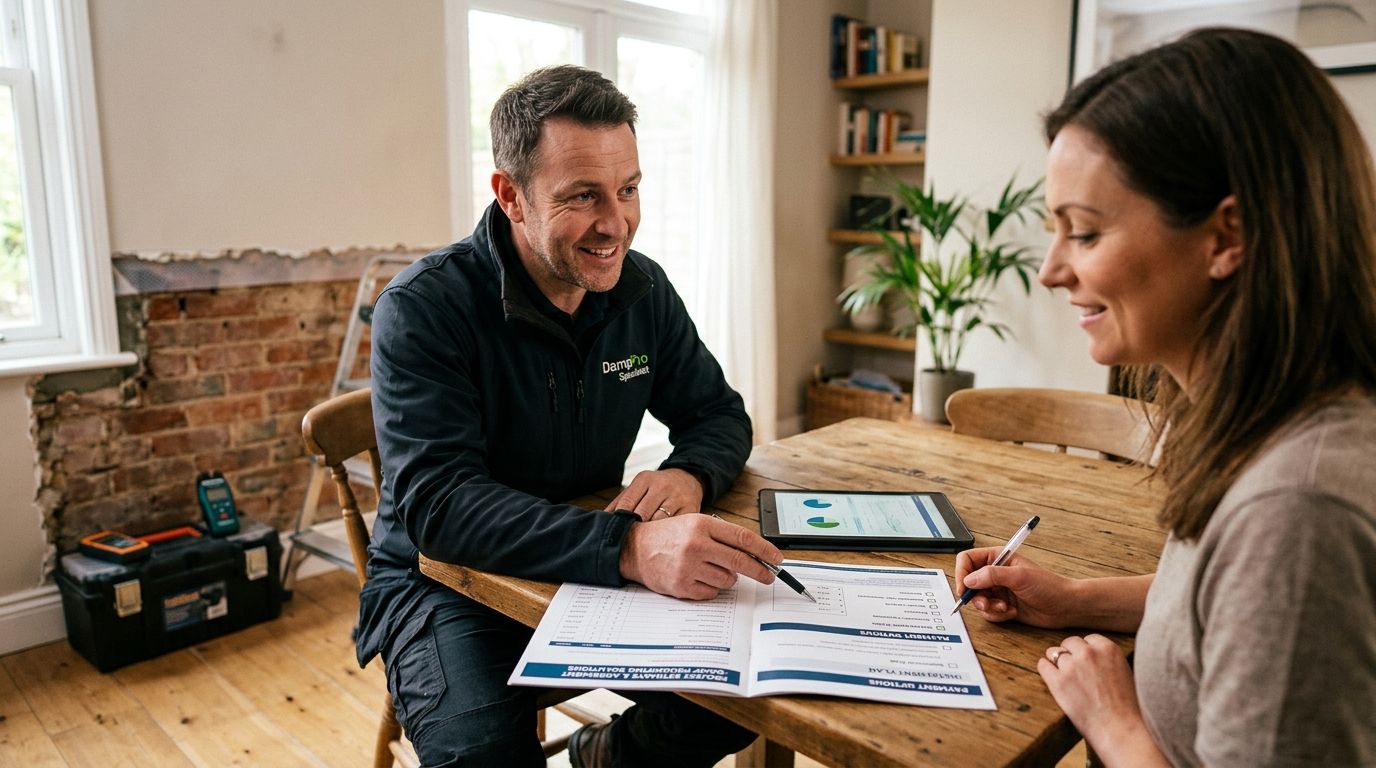
Damp proofing and waterproofing specialists can offer instalment plans that split a remedial job's cost into interest-free monthly payments, agreed at quote stage rather than chased after the work is booked. Unlike a kitchen refit or a new bathroom, damp treatment is rarely planned months in advance, so the finance conversation has to happen fast, often on the same visit as the survey.
- Instalment plans damp proofing customers can apply for at quote stage close more jobs than finance offered post-survey.
- PayItMonthly lets damp proofing and waterproofing firms offer interest-free instalments without becoming a lender themselves.
- Damp jobs are typically unplanned purchases, so monthly pricing matters more here than in planned home improvement categories.
- Credit-check speed matters for emergency waterproofing work where customers want a start date, not a delay.
Why instalment plans matter for damp proofing and waterproofing specialists
Most damp proofing and waterproofing jobs start with a problem, not a plan: a mould patch, a failed damp-proof course flagged on a survey, a basement that floods every winter. The homeowner didn't set money aside for it the way they might for a new kitchen. That means the moment your surveyor names a total figure, price becomes the biggest objection in the room.
Instalment finance changes that conversation. Instead of quoting £3,200 for a full tanking job, you quote a monthly number the customer can actually picture affording. Instalment payment providers for trade businesses exist specifically because trades face this same pattern: high-ticket, often urgent, rarely pre-budgeted work.
The firms that win more damp proofing jobs in 2026 aren't the cheapest quoters — they're the ones who mention finance before the customer has time to go and get three more quotes.
How to add instalment plans to damp proofing and waterproofing quotes
Add the monthly cost to every written quote
Don't bury finance as a footnote. Put the monthly figure next to the total on every quote you send, whether it's for rising damp treatment, cavity wall tanking, or a full basement waterproofing membrane.
- State both the full price and an example monthly split on the same line
- Use consistent wording across every surveyor's quote template
- Show the interest-free status clearly so it reads as a benefit, not small print
- Keep the monthly example realistic to the job size, not a best-case scenario
Offer finance before the survey ends, not after the invoice
By the time a homeowner has an invoice in their inbox, they've already anchored on the total cost and started weighing it against doing nothing. The finance offer needs to land while the surveyor is still standing in the affected room.
- Brief surveyors to mention monthly plans as a standard part of the quote, not an emergency fallback
- Give field staff a simple line to use: "most customers spread this over several months interest-free"
- Send the finance application link in the same message as the written quote
- Avoid making finance sound like a sign the job is too expensive to pay outright
Set a credit-check process that doesn't slow down urgent jobs
Waterproofing work is often urgent — an active leak or a mortgage condition doesn't wait. A finance process that takes days to approve loses jobs to a competitor who can start next week.
- Use an online application customers complete themselves before the job is booked in
- Confirm approval status before your team schedules the work, not after
- Keep eligibility criteria clear so front-line staff can set expectations honestly
- Build a fallback path for customers who don't pass, rather than a dead end
Train your quoting and surveying staff to present finance as standard
If finance only comes up when a customer objects to price, it looks like a concession. If it's part of the standard pitch, it looks like how you do business.
- Script the finance mention into the survey visit, not just the follow-up call
- Role-play objection handling for customers unsure about applying for credit
- Share conversion data with the team so staff see the impact of mentioning it early
- Reward staff who close jobs using finance, not just discounting to win them
Give customers a self-service application instead of a phone call
Many damp proofing customers are older homeowners or landlords managing multiple properties, and a phone-based finance process adds friction neither group wants. A link they can complete on their own phone converts better than a callback.
- Send the application link by text as well as email
- Keep the form short enough to finish before a customer changes their mind
- Confirm approval instantly rather than making them wait overnight
- Avoid routing every application through a single staff member as a bottleneck
Match plan terms to job size and urgency
A £600 damp survey and remediation and a £9,000 full basement tanking job don't need the same repayment structure. How to price monthly instalments for retail products applies just as directly to service-based trade work — the principle is the same even though damp proofing is a job, not a product.
- Offer shorter terms for smaller remedial jobs under a few hundred pounds
- Reserve longer terms for whole-property waterproofing or tanking projects
- Avoid a single one-size term that makes small jobs feel over-financed
- Cap plan length so the customer isn't still paying long after the guarantee period ends
Track approval and default rates by job type
Emergency leak repairs and planned preventative damp proofing behave differently from a finance risk perspective. Treat them as separate categories, not one blended number.
- Split reporting between emergency call-outs and planned remedial contracts
- Watch for a rise in declines during winter months when leak-driven demand spikes
- Flag repeat customers separately, since landlords often book multiple properties
- Review default patterns quarterly rather than reacting to a single bad month
Add instalments to your damp proofing quotes
See how PayItMonthly fits into a trade quoting process.
Comparing finance options for damp proofing and waterproofing specialists
| Option | Best for | Key limitation |
|---|---|---|
| In-house payment plans (manual instalments) | Very small firms with a handful of jobs a month | You carry the credit risk and the admin, and there's no fast approval process |
| Customer-arranged credit card | Customers who already have available credit | You have no visibility or control over the terms, and it doesn't appear in your quote |
| Traditional bank loan or broker finance | Very large, planned structural waterproofing projects | Slow approval, often unsuitable for urgent leak repairs |
| PayItMonthly BNPL platform | Firms wanting point-of-quote finance without becoming a lender | Requires customer eligibility checks, so not every applicant will be approved |
Verdict: for damp proofing and waterproofing specialists quoting jobs over a few hundred pounds, point-of-quote instalment finance through a dedicated platform outperforms in-house payment plans or hoping the customer has a spare credit card.
Common mistakes damp proofing and waterproofing firms make
- Quoting the full total with no monthly figure — homeowners anchor on the biggest number in the room and shop elsewhere
- Waiting until the customer objects to mention finance — by then they've already started comparing quotes
- Treating emergency leak repairs and planned tanking jobs the same way — urgent work needs a faster approval path, not the same process as a scheduled project
- Leaving finance out of phone and remote quotes — many damp jobs are quoted over the phone after photos are sent, and finance still needs to be mentioned there
- Not training every surveyor to present finance the same way — inconsistent messaging makes it look optional rather than standard
“If a survey ends with a five-figure invoice and no monthly number, most homeowners walk.”
FAQ
What's the best way to offer instalment plans for damp proofing customers?
Mention the monthly cost during the survey visit, not after the invoice is sent. Damp proofing and waterproofing specialists who present finance as standard, alongside the total price, convert more quotes into booked jobs in 2026 than those who only mention it when a customer hesitates.
Do damp proofing customers qualify for interest-free finance?
Eligibility depends on the finance provider's checks, not the type of job. Damp proofing and waterproofing firms using a platform like PayItMonthly send customers through a standard application rather than assessing credit themselves.
Is instalment finance suitable for emergency waterproofing work?
Yes, provided the application process is fast enough that it doesn't delay the start date. A self-service online application that customers complete before the job is scheduled works better for urgent leak repairs than a phone-based process.
Can customers with a thin credit file still get finance for damp treatment?
That depends on the specific provider's eligibility criteria, which vary. Firms should check current criteria directly with their finance platform rather than assume every applicant qualifies.
How long should instalment plans run for damp proofing jobs?
Match the term to the job size: shorter plans suit smaller remedial jobs, longer plans suit full basement tanking or whole-property waterproofing projects. A single fixed term for every job size tends to under- or over-finance the work.
Do I need a merchant account to offer instalment plans?
Most instalment finance platforms, including PayItMonthly, set up a merchant integration as part of onboarding rather than requiring you to hold a separate account elsewhere. Check the setup process directly with the provider.
What happens if a customer misses a repayment on a financed damp proofing job?
The finance provider, not the damp proofing firm, manages repayment collection and any missed-payment process once the plan is approved and the job is invoiced. Terms vary by provider, so confirm the process before offering finance to customers.
Does offering instalment plans slow down booking a damp proofing job?
It shouldn't, if the application is self-service and approval is near-instant. A slow finance process is the main reason urgent waterproofing customers abandon a financed quote in favour of paying cash or going elsewhere.
One last thing
The surveyors closing more damp proofing jobs in 2026 aren't the ones offering the biggest discount — they're the ones who say the monthly number out loud before the customer asks for it. Instalment plans work best when they're part of the quote itself, not a rescue offer after price shock sets in.


