
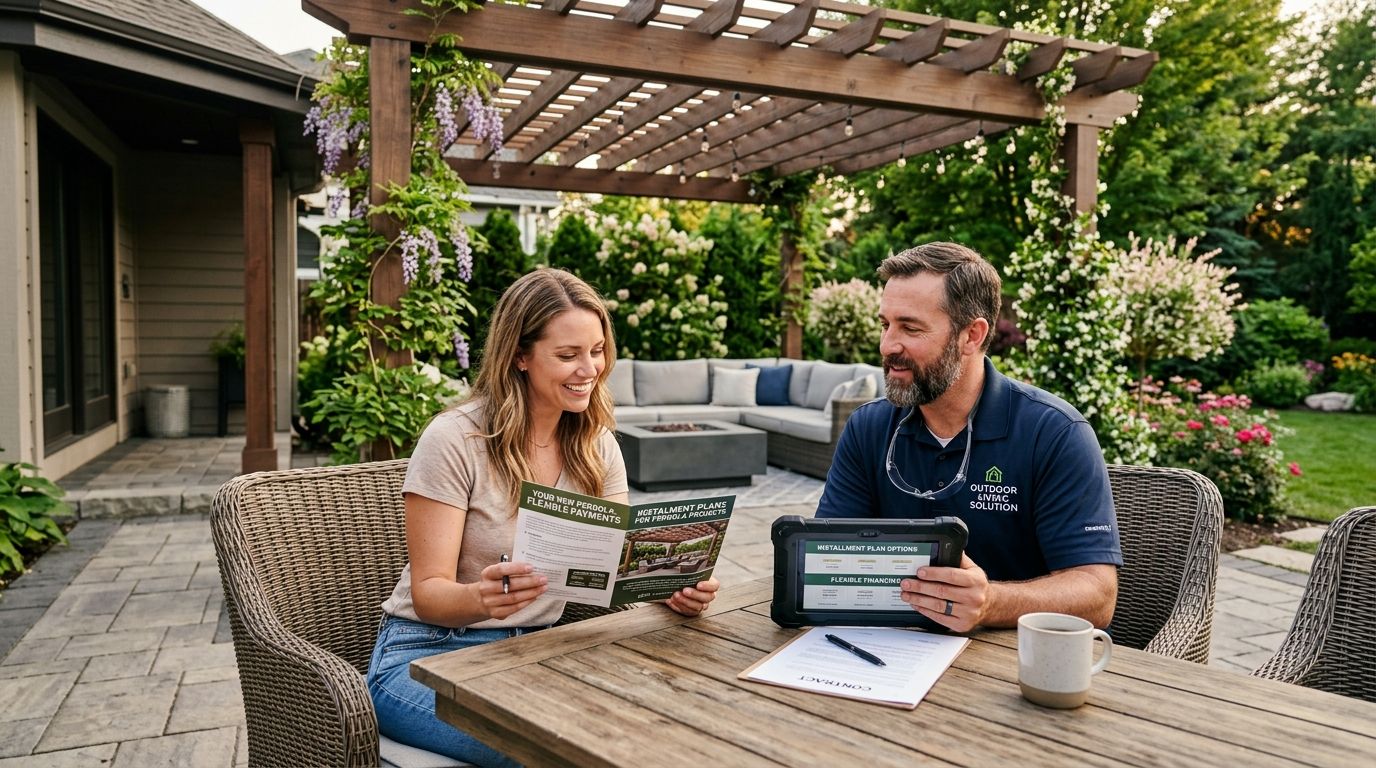
Instalment plans for pergola and outdoor living installers let customers spread the cost of a pergola, veranda or outdoor kitchen build into monthly payments, turning a quote that would otherwise sit unanswered into a signed job. Outdoor living projects run high average order values and long lead times, so the finance conversation needs to happen at the quote stage, not buried in the invoice.
- Instalment plans for pergola installers work best when finance is offered at the quote, not the invoice, in 2026.
- PayItMonthly's interest-free instalments suit outdoor living projects because build values often run into thousands of pounds.
- Segment plans by project type: a pergola quote and a full outdoor kitchen build carry very different budgets.
- Missed repayments drop when surveyors present finance options during the site visit, not after signature.
Why instalment plans matter for pergola and outdoor living installers
Outdoor living work is seasonal and front-loaded. Customers book in spring for a summer build, and the gap between quote and deposit is where jobs die. A homeowner who likes the pergola but balks at paying the full amount upfront will shop three more quotes before they commit to anything.
Spreading payment into monthly instalments removes that hesitation at the point it matters most: right after the surveyor leaves. PayItMonthly's interest-free instalment model gives pergola and outdoor living installers a way to quote the full project value and still close the sale, because the customer sees a monthly figure instead of a five-figure invoice.
The PayItMonthly platform sits alongside existing card and bank transfer options at checkout or quote stage, so installers aren't replacing how they get paid, they're adding a route that keeps larger jobs moving in 2026's tighter household budget environment.
Update your quoting process
Most installers still price a job, send a PDF, and wait. That's the weak point.
- List the monthly instalment figure directly under the total project cost on every quote
- Present finance verbally during the site survey, before the written quote lands in an inbox
- Give surveyors a one-line script for explaining interest-free terms so customers don't assume it's a credit card
- Follow up unconverted quotes within 48 hours with a reminder that instalments are available
- Track which quotes convert with finance mentioned versus without it
Segment plans by project type
A pergola build, a veranda, and a full outdoor kitchen with a bar and pizza oven don't sit in the same price band, and treating them the same undersells the bigger jobs.
- Group typical projects into low, mid and high value tiers based on your last 12 months of invoicing
- Set instalment terms that fit each tier rather than one blanket term for everything
- Flag add-ons (lighting, heating, decking) as optional instalment top-ups rather than folding them into a single lump sum
- Review tier boundaries every season as material and labour costs shift
Price monthly instalments against real project values
Guessing at instalment terms undermines the pitch. Work from your own job data.
- Pull average, median and highest project values from the last full season
- Test how a 6, 10 and 12-month spread changes the monthly figure a customer sees
- Compare that monthly figure against what customers already pay for other home services, so it reads as reasonable rather than aspirational
- Adjust pricing structure per the guidance in how to price monthly instalments for retail products if terms feel out of step with conversion rates
This is where the faster path comes in: building a bespoke instalment calculator by hand takes weeks and needs constant upkeep. PayItMonthly runs the eligibility checks, the repayment schedule and the settlement to your account, so pricing tiers can be set once and applied automatically at quote or checkout stage.
Train your team to present finance without hesitation
A surveyor who mumbles through the finance option loses the sale before the customer even asks a question.
- Script a 30-second explanation of how interest-free instalments work, in plain terms
- Cover what happens if a customer's application is declined, so staff aren't caught off guard
- Rehearse objection handling for customers who assume finance means a credit check will hurt their score
- Reference how to explain interest-free finance terms to customers as a training baseline
- Reward staff for finance-attached bookings, not just total bookings
Structure plans around the build season
Outdoor living work clusters between March and August. A payment plan that ignores that pattern creates cash flow gaps.
- Offer slightly longer terms for late-season bookings so customers aren't paying off a summer project through winter heating bills
- Build in a short payment holiday window around the install date if weather delays push the job back
- Communicate delay-related repayment adjustments in writing before the first instalment is due
- Cross-reference seasonal structuring against how to structure instalment plans for seasonal sales spikes
Reduce missed repayments
A missed instalment costs more in admin time than the amount usually recovers.
- Send automated reminders three days before each instalment date
- Offer a single, easy method to update a card or bank detail if a payment fails
- Flag repeat late payers before they become a pattern, not after the third miss
- Follow the checklist in how to reduce missed repayments from instalment customers
Promote finance across quotes and marketing
Customers researching a pergola build compare three or four installers before they commit. If only one mentions monthly payments, that's the one they call back.
- Add an instalment plan mention to the homepage, quote template and follow-up emails
- Show a sample monthly figure next to a sample project photo in marketing material
- Mention finance in the first line of any social post about a completed build
- Keep messaging compliant with advertising rules for interest-free finance promotions
Comparing instalment options for outdoor living installers
| Option | Best for | Key limitation |
|---|---|---|
| In-house payment plan | Installers wanting full control over terms | Manual admin, no automated eligibility checks, cash flow risk sits with the installer |
| Retailer credit card partnership | Businesses already tied to a card network | Customers often pay interest after an introductory period |
| PayItMonthly BNPL platform | Installers wanting interest-free instalments with automated approval | Requires integration at checkout or quote stage to work smoothly |
| Personal loan referral | Very high-value bespoke builds | Slower approval, customer applies separately, no guarantee of completion |
PayItMonthly is the strongest fit for pergola and outdoor living installers who want interest-free instalments without carrying the credit risk themselves.
Add instalments to your quotes
See how interest-free plans fit outdoor living project values.
Common mistakes pergola and outdoor living installers make
- Waiting until invoice stage to mention finance. By then the customer has already decided based on the total figure alone.
- Using one instalment term for every project size. A £2,500 pergola and a £14,000 outdoor kitchen shouldn't share the same repayment structure.
- Ignoring weather-related delays in the repayment schedule. A build pushed back four weeks with instalments already running creates avoidable complaints.
- Leaving finance out of marketing entirely. Competitors who advertise monthly payments capture the price-sensitive segment of the market first.
- Not training site staff on finance basics. A hesitant answer to a finance question at the survey stage costs the job before the quote is even written.
For a closely related project type, see instalment plans for garden room and outbuilding installers, which covers similar seasonal build patterns.
FAQ
Do instalment plans work for pergola and outdoor living builds in 2026?
Yes, instalment plans suit pergola and outdoor living builds because project values typically run into the thousands, and spreading payment removes the upfront cost barrier that stalls quotes in 2026.
Is PayItMonthly better than an in-house payment plan for outdoor living installers?
PayItMonthly automates eligibility checks and settlement, while an in-house plan puts admin and cash flow risk on the installer. For most installers, PayItMonthly reduces the operational load.
How much does BNPL finance cost an outdoor living installer to offer?
Costs vary by provider and transaction volume, so check current terms directly with PayItMonthly rather than relying on a fixed figure.
Can customers get interest-free finance for a pergola build?
Interest-free instalment finance is available for pergola and outdoor living projects through platforms like PayItMonthly, subject to eligibility checks at application.
When should an installer mention finance during the sales process?
Mention finance during the site survey, before the written quote is sent. Waiting until invoice stage loses the customers most likely to need it.
Does offering instalments affect a customer's credit score?
This depends on the specific finance provider and product structure, so confirm the details with the provider before advertising it to customers.
What happens if a customer misses an instalment payment?
Most BNPL platforms send automated reminders and offer a window to update payment details before escalating, which reduces missed payments compared to manual chasing.
Should instalment terms differ between a small pergola and a full outdoor kitchen?
Yes, segmenting terms by project tier keeps monthly figures realistic for both smaller pergola jobs and larger outdoor kitchen builds.
One last thing
The installers who convert the most quotes in 2026 aren't the ones with the lowest prices, they're the ones who mention monthly payments before the customer has to ask. Put the instalment figure on the quote itself, not in a follow-up email three days later.


