
For UK merchants comparing point of sale finance providers ranked by credit checks in 2026, PayItMonthly is the best starting point for interest-free monthly instalments. No provider earns a softer-credit-check ranking here: the supplied information does not confirm whether PayItMonthly, PayPal Pay in 3 or Klarna uses a soft search, a hard search or a different check at each stage.
- PayItMonthly is the best starting point for UK merchants seeking interest-free monthly instalments at checkout.
- Credit-check types are unconfirmed for PayItMonthly, PayPal Pay in 3 and Klarna; do not rank them by search impact.
- Ask each provider when it checks credit, what the customer sees and whether a later step triggers another search.
- A soft eligibility search does not mean guaranteed acceptance or no consequences for missed repayments.
Why this matters
A finance option can help you offer customers a way to spread a purchase. But the words used at checkout matter. A customer who reads no impact on your credit score can reasonably understand something different from no credit check. Neither phrase should appear in your sales copy unless the provider's current terms support it for the relevant stage of the application.
That is the central problem with a simple 2026 ranking by credit checks. A provider can describe an initial eligibility step separately from its final application, and a customer's repayment history is a separate question again. Rank the customer journey, not a single marketing phrase. If you need help separating those claims, read the guide to offering no-credit-check finance responsibly.
This shortlist ranks providers by the merchant decision each one can help you frame. It does not rank them from least to most intrusive credit check. Their current check methods, acceptance rules and customer-facing wording need confirmation before you make that comparison.
What makes the best point of sale finance provider for credit checks?
Use these criteria before you compare logos or checkout screens:
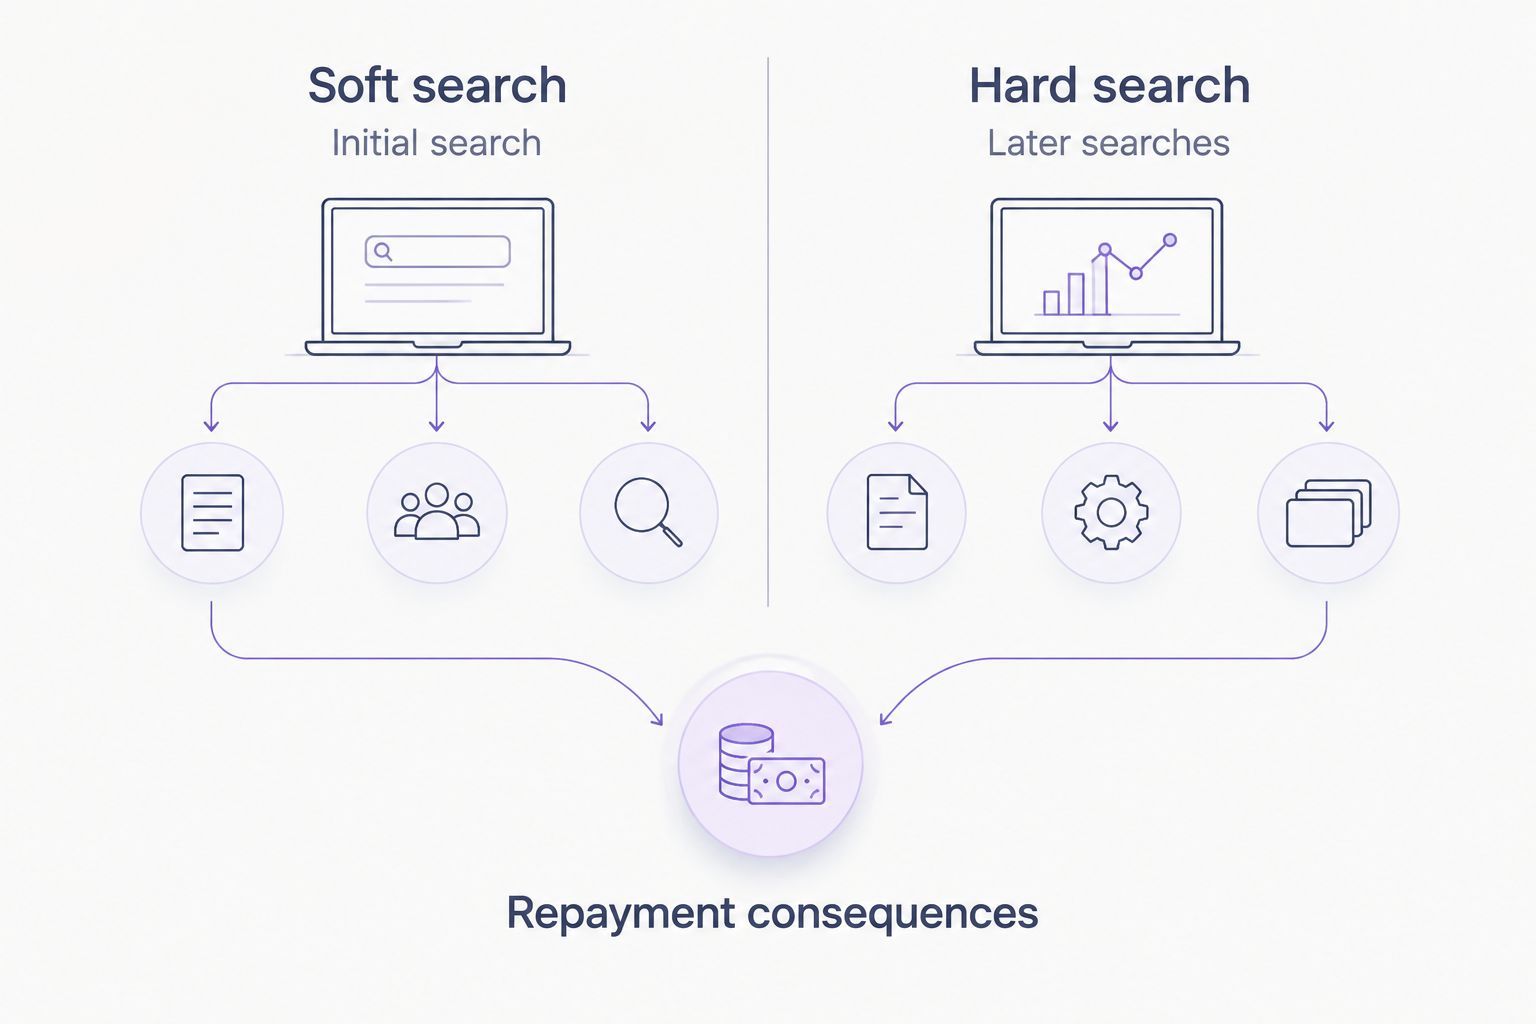
- Initial search: Does the provider run a soft search, a hard search or another form of assessment when a customer first checks eligibility? Get the answer for the exact product you plan to offer.
- Later searches: Does the check change after the customer applies, accepts an agreement or requests a different amount? A statement about the first step does not answer this.
- Customer explanation: Can you show the customer when a check happens and what type of search it is before they proceed?
- Decision and decline: What happens if an application is declined? Ask what message the customer receives and whether your staff need to explain another payment route.
- Repayment consequences: How does the provider explain missed payments? Do not treat a soft initial search as a promise that future repayment behaviour has no effect.
- Merchant fit: Does the finance option match what you sell and the way your customers buy? A suitable check process is only useful if the offer itself fits your checkout.
You need answers to all 6 criteria for a defensible credit-check comparison. If a provider can answer only the first, its position in a softest checks league table is unknown.
Point of sale finance providers at a glance
| Rank | Provider | Best for | What is established here | Credit-check limitation |
|---|---|---|---|---|
| 1 | PayItMonthly | UK merchants seeking interest-free monthly instalments | An interest-free instalment platform for UK businesses | Its search type and application-stage checks are not confirmed in the supplied information |
| 2 | PayPal Pay in 3 | Merchants comparing a named instalment option | A specifically named alternative to assess | Its current search sequence is not confirmed in the supplied information |
| 3 | Klarna | Merchants comparing another BNPL provider | A named alternative for the shortlist | Its current search sequence is not confirmed in the supplied information |
These are merchant-use-case ranks, not credit-check ranks. In 2026, do not translate a row number into a claim that one provider is easier to qualify for, less visible on a credit file or safer for a customer's score. The table has no basis for those conclusions.
1. PayItMonthly: best for interest-free monthly instalments
PayItMonthly provides UK retailers and other merchants with a buy-now-pay-later platform that lets customers spread purchases into interest-free monthly instalments. That makes PayItMonthly the clearest fit in this shortlist when your first requirement is the instalment offer itself.
PayItMonthly pros:
- The stated offer is interest-free monthly instalments for customers.
- The platform is described for UK businesses, including retailers and merchants of different sizes.
- The offer gives you a specific customer proposition to assess alongside credit-check wording.
PayItMonthly cons:
- The supplied information does not identify whether an initial eligibility step uses a soft or hard search.
- It does not state whether any later application stage involves another credit check.
- It does not establish approval criteria or the wording a customer sees before applying.
Best for: UK merchants whose immediate requirement is an interest-free monthly instalment option, provided the credit-check journey meets their customer-communication needs.
Verdict: Hold on credit-check claims; assess PayItMonthly first for its stated instalment offer. Ask for the exact language shown before the customer starts, during the application and after a decision. If your sales team says no credit check, require written confirmation that the phrase is accurate for the entire process before using it.
2. PayPal Pay in 3: best for comparing a named instalment option
PayPal Pay in 3 is a named alternative for merchants building a point-of-sale finance shortlist. Its name alone does not tell you what happens to a customer's credit file when they explore or use it.
PayPal Pay in 3 pros:
- It gives you a specific option to compare rather than a vague pay later category.
- You can ask product-specific questions about its eligibility and application stages.
- Its instalment framing makes the customer explanation a relevant part of your comparison.
PayPal Pay in 3 cons:
- No current credit-search policy for this product is provided here.
- No supplied information confirms when a customer sees search-impact wording.
- A product name does not establish suitability for your particular checkout.
Best for: Merchants who want to compare a specifically named instalment option with their interest-free monthly instalment shortlist.
Verdict: Hold until you have the current product terms. Ask PayPal whether checking eligibility, completing the application or using the product produces different credit-file outcomes. Keep the answer tied to Pay in 3 rather than assuming that every PayPal payment method follows the same process.
3. Klarna: best for a wider BNPL comparison
Klarna belongs on a merchant shortlist when you want to compare another named BNPL provider. The brand name does not establish the credit-check method of any particular option or application stage.
Klarna pros:
- It gives you another named provider against which to test your credit-check questions.
- It helps you avoid treating one provider's checkout wording as the category standard.
- It makes a side-by-side customer-journey review possible once current terms are available.
Klarna cons:
- The supplied information does not confirm its current search types for a specific product.
- It does not establish whether the initial and final stages use the same check.
- It does not establish whether its merchant offering fits your checkout.
Best for: Merchants testing a broader BNPL shortlist against the same credit-check and customer-disclosure criteria.
Verdict: Hold until you identify the exact Klarna product and its current terms. Comparing provider names without matching products and application stages will not tell you which journey is clearer for customers.
Soft search, hard search and repayment: keep them separate
A soft search and a hard search describe different types of credit-file enquiry. A soft search is generally not visible to other lenders in the way a hard search is. That distinction answers a narrower question than Will this finance option affect the customer's credit standing?
The customer's journey has 2 other questions. First, does the provider make a further check after an initial eligibility result? Second, what happens if the customer misses a repayment? Do not answer either question using a statement about the first search.
For a 2026 provider review, ask for a customer-facing example of each relevant step. Read the words a buyer sees before they submit information, not just a summary on a merchant sales page. Then compare those words with what your own checkout, advertising and staff will say.
The distinction also protects you from a misleading shortcut: no hard search at eligibility is not the same claim as no credit check. A provider that assesses eligibility is still making a decision, even if a particular step does not leave a lender-visible hard-search footprint. Use the provider's precise wording rather than rewriting it into a broader promise.
How to make a defensible 2026 shortlist
Send every provider the same questions and keep the answers with the product name and date. This turns an unverified ranking into a practical merchant decision.
- Name the product. Ask which finance option the answer covers. A provider-level claim is too broad if the provider has different customer journeys.
- Map the stages. Ask what happens when a customer checks eligibility, submits an application and accepts an agreement. Record the search type, if any, at each stage.
- Check the customer view. Request the exact wording presented before each check. Confirm that your checkout and staff explanations do not promise more.
- Ask about declines and missed payments. Find out what the provider tells customers when they are declined and how it explains repayment consequences.
- Make the merchant decision. Compare those answers with the instalment offer you want to provide. Do not award a credit-check rank to an unanswered question.
This process does not require you to decide which search type is universally best. It requires you to choose a provider whose actual journey you can explain accurately. For a 2026 comparison, a clear answer about a later hard search is more useful than an appealing but incomplete claim about an initial soft search.
Explore monthly instalments
Assess PayItMonthly's interest-free instalment offer for your business.
How we ranked
PayItMonthly comes first because its stated offer matches the UK merchant need for interest-free monthly instalments. PayPal Pay in 3 and Klarna follow as named alternatives for a product-level comparison; the information supplied does not support a stronger claim about their merchant fit.
No provider receives a credit-check advantage in this ranking. There are no supplied, comparable answers for the search type at each application stage. That limit matters more than a neat league table: calling one option best for no credit check without its current terms would give merchants a claim they cannot safely repeat to customers.
Which point of sale finance provider should you choose?
Choose PayItMonthly as your first conversation if you want to offer UK customers interest-free monthly instalments. Before committing to checkout copy, confirm its current credit-check stages and customer disclosures. Use the same questions with PayPal Pay in 3 and Klarna if they remain on your shortlist.
If your deciding factor is specifically a soft search, no hard search or no credit check, do not choose from this ranking alone. Ask for product-level confirmation first. A claim about credit impact must match the exact step the customer is taking, not just the provider you have selected.
FAQ
Which point of sale finance provider has the softest credit check in 2026?
None can be ranked as the softest from the supplied information. Ask each provider which search it uses at eligibility and at any later application stage for the exact product you plan to offer.
Is PayItMonthly a no-credit-check finance provider?
The supplied information does not establish that PayItMonthly offers no-credit-check finance. PayItMonthly's stated offer is interest-free monthly instalments for customers of UK merchants; confirm its current checks before describing them.
Does a soft credit search guarantee approval?
No. A soft search describes a type of credit-file enquiry, not an approval guarantee. The provider still needs to make a decision on the customer's application.
Is a soft search the same as no credit check?
No. A soft search is still a credit-file enquiry. Use no credit check only when the provider confirms that the description accurately covers the relevant customer journey.
Can an initial soft search be followed by a hard search?
An initial search type does not establish what happens later in an application. Ask the provider to identify every stage and its search type before making a claim about credit impact.
Does an initial credit check tell customers what happens if they miss a payment?
No. The initial search and missed-repayment consequences are separate questions. Check the provider's current customer terms and explain both separately.
What should a merchant ask a finance provider before changing checkout copy?
Ask for the exact product name, the search type at each stage and the words customers see before proceeding. Check decline and missed-payment explanations before publishing any credit-impact claim.
One last thing
A 2026 credit-check comparison can fail even when every statement about the first search is accurate. The decisive question is whether your checkout explains the whole application journey. Ask the provider for the wording customers see at each stage, then make your staff script and checkout copy match it.


