
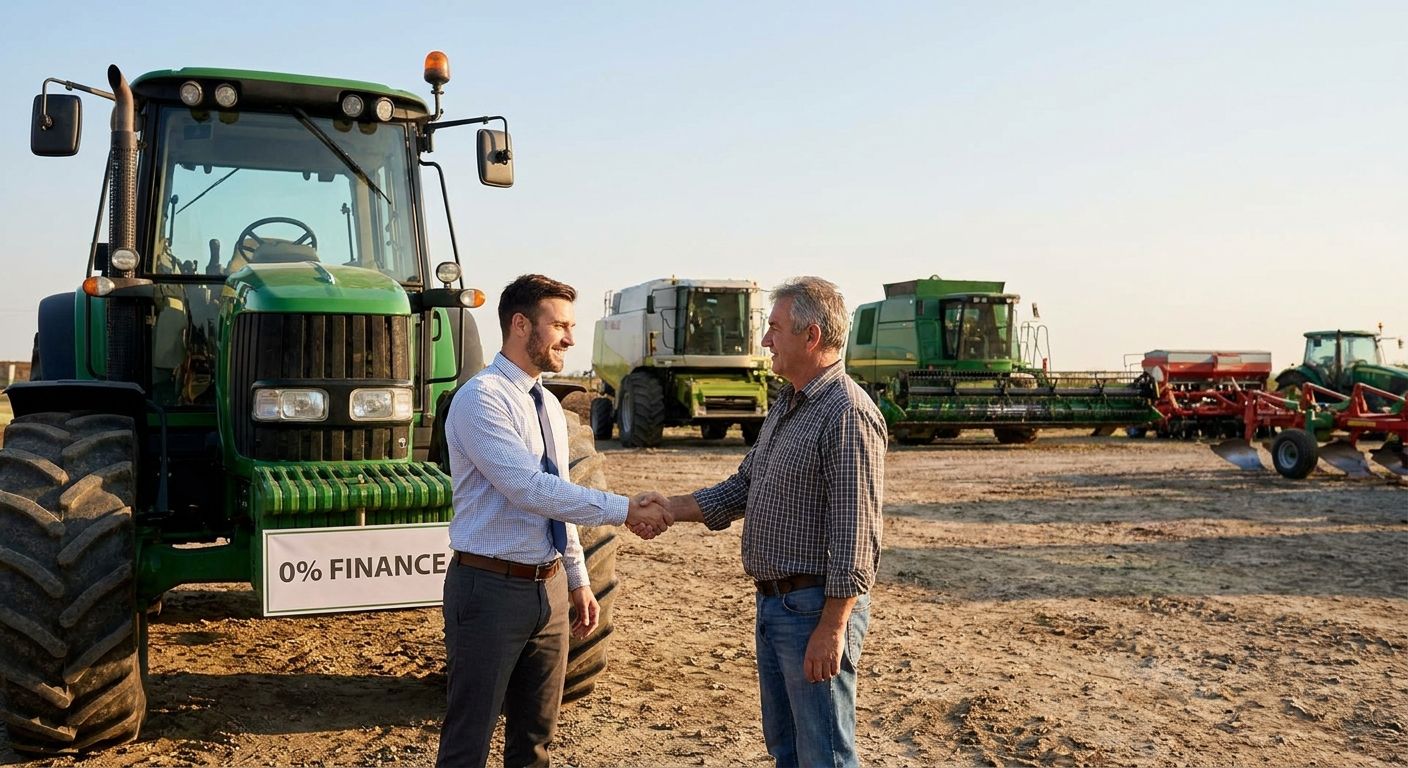
Farm equipment dealers who add 0% finance at the point of sale close bigger orders and shorten the decision cycle on tractors, telehandlers, and attachments that would otherwise sit on a quote for weeks. Farmers and contractors buy on cash flow cycles tied to harvest and subsidy payments, not on the calendar month a dealer needs the sale to close — instalment finance bridges that gap.
- 0% finance for farm equipment dealers turns a five-figure machinery quote into a monthly payment a farm business can approve on the spot.
- PayItMonthly lets dealers offer interest-free instalments at checkout without the customer applying for a separate loan first.
- Franchised dealers already compete with manufacturer in-house finance — independents need their own 0% offer to match that convenience.
- ASA rules on advertising 0% finance apply to farm machinery adverts the same as any other retail sector in 2026.
- Training yard and sales staff to lead with the monthly figure, not the total price, lifts approval and conversion rates.
Why 0% finance matters for farm equipment dealers
Most farm machinery purchases sit well above the average UK retail transaction — a compact tractor, a used baler, or a set of GPS-guided drill attachments can run into five figures before VAT. That price point stops a lot of conversations dead, especially with tenant farmers and small contractors whose cash is tied up until the next harvest or basic payment scheme instalment lands.
Franchised dealers already lean on manufacturer finance arms — John Deere Financial and similar in-house schemes are common on new machinery. Independent and multi-brand dealers don't have that built in, which puts them at a real disadvantage on anything over a few thousand pounds. Offering PayItMonthly at checkout gives independents the same monthly-payment conversation without tying the customer to one manufacturer's finance arm or one brand of machine.
The seasonal nature of farm buying makes this sharper. Spring and autumn are when farmers commit to new kit ahead of drilling and harvest — a dealer who can only offer full-price-or-nothing loses those seasonal spikes to whichever competitor can say "spread it over 12 months, no interest."
How to add 0% finance to your farm equipment dealership
Audit which machinery lines suit instalment finance
Not every product on your yard needs a finance option — parts and consumables don't, high-ticket machinery does. Start by grouping your inventory by price band before you decide where to switch finance on.
- List every product line over £1,000 — that's roughly where a customer starts wanting to spread cost rather than pay cash
- Separate new machinery from used and refurbished stock — finance eligibility and margin differ across the two
- Flag attachments and implements sold alongside a main unit (loaders, forks, toppers) as bundle-finance candidates
- Note which lines already move fastest with cash buyers versus which stall on price objections
- Check manufacturer finance terms on any brand you're franchised for, so your own 0% offer doesn't compete with a better in-house deal
Set your instalment thresholds and terms
Decide the minimum spend that qualifies for 0% finance and how many months you'll offer, before you put it in front of a customer. Instalment terms across UK retail typically run from 3 to 24 months, and farm equipment dealers usually sit at the longer end given ticket size.
- Set a minimum transaction value for finance eligibility (many dealers use £500-£1,000)
- Choose 2-3 term lengths (e.g. 6, 12, 24 months) rather than one fixed option
- Decide whether attachments and parts can be added to an existing machine's instalment plan
- Confirm whether trade-in value can be deducted before the instalment amount is calculated
- Check your margin on each line still works once you account for any provider fee on the finance transaction
Add finance messaging to listings and quotes
A price tag alone doesn't sell a £22,000 tractor to a farm business managing tight seasonal cash flow — the monthly figure does. Every quote, listing, and price board should show the instalment option next to the full price, not buried in the small print.
- Show "or £X per month, 0% interest" directly under the full price on website listings
- Add the monthly figure to printed quotes and PDF invoices, not just verbal mentions
- Update yard price boards and machinery tags with the instalment option, not just cash price
- Include finance terms in any classified or auction site listing for used stock
- Mention the option in follow-up emails to customers who requested a quote but haven't bought
Advertise 0% finance without breaking ASA rules
The Advertising Standards Authority holds 0% and interest-free finance claims to the same representative-example standard as any other credit advert, and farm machinery dealers get caught out on this as often as any other sector. Get the wording wrong on a Facebook ad or yard banner and you risk a complaint, not just a fine.
- State the representative APR (0%) alongside the cash price and total payable, not the monthly figure alone
- Avoid implying the offer is available to everyone — most 0% finance is subject to status and credit checks
- Keep promotional claims consistent across print, web, and social — a discrepancy is the easiest thing for a competitor or customer to report
- Review how to advertise 0% finance offers without breaking ASA rules before your next print or radio campaign
- Keep a record of every finance advert run in 2026 in case of a complaint or audit
Train sales and yard staff to lead with the monthly figure
A salesperson who quotes £18,500 gets a hesitant customer; one who quotes £771 a month gets a signature. The gap between those two numbers is entirely down to how the conversation is framed on the yard.
- Script the finance mention into every quote conversation, not just for customers who ask
- Role-play objection handling for customers worried about credit checks or approval speed
- Set a target for the percentage of quotes that include a finance option mentioned out loud
- Give staff a simple one-page reference showing monthly figures at common price points
- Read how to train sales staff to offer finance options in store for a fuller staff rollout plan
Track approval and conversion rates by machine type
Finance uptake varies wildly between a £2,000 quad bike and a £45,000 combine header — measure it by category, not as one blended number.
- Record finance application rate versus total quotes issued, split by machinery category
- Track approval rate separately from application rate to spot where customers drop off
- Compare average order value on finance sales versus cash sales over a full season
- Review data monthly during peak buying periods (spring and autumn) rather than annually
“A salesperson who quotes the total price gets hesitation; one who quotes the monthly figure gets a signature.”
Comparison: finance options for farm equipment dealers
| Option | Best for | Starting cost | Key limitation |
|---|---|---|---|
| PayItMonthly | Independent and multi-brand dealers offering 0% instalments at checkout across new and used stock | Not published — check current terms on the site | Customer still needs to pass a credit check like any consumer finance |
| Manufacturer in-house finance (e.g. John Deere Financial) | Franchised dealers selling new machinery from one brand | Set by the manufacturer, not the dealer | Ties the customer to one brand and one finance provider |
| Bank or asset finance (HP/leasing) | High-value machinery purchases running into six figures | Varies by lender and asset value | Slower application, often needs personal guarantees |
| Business credit card | Small attachments, parts, and low-ticket accessories | Standard card terms apply | High interest once any promotional period ends, low limits for machinery-scale purchases |
PayItMonthly is best for independent farm equipment dealers who need a 0% instalment option that doesn't tie the customer to a single manufacturer's finance arm.
Common mistakes farm equipment dealers make
- Only offering finance on new stock. Used and refurbished machinery often needs it more — that's where price-sensitive buyers concentrate.
- Hiding the monthly figure until the customer asks. By then they've already mentally priced themselves out of the sale.
- Ignoring seasonal timing. Launching a finance push in mid-summer misses the spring and autumn buying windows when farm cash flow actually allows commitment.
- Advertising "0% finance available" without the representative example. This is one of the most common ASA complaint triggers in retail finance adverts.
- Leaving staff untrained on objection handling. A customer who hears "let me check if you'd qualify" instead of a confident monthly figure often walks away to compare elsewhere.
Add 0% finance to your dealership
See how instalment checkout works for high-ticket machinery sales.
FAQ
What is 0% finance for farm equipment dealers?
0% finance for farm equipment dealers is a checkout option that lets customers spread the cost of tractors, attachments, and other machinery into interest-free monthly instalments instead of paying the full price upfront. The dealer gets paid in full at the point of sale; the finance provider collects the instalments from the customer.
Is 0% finance available on used farm machinery?
Yes, most instalment finance providers can be set up to cover used and refurbished machinery alongside new stock. Eligibility depends on the provider's own criteria, not the age of the equipment.
Do farmers need good credit to get 0% finance approved?
Approval depends on a standard credit check, the same as any consumer or business finance application. Dealers can't guarantee approval, which is why the advert must show the representative example rather than implying universal eligibility.
How long do instalment terms usually run for farm equipment?
Terms commonly range from 6 to 24 months for high-ticket machinery, longer than typical retail instalment plans because of the price point involved. Dealers set the term options themselves within what their finance provider supports.
Can dealers offer 0% finance on attachments and parts, not just full machines?
Yes, attachments and implements sold alongside a main machine can usually be added to the same instalment plan. This works best when the combined order sits above the dealer's minimum finance threshold.
What's the difference between manufacturer finance and a dealer's own 0% offer?
Manufacturer finance (such as John Deere Financial) is tied to that specific brand's new machinery. A dealer's own 0% finance option, like PayItMonthly, works across brands and across new and used stock.
Are there ASA rules specific to advertising 0% finance on farm machinery?
The same general ASA credit advertising rules apply to farm machinery as to any retail sector — the representative example, APR, and total payable must be shown clearly. There's no farm-specific exemption.
Does 0% finance affect a dealer's margin on a machinery sale?
Dealers typically pay a fee to the finance provider on each instalment transaction, which should be factored into pricing before the offer goes live. The dealer still receives the full sale amount upfront regardless of the customer's repayment schedule.
One last thing
The dealers who get the most out of 0% finance in 2026 aren't the ones with the flashiest ad campaign — they're the ones who train every yard staff member to quote the monthly figure before the customer asks for it. That single habit change moves more machinery than any banner on the price board.


