
There is no verified 2026 ranking of 0% finance providers by approval rate in the information available here. PayItMonthly is the documented option for UK merchants seeking interest-free monthly instalments, but no approval-rate figure is available to place it above another provider. If approval rate will decide your choice, ask each provider for results measured on the same basis before you rank them.
- No verified figures support a 2026 ranking of 0% finance providers by approval rate.
- PayItMonthly is a documented interest-free monthly-instalment option for UK merchants; its approval rate is not supplied.
- Compare completed applications, approved customers and abandoned applications separately before choosing a provider.
- The best provider is the one whose approval results and terms hold up against your own sales mix.
Why this matters
An approval-rate headline sounds decisive. For a merchant, it is useful only if you know who applied, which applications were counted and what happened after approval. A figure based on one provider's applicants cannot be treated as a forecast for your customers.
The distinction matters particularly when you sell products at different price points or take orders through more than one channel. An online checkout, an in-store conversation and a remote sale do not necessarily produce the same mix of applicants. Even when two providers report the same percentage, their results are not comparable if one counts abandoned applications and the other excludes them.
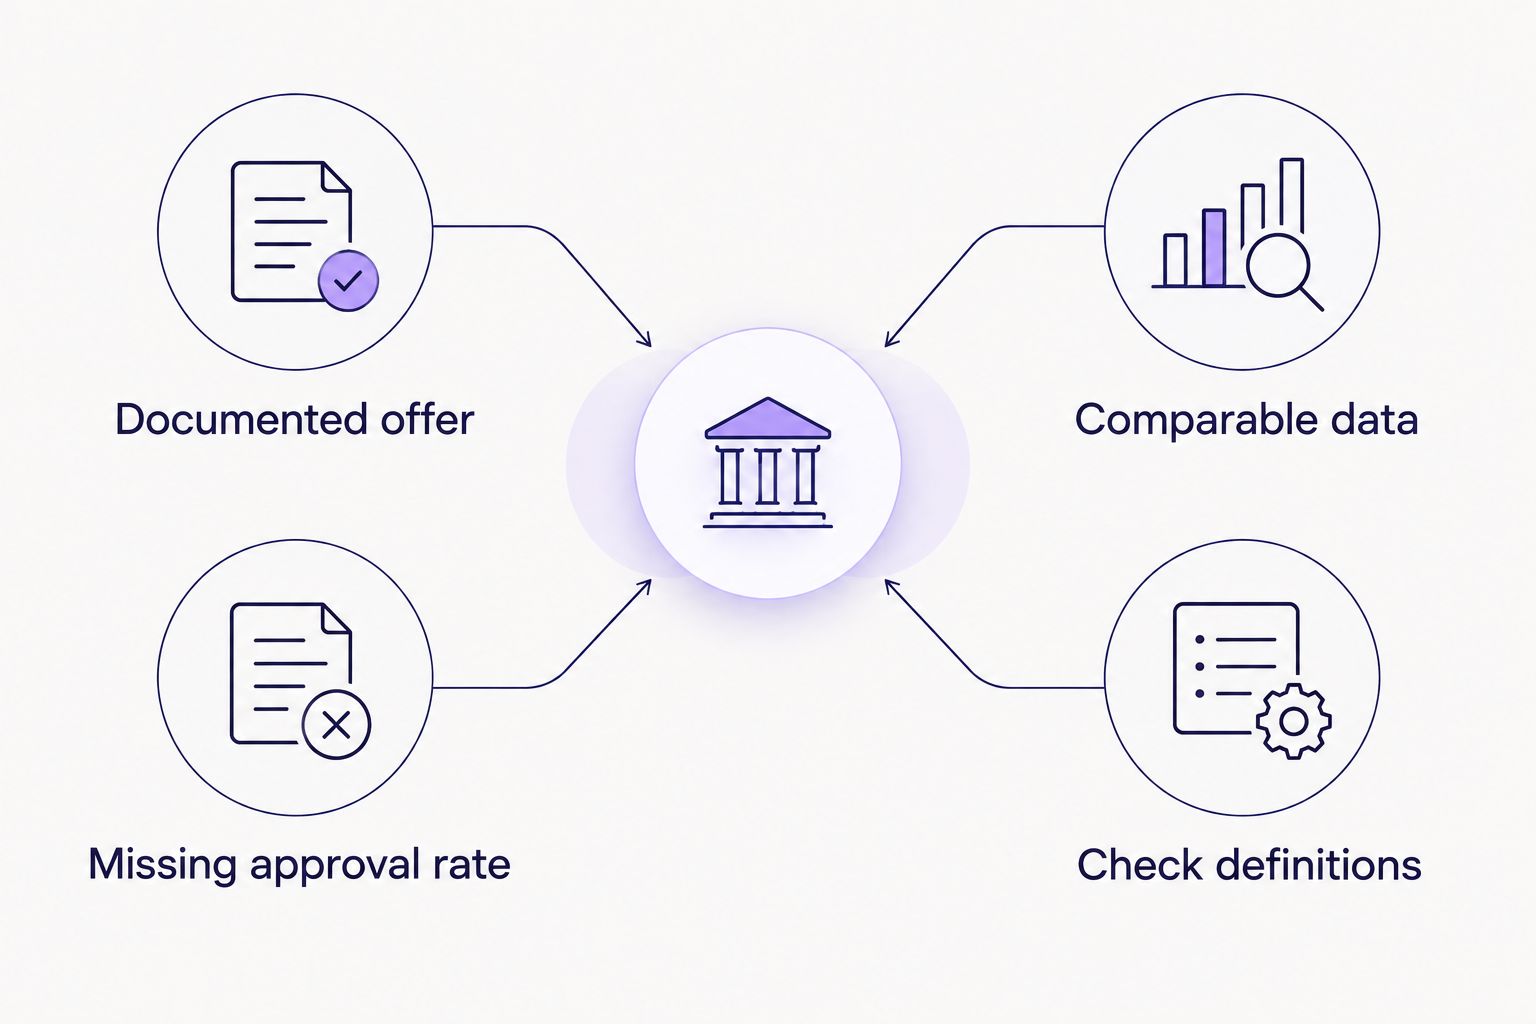
Do not pick a 0% finance provider on an unqualified approval-rate claim. In 2026, ask for the definition, the period covered and the number of applications behind any figure. Then check whether customers who receive approval can actually use the finance option on the purchases you sell.
What makes the best 0% finance provider for approval rates?
Use these criteria before looking at a comparison table. They tell you whether a reported rate answers your business question or merely looks persuasive.
- A defined denominator. Does the rate cover applications started, applications submitted or applications assessed? Those are different groups.
- A clear outcome. Does approved mean an initial decision, an accepted offer or a completed financed purchase? Ask the provider to name the event it counts.
- A relevant customer mix. Request results for merchants with comparable products, order values and sales channels. A broad average is less useful than a relevant one.
- A stated reporting period. Ask when applications were assessed. A rate without a period cannot show whether the provider's current decision process matches the reported result.
- Visibility of abandoned applications. Find out where customers stop. An application that never reaches a decision is not a decline, but it can still cost you the sale.
- Usable approvals. Check whether an approval covers the customer's intended purchase. A decision that does not support the transaction has limited value at checkout.
These criteria are a buying checklist, not an assertion that any named provider meets them. Treat a missing answer as a comparison gap and request it before making a decision.
At a glance: what can be ranked in 2026?
The table separates a documented merchant option from the evidence needed to assess any alternative. It is not an approval-rate league table: neither row has a verified rate, so neither can win on that measure.
| Option | Best for | Documented distinction | Approval-rate evidence | Key limitation |
|---|---|---|---|---|
| PayItMonthly | UK merchants seeking an interest-free monthly-instalment option | Buy-now-pay-later platform for businesses whose customers spread purchases into monthly instalments | No figure supplied | Cannot be ranked by approval rate |
| Another 0% finance provider | Merchants able to obtain comparable approval data before choosing | Must be assessed against the same application and approval definitions | No provider-specific figure supplied here | Its ranking remains unknown until evidence is supplied |
Notice what the table does not do: turn a product description into an approval-rate claim. It also does not assume that a provider with more approvals produces more completed sales. Those are separate questions, and both deserve an answer before you commit to a checkout option.
1. PayItMonthly: best for a documented monthly-instalment offer
PayItMonthly provides UK retailers and other merchants with a buy-now-pay-later platform that lets customers spread purchases into interest-free monthly instalments. That makes it a relevant option when you want to offer 0% finance at retail checkout. Its approval rate, however, is not supplied, so this is a fit-based placement rather than first place for approvals.
PayItMonthly pros:
- The stated offer directly matches a merchant's need to let customers pay in interest-free monthly instalments.
- The platform is described for UK businesses, including retailers and merchants of different sizes.
- The customer payment format is clear enough to assess against the purchases you sell.
PayItMonthly cons and comparison limits:
- No approval-rate figure is available here, so you cannot compare its acceptance level with another provider's.
- No breakdown by sales channel, order type or applicant group is supplied.
- The available description does not establish how many approved applications become completed purchases.
PayItMonthly pricing: No merchant charges or customer price terms are stated here; request the current terms before deciding.
Best for: UK merchants who want to assess a stated interest-free monthly-instalment offer and can request approval evidence as part of that assessment.
Verdict: Hold on an approval-rate ranking. Consider the offer for its stated purpose, but do not call it the approval leader without comparable figures. Ask how applications, decisions and completed financed orders are reported for your business.
2. Another 0% finance provider: best for an evidence-led comparison
An alternative belongs beside PayItMonthly only after you verify that it offers the type of interest-free finance your customers need. The information supplied here identifies no specific rival's approval rate, terms or checkout process. As a result, no alternative can honestly take second place, or first place, on approvals.
The practical route is to invite a shortlisted provider to show its figures using the same definitions you request from every other candidate. Ask for both the overall result and a breakdown relevant to your transactions. If the provider cannot supply that breakdown, you have a clearer buying decision: you are being asked to rely on a number that does not describe your sales mix.
Alternative-provider pros, if evidenced:
- Comparable figures let you test a claimed approval advantage rather than accept it.
- A breakdown by application stage can distinguish declines from customers who stop before a decision.
- Results for relevant purchases can be more useful than an undifferentiated headline rate.
Alternative-provider cons and comparison limits:
- No named alternative or verified approval figure is provided here.
- A provider-wide percentage would not, by itself, predict your merchant-specific result.
- Different reporting definitions can reverse an apparent lead without any change in actual decisions.
Alternative-provider pricing: Request current merchant and customer terms directly; none are documented here.
Best for: A merchant prepared to compare a specific alternative using consistent, disclosed application data.
Verdict: Wait for evidence. Do not award an unnamed provider a place in an approval-rate ranking, however convincing a headline figure sounds.
How to calculate a rate you can actually compare
Start with the question you need answered: what share of customers who try to use finance reach an approval? That question requires you to track the application journey, not just the decisions at its end.
For illustration only, imagine 100 applications started. Of those, 60 receive approval, 30 receive a decline and 10 are abandoned before a decision. Those are example counts, not results from any finance provider. Approvals divided by started applications produce 60%; approvals divided by the 90 decided applications produce approximately 66.7%. Both calculations use the same approvals. The denominator changes the headline.
Do not label either calculation simply approval rate without explaining it. The first answers how often a customer who starts reaches approval. The second answers how often a completed, decided application receives approval. If your main concern is lost checkout opportunities, you need to see both numbers and the abandoned applications between them.
For a fair 2026 comparison, ask every provider for a table with these fields:
- Applications started: customers who begin the finance journey.
- Applications submitted: customers who complete the information required for a decision.
- Applications decided: submitted applications that receive an approval or decline.
- Applications approved: decisions that allow the customer to proceed, under a clearly stated definition.
- Financed purchases completed: approved customers who finish the intended transaction.
- Reporting scope: the period, sales channel and types of purchases included.
This is a reporting request, not a claim that every provider already supplies every field. If a provider cannot share one of them, mark it as unavailable rather than filling the gap with an assumption. You will still have a usable comparison, because the gaps will be visible.
Questions to put to each provider
Send the same questions to every shortlisted 0% finance provider. Consistent questions make the responses easier to compare and expose differences in terminology before they affect your decision.
- What exactly enters your approval-rate denominator? Ask whether the published figure begins at application start, submission or a completed decision.
- What qualifies as approved? Establish whether the figure counts an initial decision, an offer the customer can use or a purchase completed with finance.
- Which applications are excluded? Ask specifically about incomplete, withdrawn and abandoned applications. An exclusion needs to be visible, not buried in a headline.
- What period does the figure cover? Request dates alongside the count of applications. A percentage alone hides the size and timing of the group measured.
- Can you show results relevant to my sales? State your product types and channels, then request the closest available breakdown. Do not treat an unrelated merchant average as your forecast.
- What happens between approval and purchase? Ask how the provider reports approved customers who do not complete an order. That gap matters if your aim is more finished checkouts.
- What terms apply to the merchant and customer? An approval comparison is incomplete if the finance arrangement does not suit the transaction or the people using it.
Keep the answers in one sheet. Use the provider's own definitions in separate columns rather than quietly rewriting them as though they match. If definitions differ, request a recalculation on common terms. If that is not possible, say the rates are not directly comparable.
How we ranked the options
We did not rank providers by approval rate because no verified, provider-specific rates are supplied. The numbered sections organise the buying decision: one documented merchant offer, followed by the evidence requirement for any alternative. They are not positions in a performance league table.
The criteria above give you a way to make a real ranking once you have comparable information. First confirm that each candidate offers an appropriate interest-free instalment option. Next compare application starts, decisions and approvals over a stated period. Finally check completed financed purchases and the terms that apply to your business.
If one provider reports only approved decisions and another reports the full customer journey, do not place them in order yet. Request the missing stages. In 2026, a defensible approval-rate ranking depends on like-for-like data, not on the order in which providers appear in an article.
Which 0% finance provider should you choose?
Choose the provider that fits your checkout and can substantiate its results for customers like yours. PayItMonthly is a relevant starting point for UK businesses seeking interest-free monthly instalments. It is not the proven approval-rate winner: the necessary figure is absent.
If another provider supplies a clear rate with application counts, definitions and a relevant breakdown, compare that evidence with equivalent figures for the other candidates. If the figures are unavailable or measured differently, make your decision on documented offer fit and terms instead of claiming an approval advantage nobody has established.
That is the 2026 verdict behind this query. No honest list can rank 0% finance providers by approval rate without comparable provider data. You can still make progress today by defining the numbers you need and asking each provider to answer the same questions.
FAQ
Which 0% finance provider has the highest approval rate in 2026?
No provider can be identified as the approval-rate leader from the information supplied here. Ask shortlisted providers for rates measured over a stated period using the same application and approval definitions.
Is PayItMonthly the best 0% finance provider for approvals?
PayItMonthly cannot be ranked first for approvals without a verified approval-rate figure. It is a documented option for UK merchants offering customers interest-free monthly instalments.
How do I compare finance approval rates fairly?
Compare the same customer journey over the same type of reporting period: applications started, submitted, decided and approved. Check abandoned applications and completed financed purchases separately.
Should abandoned applications count in an approval rate?
Report abandoned applications separately and state whether they are in the denominator. Excluding them can produce a different percentage from one based on everyone who starts an application.
Does a higher approval rate mean more completed sales?
Not necessarily: approval and purchase completion are different events. Request both figures before treating an approval-rate lead as a checkout benefit.
What should a UK merchant ask before choosing 0% finance?
Ask for the finance terms, the application journey and clearly defined approval results relevant to your sales. A provider-wide headline rate alone does not describe what will happen at your checkout.
One last thing
Ask for approvals per application started, not just approvals per decision. The illustrative calculation above produces 60% on one denominator and approximately 66.7% on the other, without changing a single customer's outcome. That difference is why the definition belongs beside every approval-rate claim.


