
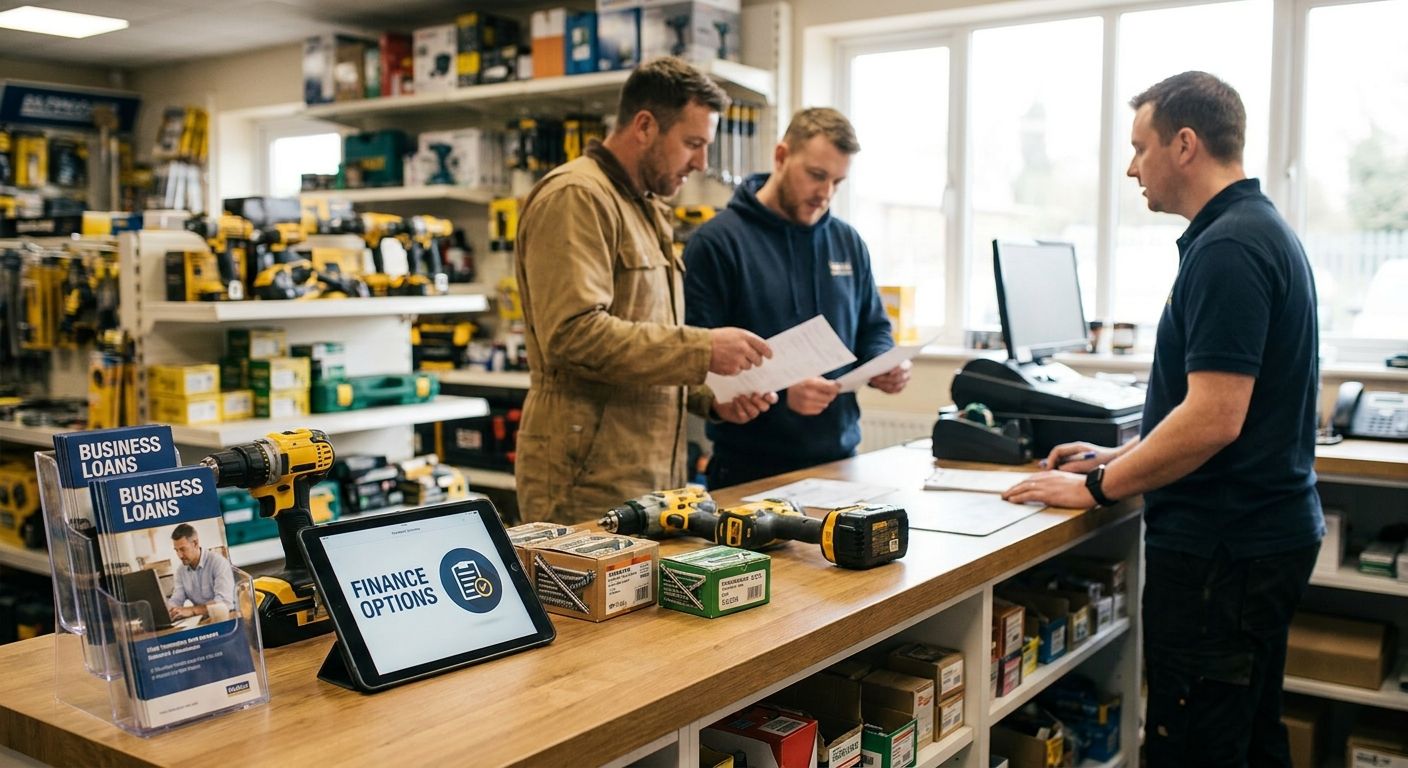
A trade counter that only takes cash, card or a 30-day account is turning away every customer who wants a kitchen worktop, a pressure washer or a load of decking boards today but can't clear the invoice in one go. This guide ranks the six main finance options for trade counters and hardware stores in 2026, from interest-free instalment finance at checkout to traditional trade credit, and tells you which one fits which type of sale.
- PayItMonthly's interest-free instalment finance wins for trade counters selling big-ticket tools, kitchens or timber orders.
- 30/60-day trade credit accounts still beat every alternative for regular contractor customers running ongoing jobs.
- Business credit cards work for quick stock top-ups but carry interest the moment the balance rolls over.
- Invoice finance and asset finance solve the merchant's own cash flow, not the customer's purchase.
- The best finance options for trade counters in 2026 split into customer-facing finance and merchant-facing finance – most counters need both.
Why this matters
A trade counter serves two very different buyers in the same day: a contractor with a 60-day account and a homeowner paying out of pocket for a new shed or a set of power tools. One finance option rarely covers both. The instalment payment providers for trade businesses that get this right in 2026 offer trade credit for the account customers and instalment finance for everyone else, rather than forcing a single model on every sale.
Getting the finance mix wrong costs real money. A hardware store that only runs trade accounts pushes retail and DIY customers to a competitor who lets them spread the cost. A store that only offers instalment finance at the till loses the loyalty and repeat spend that comes from a proper trade account relationship.
What makes the best finance option for a trade counter
- Speed of approval – can the customer or business get a decision at the counter or online in minutes
- Whether it triggers a hard credit search – instalment finance and trade accounts behave very differently here
- POS and checkout integration – does it slot into the till or website you already run
- Cost structure – who pays for the finance, the merchant or the customer, and under what terms
- Fit for one-off vs recurring buyers – retail and DIY walk-ins need a different tool than repeat contractor accounts
- Admin overhead – invoicing, chasing late payers and reconciliation all take staff time
Finance options for trade counters at a glance
| Finance option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| PayItMonthly instalment finance | High-ticket trade and retail purchases at the counter | Interest-free monthly instalments for the customer | Not built for ongoing account-based trade relationships |
| Trade credit accounts (30/60-day terms) | Repeat contractor and trade customers | Familiar, no-interest terms if paid on time | Ties up merchant cash flow and needs credit checks |
| Business credit cards | Quick, ad-hoc stock top-ups | Instant access, no paperwork | Interest accrues fast if not cleared monthly |
| Invoice finance | Merchants waiting on large B2B invoices | Frees up cash tied in unpaid invoices | Solves merchant cash flow, not customer affordability |
| Asset finance / equipment leasing | Financing shop fit-out or heavy equipment | Spreads the cost of big capital purchases | Longer approval process, fixed-term commitment |
| Merchant cash advance | Fast cash against future card sales | No fixed monthly repayment amount | Among the most expensive finance routes available |
1. PayItMonthly instalment finance: best for high-ticket counter sales
PayItMonthly lets a trade counter or hardware store offer its customers interest-free monthly instalments at the point of sale, in store or online. For a customer buying a £1,200 mitre saw, a full kitchen worktop order, or a garden building, spreading that cost over several months is often the difference between buying today and walking out to "think about it."
PayItMonthly pros:
- No interest charged to the customer, so the full purchase price stays the same
- Fast approval built into checkout, whether that's the till or the website
- Increases average basket size on big-ticket tools, kitchens, timber and garden buildings
PayItMonthly cons:
- Designed for one-off or occasional purchases, not ongoing account relationships
- Needs POS or checkout integration to set up properly
- Doesn't replace 30/60-day trade terms for regular business-to-business customers
Best for: trade counters and hardware stores converting big-ticket walk-in and online purchases into instalments rather than lost sales.
Verdict: Buy.
See instalment finance at your counter
Let customers spread big purchases into interest-free monthly instalments.
2. Trade credit accounts (30/60-day terms): best for repeat contractors
Trade credit accounts are the default finance option most builders' merchants and hardware stores already run for their regular contractor customers. A tradesperson buys materials against an account and settles the invoice on agreed terms, usually 30 or 60 days, once their own client has paid them.
Trade credit pros:
- Familiar to contractors who expect account terms as standard
- No interest charged if the account is paid within the agreed period
- Builds loyalty and repeat spend from regular trade customers
Trade credit cons:
- Every account needs credit-checking, and late payers need chasing
- Ties up the merchant's own working capital until invoices clear
- Does nothing for the walk-in retail or DIY customer who wants to pay today
Best for: hardware stores and builders' merchants with an established base of repeat trade customers.
Verdict: Buy – keep this running alongside instalment finance rather than instead of it.
3. Business credit cards: best for quick stock top-ups
A business credit card is the fastest way for a trade counter to cover an unexpected supplier order or restock a fast-moving line, without applying for a formal facility.
Business credit card pros:
- Instant access to funds, usually with no extra paperwork
- Works for both online supplier accounts and in-person purchases
- Useful as a backup when a trade account is temporarily maxed out
Business credit card cons:
- Interest builds quickly once the balance isn't cleared each month
- Credit limits are typically lower than a dedicated trade facility
- Offers zero finance to the end customer – it's a merchant-side tool only
Best for: covering short-notice supplier costs, not customer-facing sales.
Verdict: Hold – useful as a backup, not a primary finance option for the counter.
4. Invoice finance: best for cash tied up in B2B orders
Invoice finance releases cash against unpaid invoices from larger trade or contract customers, rather than waiting the full 30 or 60 days for payment to land.
Invoice finance pros:
- Frees up working capital tied up in outstanding B2B invoices
- Scales with turnover as the trade side of the business grows
- Doesn't require giving up any equity in the business
Invoice finance cons:
- Fees reduce the value the merchant actually receives from each invoice
- Solves the merchant's cash flow problem, not the customer's affordability problem
- Best suited to trade counters with large account customers, not retail-heavy stores
Best for: builders' merchants and trade counters carrying a lot of outstanding B2B invoices.
Verdict: Hold – situational, not a fit for every hardware store.
5. Asset finance / equipment leasing: best for fit-out and heavy equipment
Asset finance spreads the cost of forklifts, racking, POS hardware or a full shop refit over a fixed term instead of paying upfront.
Asset finance pros:
- Spreads the cost of shop fit-out or heavy equipment over time
- Preserves working capital that would otherwise go into a single purchase
- Some agreements bundle in maintenance
Asset finance cons:
- Approval usually takes longer than instalment finance at checkout
- Locks the business into a fixed term regardless of trading conditions
- Doesn't touch the customer-facing side of the counter at all
Best for: hardware stores fitting out a new counter, warehouse or delivery fleet.
Verdict: Wait – only when there's a genuine capital purchase on the table.
6. Merchant cash advance: best avoided unless nothing else fits
A merchant cash advance provides a lump sum against future card sales, repaid as a percentage of daily takings.
Merchant cash advance pros:
- Fast access to cash, often within days
- No fixed monthly repayment – it scales with turnover
Merchant cash advance cons:
- Among the most expensive forms of business finance available
- Daily repayment deductions can squeeze cash flow during quiet weeks
- Does nothing to help convert sales at the counter
Best for: a genuine last resort when other trade finance isn't available.
Verdict: Skip unless every other option above has been ruled out.
How this list was ranked
Each option was weighed against the same six criteria: approval speed, credit-search impact, checkout integration, cost structure, fit for one-off versus recurring buyers, and admin overhead. PayItMonthly and trade credit both score well because they solve different problems for different customers rather than competing head-to-head. Business credit cards, invoice finance and asset finance all score lower on customer-facing sales because none of them touch the point where a purchase decision actually happens.
Which finance option should you choose?
For a trade counter or hardware store weighing up finance in 2026, the decision usually comes down to who's buying and why:
- High-ticket retail or trade walk-in sale – instalment finance
- Repeat contractor account customer – trade credit terms
- Unexpected supplier order – business credit card
- Cash tied up in large B2B invoices – invoice finance
- Shop fit-out or heavy equipment purchase – asset finance
- No other option available – merchant cash advance, as a last resort
Most hardware stores don't need to pick one winner. The stores getting this right in 2026 run instalment finance and trade credit side by side, covering both the walk-in customer and the account holder from the same counter. Staff still need training to offer the right option to the right customer, which is covered in how to train sales staff to offer finance options in store.
“A hardware store that only runs 30-day trade terms is turning away every customer who wants to buy today and pay in instalments.”
FAQ
What's the best finance option for a trade counter in 2026?
Interest-free instalment finance from a provider like PayItMonthly is the strongest option for high-ticket walk-in and online purchases, while 30/60-day trade credit accounts remain the best fit for repeat contractor customers. Most counters need both.
Is interest-free instalment finance available for trade counters and hardware stores?
Yes, instalment finance platforms integrate at the till or website checkout so trade counters and hardware stores can offer customers interest-free monthly payments on big-ticket purchases.
Can a hardware store offer both trade credit accounts and instalment finance?
Yes, and running both is common practice in 2026: trade credit covers regular account customers, while instalment finance covers one-off retail and DIY purchases at the same counter.
Does offering instalment finance at checkout affect the customer's credit score?
That depends on the provider's application process, so check the specific terms before assuming a soft or hard search applies. Trade credit accounts, by contrast, always involve a formal credit check when the account is set up.
How does trade credit compare to instalment finance on cost?
Trade credit is interest-free if the invoice is paid within the agreed 30 or 60-day term, and instalment finance is interest-free to the customer by design. The real difference is who the finance is for: trade credit serves the business buyer, instalment finance serves the end customer.
What's the fastest finance option to set up for a trade counter?
Business credit cards and instalment finance both offer near-instant approval. Trade credit accounts and asset finance take longer because they involve formal credit checks or leasing agreements.
Should a hardware store use a business credit card instead of trade credit?
No, they solve different problems. A business credit card covers the merchant's own short-notice stock purchases, while trade credit finances the store's contractor customers.
Is a merchant cash advance a good option for a seasonal hardware store?
It's usually a last resort. Merchant cash advance is one of the more expensive finance routes and daily repayment deductions can strain cash flow during a store's quieter months.
One last thing
The trade counters winning the most repeat business in 2026 aren't the ones that picked a single finance option and stuck with it. They're the ones running trade credit for account customers and instalment finance for everyone else, side by side, so no customer at the counter ever hears "we don't have a way to help with that."


