
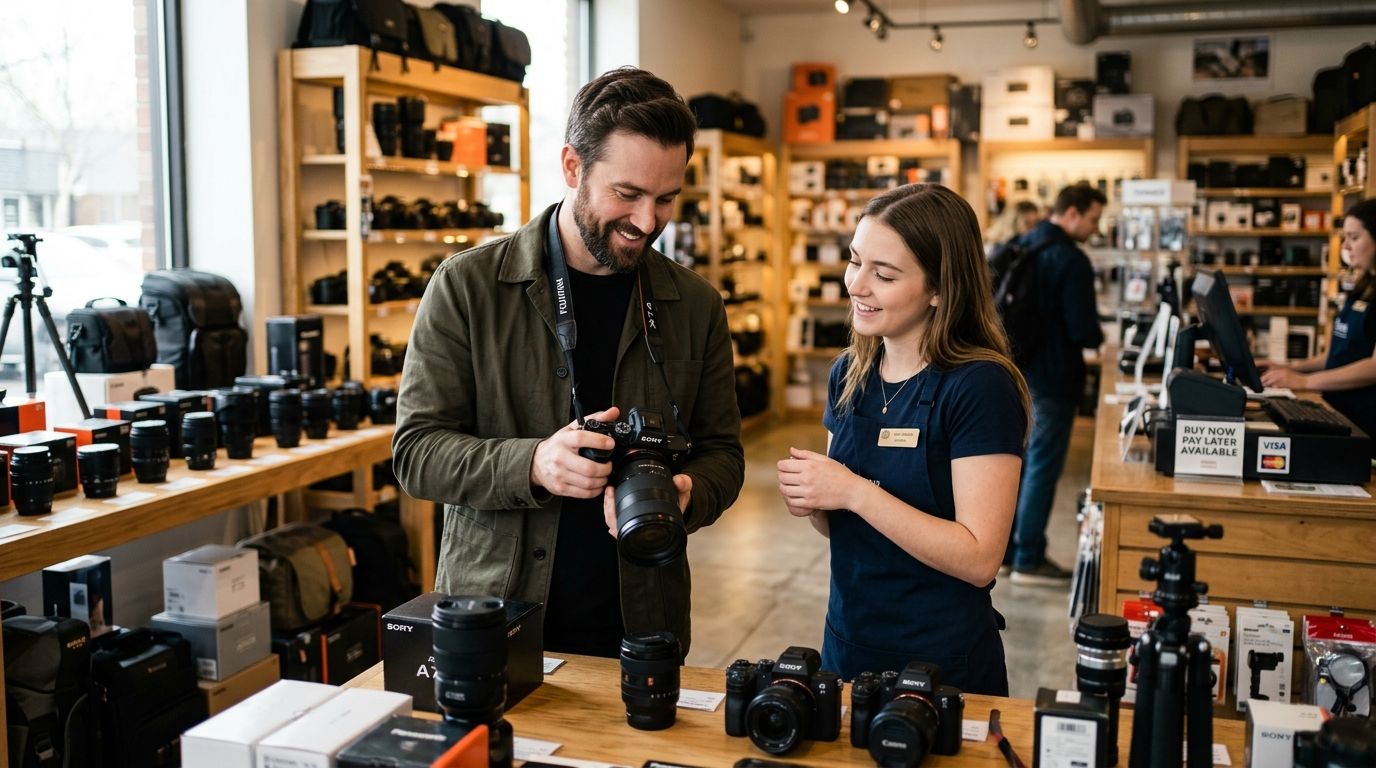
Camera equipment retailers selling bodies, lenses and lighting kits lose sales the moment a customer sees the total at checkout, not because the gear is overpriced but because paying for it in one go is a shock most amateur and semi-pro buyers aren't ready for. Buy now pay later camera equipment finance splits that total into interest-free monthly instalments, so a customer choosing between a mirrorless body and a smartphone upgrade sees a monthly figure instead of a four-digit bill. That single change in how the price is presented is what moves considered purchases from "I'll think about it" to "add to basket" in 2026.
Camera buyers behave differently to most retail shoppers. They research for weeks, compare specs across forums and YouTube reviews, and often buy a body and two or three lenses across a single visit rather than one item. That means the basket value is higher than almost any other consumer electronics category, and the decision point is longer — which is exactly where instalment finance earns its keep.
- Buy now pay later camera equipment finance turns high-ticket bodies and lens kits into a monthly figure at checkout, lifting basket size without discounting.
- PayItMonthly offers UK camera retailers interest-free instalment finance built for considered, multi-item purchases in 2026.
- Comparison shoppers respond to monthly pricing on product pages, not just at checkout — that's where conversion is won or lost.
- Vetting and margin protection matter more in camera retail than in low-ticket categories because average order values run high.
Why buy now pay later matters for camera retailers
A camera shop's average basket is rarely a single item. A buyer who comes in for a body frequently leaves with a kit lens, a spare battery and a bag, and that combined total is where sticker shock kills the sale. Splitting that total into instalments doesn't change what the customer pays overall on an interest-free plan — it changes when they feel the cost, and for a considered-purchase category like photography gear, timing is everything.
The segment also skews toward hobbyists upgrading gradually and small business owners (wedding photographers, content creators, studio operators) buying gear as a business expense. Both groups research heavily before buying, which means the monthly price needs to be visible early — on the product page, not just buried in the checkout flow. PayItMonthly positions instalment pricing as part of the product story for exactly this reason.
Camera retail also runs on seasonal spikes: Christmas, back-to-school for content creators, and pre-wedding-season buying in spring. Instalment finance smooths demand across these peaks because customers who'd otherwise wait for a sale can commit now at a monthly price they've already budgeted for.
Update your product pages first
Most camera retailers add finance only at checkout. That's too late — comparison shoppers decide on the product page.
- Show the monthly instalment figure next to the full price on every body, lens and lighting kit listing
- Add a short "pay monthly" line to category pages for bodies, lenses and accessories, not just flagship products
- Update product feed data so instalment pricing shows in Google Shopping listings where camera buyers compare across retailers
- Mention interest-free terms in email campaigns for abandoned high-value carts
- Keep the wording consistent across every channel so customers aren't confused between in-store and online offers
Add the option at checkout without adding friction
A slow or clunky finance application at the point of sale undoes everything the product page built. The application needs to feel as fast as entering a card number.
- Offer the finance option as a visible payment method alongside card and PayPal, not hidden in a dropdown
- Keep the customer's application on your checkout page rather than redirecting to an external site where possible
- Show approval status within seconds so the customer doesn't abandon the basket waiting
- Test the flow on mobile specifically — a large share of camera research happens on phones even when the purchase completes on desktop
- Review the checkout integration guide if your current setup adds more than one extra screen to complete
Price your instalment plans to match how camera gear sells
A £250 accessory and a £3,000 professional body don't belong on the same instalment structure. Match the plan length to the price point.
- Offer shorter plans (3 months) for accessories and entry-level lenses under a few hundred pounds
- Offer longer plans (6 to 12 months) for bodies, professional lenses and lighting kits where the total runs into thousands
- Round the advertised monthly figure to a clean number so it reads well in marketing copy and on shelf-edge labels
- Avoid stacking finance offers with existing sale discounts unless the margin math has been checked first
- Keep instalment lengths consistent across your own product range so customers aren't confused switching between categories
Vet customers without slowing down the sale
High-ticket electronics attract a different risk profile than low-ticket retail — both from genuine buyers with thin credit files and from opportunistic fraud attempts on expensive, resellable gear.
- Run eligibility checks that don't leave a hard mark on the customer's credit file for standard applications
- Set sensible limits for first-time customers on your highest-value items (flagship bodies, premium lens kits)
- Flag orders where the delivery address doesn't match the billing address for manual review
- Keep the application short — three or four fields, not a full loan form
- Train staff to explain what's being checked so customers don't feel interrogated over a routine approval
Train staff to lead with the monthly price in-store
In-store sales conversations still decide a large share of camera purchases, especially for buyers wanting to hold a body before committing.
- Have staff quote the monthly instalment figure alongside the full price during every high-ticket conversation
- Train staff to introduce finance before the customer asks, not as a rescue when they hesitate at the till
- Give staff a simple script for explaining that the plan is interest-free, not a hidden-cost loan
- Brief staff on plan lengths so they can match the right term to the item without checking a manual mid-sale
Protect your margin when offering interest-free finance
Offering 0% to the customer doesn't mean the retailer absorbs the cost blindly. Camera gear already runs on thin margins compared to some retail categories, so this step matters more here than in most.
- Model the cost of the finance fee against your actual margin per product line before rolling it out storewide
- Reserve the longest, most attractive plans for higher-margin accessories and bundles rather than thin-margin flagship bodies
- Review the margin protection guide before setting blanket instalment terms across your whole catalogue
- Track conversion lift against the finance fee monthly, not just at launch, since buyer behaviour shifts with new camera releases
Add instalment finance to your camera checkout
See how PayItMonthly fits your existing checkout and product pages.
Comparing finance options for camera and photography retailers
| Option | Best for | Key limitation |
|---|---|---|
| Standard store credit card | Retailers with an existing card partner | Slower approval, often carries interest after a promotional window |
| Generic pay-in-4 apps | Low-ticket accessories under a few hundred pounds | Not built for four-figure bodies and lens kits |
| In-house payment plans | Retailers wanting full control of terms | Retailer carries the credit risk directly |
| PayItMonthly interest-free instalments | UK camera retailers selling high-ticket bodies, lenses and kits | Requires the same eligibility checks as any consumer finance product |
PayItMonthly's interest-free model works for camera retailers because it's built around the same considered-purchase, multi-item basket that defines the category, not a low-ticket impulse-buy split.
Common mistakes camera retailers make with instalment finance
- Hiding the monthly price until checkout. Camera buyers decide on the product page; if the instalment figure only appears at the final step, you've already lost the comparison-shopping customer to a competitor who showed it earlier.
- Using one instalment length for everything. A £150 filter kit and a £4,000 professional body shouldn't share the same plan term — mismatched terms either look unattractive on cheap items or unrealistic on expensive ones.
- Ignoring seasonal demand planning. Christmas and pre-wedding-season spikes are predictable in camera retail; retailers that don't plan instalment capacity around them see approval bottlenecks at the worst possible moment.
- Letting staff treat finance as a last resort. Waiting until a customer hesitates at the till to mention monthly pricing is too late — it should be part of the opening pitch on any item over a few hundred pounds.
- Skipping the margin check. Rolling out 0% finance storewide without checking it against category-specific margins (bodies vs. accessories vs. lighting) erodes profit on your thinnest-margin lines first.
FAQ
Does buy now pay later work for expensive camera bodies and lenses?
Yes — interest-free instalment finance is built for exactly this kind of high-ticket, considered purchase, splitting a four-figure body or lens kit into a monthly figure rather than a single payment.
Is buy now pay later camera equipment finance interest-free?
With PayItMonthly, the customer pays the full price of the item split across monthly instalments with no interest added, provided repayments are made on schedule.
Will offering instalment finance hurt my margin on camera gear?
It can if plan terms aren't matched to product margin — accessories and bundles can usually support longer, more attractive plans than thin-margin flagship bodies.
Does a finance application affect the customer's credit score?
Standard eligibility checks for instalment finance are designed to avoid leaving a hard mark on a customer's credit file for routine applications.
Should camera retailers show monthly pricing on product pages or only at checkout?
Product pages, primarily. Camera buyers research and compare before purchasing, so the monthly figure needs to be visible where they're deciding, not just where they're paying.
Can instalment finance be offered on both in-store and online camera purchases?
Yes, provided the checkout and till systems are both configured for it — the terms and monthly figures should stay consistent across both channels.
What plan lengths suit camera and photography equipment best?
Shorter plans (around 3 months) suit accessories and entry-level lenses, while longer plans (6 to 12 months) suit professional bodies and lighting kits where the total runs into the thousands.
One last thing
The single highest-leverage change most camera retailers can make in 2026 isn't adding finance at checkout — it's moving the monthly price onto the product page itself, since that's where the comparison-shopping buyer actually decides whether your listing beats the one they had open in another tab.


