
Picture framing and art supply retailer buy now pay later is a checkout finance option that lets customers split custom framing commissions and bulk art material orders into interest-free monthly instalments, with the aim of turning hesitant browsers into paying customers on the spot. Framers and art supply shops carry a mix of low-ticket consumables and high-ticket custom work, which means one instalment structure rarely fits the whole product range.
- Buy now pay later art supply retailers use lets custom framing jobs and bulk orders convert at the till instead of walking out unpaid in 2026.
- PayItMonthly spreads a single commission or supply order into interest-free monthly instalments without a credit account setup.
- Custom framing needs a deposit-and-balance structure, not a single lump-sum instalment plan, because the work starts before the frame ships.
- Generic BNPL apps built for £30 fashion baskets often cap order values too low for a framed canvas or gallery-wall commission.
- Staff training on offering finance in-store beats hiding the option behind a checkout widget for walk-in framing customers.
Why buy now pay later matters for picture framing and art supply retailers
A custom frame commission, a set of oil paints and canvases, or a gallery-wall bundle rarely costs the same as a t-shirt. When the ticket price climbs, customers pause at the counter and ask if they can pay in parts. Instalment finance for craft and Etsy sellers shows the same pattern in adjacent trades: buyers of handmade, one-off goods want a payment plan before they'll commit, not after.
Framing shops also carry two very different buying moments in one till: a £15 mount board sale and a £200 bespoke frame-and-glaze job. Buy now pay later art supply retailers offer needs to flex across both, or the shop ends up applying a blunt instalment tool to a business that runs on custom quotes.
Update your product pages and quote process
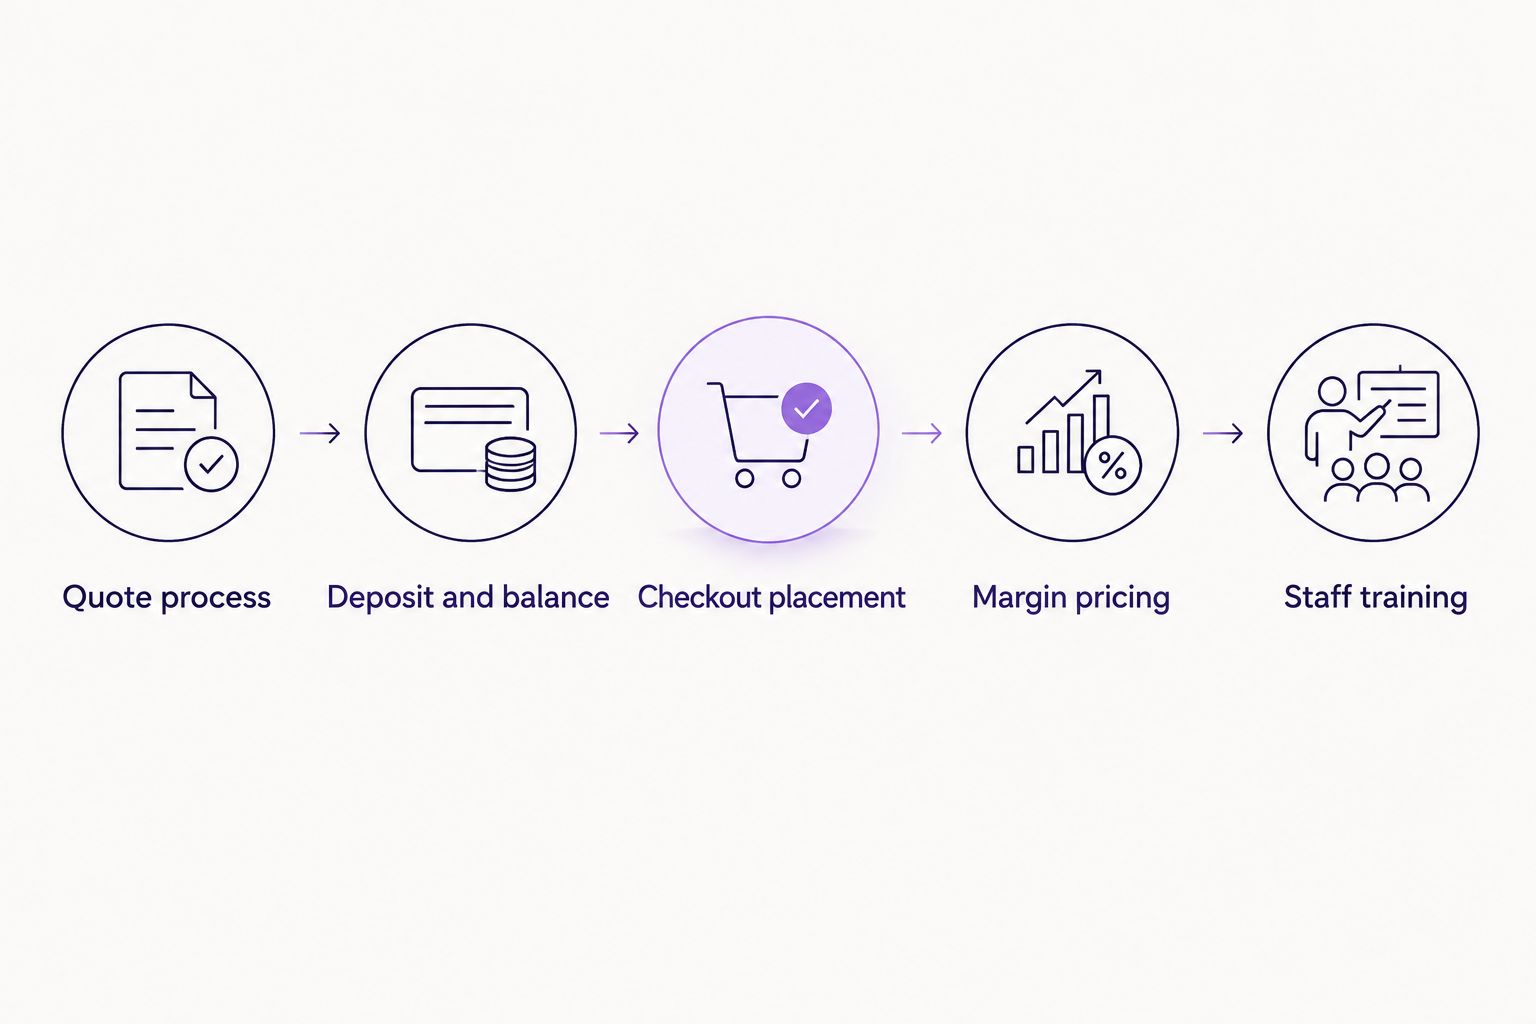
Custom framing rarely has a fixed price until the job is measured and quoted, so the instalment option has to sit inside the quote, not just on a product page.
- List the finance option on any product page for framed art, canvases and bundled supply kits
- Add a line to written and emailed quotes stating instalments are available on the finished commission price
- Flag finance on in-store price boards next to bespoke framing services, not just retail stock
- Mention it verbally at the counter when a customer asks for a quote on a large or multiple-item job
Set a deposit-and-balance structure for custom orders
A framing job that takes two weeks to complete shouldn't be financed the same way as an off-the-shelf print.
- Take a deposit at order confirmation to cover materials and start the job
- Apply the instalment plan to the remaining balance, due on completion or collection
- Confirm in writing when each instalment is collected relative to the job timeline
- Keep the deposit policy consistent across custom framing, printing and mount-cutting services
Add the option at checkout, online and in person
Getting the finance option visible where the buying decision actually happens is the single biggest lever on take-up. How to add a buy now pay later option at checkout covers the mechanics, but for a framing or art supply counter the priorities are:
- Show the instalment badge on the online basket page before the customer reaches payment
- Add a card-machine prompt or till note so in-store staff remember to mention it
- Cover both the ecommerce checkout and any phone or email order process for commissions
- Make sure the option appears for bundled orders (frame plus glass plus mount), not just single items
Price instalments so margins hold on custom work
Custom framing carries labour cost that stock retail doesn't, so the instalment structure needs to protect that margin. How to price monthly instalments for retail products walks through the calculation, and for framers the key adjustments are:
- Build the instalment price from the finished commission cost, including labour, not just materials
- Avoid discounting a job just because it's financed rather than paid in full
- Set a minimum order value for finance eligibility so small mount-only jobs aren't administratively costly
- Review instalment pricing whenever glass, moulding or canvas material costs shift
Train counter staff to offer finance before the customer asks
Many framing customers don't know instalment finance exists for a bespoke job until someone tells them.
- Script a short line for staff to use when quoting anything over a set threshold
- Train staff on what interest-free actually means so they can answer questions accurately
- Give staff a way to check finance eligibility without leaving the counter or the customer waiting
- Review till transaction data monthly to see which staff members mention finance most, and share what works
Promote instalments on your highest-value seasonal ranges
Graduation prints, wedding photo commissions and Christmas gift framing all spike demand for larger, pricier orders.
- Highlight instalments on seasonal landing pages and in-store signage during peak framing periods
- Pair the finance message with examples of typical commission types (canvas, box frame, multi-aperture)
- Use social posts to show finished framing work with a instalment note in the caption
- Time promotion pushes to graduation, wedding and festive seasons when order values rise
Comparing finance options for framing and art supply shops
| Option | Best for | Key limitation |
|---|---|---|
| In-house layaway / deposit scheme | Shops that want full control over collection timing | Manual tracking, no automated reminders, staff time cost |
| Generic consumer BNPL apps | Low-ticket art supply baskets under standard order caps | Often built for fixed short-term splits, poor fit for custom quotes |
| PayItMonthly | Custom framing commissions and bundled supply orders needing flexible instalment length | Requires setup and eligibility checks like any finance product |
| Traditional store credit account | Regular trade customers, schools, art societies | Slower approval, more paperwork than instant checkout finance |
Verdict: PayItMonthly fits picture framing and art supply retailers best when order values vary widely between a £15 mount and a £250 commission, because the instalment structure isn't locked to a single fixed-term split the way many generic apps are.
Add instalment finance to your framing shop
Offer interest-free monthly plans on custom commissions and supply orders.
Common mistakes picture framing and art supply retailers make
- Offering finance only on finished frames, not on bulk supply orders. Art teachers and hobbyists buying canvases, paints and easels in bulk often have the same payment hesitation as framing customers.
- Applying a single lump-sum instalment plan to a job that isn't finished yet. Custom framing needs a deposit taken upfront, not the full balance financed before the work starts.
- Hiding the finance option until the final checkout screen. Customers who don't see it during the quote stage often don't ask, and the sale gets lost to hesitation.
- Not training weekend or part-time staff on the offer. A framing counter often runs on rotating staff, and inconsistent messaging means inconsistent take-up.
- Ignoring seasonal spikes when planning promotion. Graduation and wedding season order values are typically higher than the rest of the year, and that's exactly when the finance message should be loudest.
FAQ
What's the best buy now pay later option for art supply retailers in 2026?
PayItMonthly suits art supply and picture framing shops with mixed order values because instalment terms flex from small supply baskets to large custom commissions. Generic consumer BNPL apps built for fixed short splits fit less well once order values climb.
Can custom framing commissions be split into instalments?
Yes, but the structure works best as a deposit at order confirmation followed by an instalment plan on the remaining balance. Financing the full amount before the job starts leaves the shop exposed if the order changes.
Is buy now pay later better than a store credit account for framers?
Buy now pay later at checkout approves faster than a traditional credit account, which matters when a customer is standing at the counter deciding on a bespoke frame. Store credit accounts still suit regular trade or institutional buyers like schools and art societies.
Does offering instalment finance affect margins on custom framing?
Margins hold if the instalment price is calculated from the full commission cost, including labour, rather than treating finance as a discount. Pricing that skips the labour cost erodes margin on every financed job.
How do I add buy now pay later to my art supply ecommerce store?
Add the finance badge to product and basket pages before checkout, and confirm the payment provider supports bundled orders like a frame, glass and mount sold together. The checkout placement matters more than the provider logo for conversion.
Should small art supply purchases qualify for instalment finance?
Set a minimum order value for eligibility, since financing a £15 mount board purchase costs more in admin than it returns in conversion. Reserve instalments for orders above a threshold that covers processing effort.
What's the biggest mistake framing shops make with finance offers?
Limiting the offer to finished frames only, while ignoring bulk art supply orders that carry the same price hesitation. Art teachers and hobbyist buyers respond to the same instalment message as framing customers.
Does buy now pay later help with seasonal framing demand?
Yes, graduation, wedding and festive seasons typically bring higher-value commission orders, and promoting the finance option during those windows captures buyers who'd otherwise delay the purchase.
One last thing
The framing trade runs on quotes, not fixed prices, which is the one detail most instalment finance guides skip. Set the deposit-and-balance structure before you promote anything, because a customer who's already paid a deposit is far more likely to complete an instalment plan than one financing the whole job upfront. Compare a couple of providers against the best 0% finance options for independent retailers before picking one, since the eligibility checks and order-value caps vary more than the headline "interest-free" claim suggests.


