
118 118 Money serves consumers seeking personal credit, so it belongs on a borrowing shortlist rather than a merchant checkout shortlist. Its consumer-credit role does not answer the separate question of how your shop offers monthly instalments. The best 118 118 Money alternative in 2026 is PayItMonthly if you need merchant-led, interest-free monthly instalments; PayPal Pay in 3 if you want to assess instalments within a PayPal checkout.
- For merchant-focused 118 118 money alternatives, shortlist PayItMonthly for interest-free monthly instalments at retail checkout.
- 118 118 Money addresses personal borrowing; merchant BNPL addresses payment for a particular purchase.
- Assess PayPal Pay in 3 and Klarna against your checkout, customer eligibility and refund workflow.
- Choose retail finance by merchant fit, not by treating consumer lenders as interchangeable checkout providers.
Why this matters
Searching for 118 118 money alternatives brings together two different needs: a consumer looking for credit and a retailer looking to offer customer finance. You need to separate them before comparing providers. Otherwise, you risk choosing a familiar lender without establishing whether it solves your checkout problem.
For a UK merchant, the useful question is: “How can my customers spread a purchase while my business manages the sale properly?” That requires a merchant arrangement, a clear customer application journey and an agreed process for cancellations. A customer independently arranging a personal loan is a different transaction.
This 2026 shortlist focuses on retail checkout, not replacing a customer's existing borrowing. Choose the payment model first, then assess the provider.
118 118 Money alternatives at a glance
The comparison below separates each option's purpose. It is a shortlist for merchant assessment, not a claim that every provider supports your business, sales channel or purchase type.
| Provider | Best for | Standout feature or purpose | Difference from 118 118 Money |
|---|---|---|---|
| 118 118 Money | Consumers assessing personal borrowing | Consumer loans and credit cards | Benchmark for personal credit, rather than merchant-arranged instalments |
| PayItMonthly | UK merchants offering interest-free monthly instalments | BNPL platform for retail purchases | The business offers instalments to its customers |
| PayPal Pay in 3 | Merchants assessing instalments through PayPal | Purchase split into 3 payments | Purchase-linked payment option rather than a separate personal loan |
| Klarna | Merchants assessing a BNPL checkout option | Purchase-linked buy-now-pay-later services | BNPL relationship attached to a retail purchase |
Do not rank these options by brand familiarity alone. Your shortlist should match what you sell, where you sell it and how your team handles the order after checkout. The repayment experience matters, but so does the process when the order changes.
1. PayItMonthly: best for interest-free monthly instalments
PayItMonthly provides UK retailers and merchants of all sizes with a BNPL platform that lets customers spread purchases into interest-free monthly instalments. That makes it a direct fit for the merchant question behind this search. You are assessing a way to offer finance for a sale, not asking customers to source unrelated personal borrowing.
Best for: UK merchants whose requirement is interest-free monthly payments for retail purchases.
Where this option shines
- Its stated purpose matches merchant-led customer finance.
- Monthly instalments give you a clear payment structure to discuss with customers.
- Interest-free repayments match a retail proposition centred on spreading a purchase without interest.
- The platform serves retailers and merchants of all sizes, rather than a stated narrow business-size segment.
Where this option falls short
- Purchase-linked BNPL is not a like-for-like substitute for a customer's general-purpose personal loan.
- The interest-free monthly model alone does not establish whether a particular purchase or customer is eligible.
- Merchant suitability still requires confirmation of your sales channel, settlement arrangements and cancellation process.
Those limits matter. Do not present finance as approved before the customer has completed the required process, and do not infer a checkout integration from the fact that a provider serves retailers.
Head-to-head with 118 118 Money
| Dimension | Merchant BNPL option | 118 118 Money |
|---|---|---|
| Main purpose | Finance offered for a retail purchase | Personal borrowing |
| Business relationship | Platform serving retailers and merchants | Consumer-credit relationship |
| Stated repayment proposition | Interest-free monthly instalments | Depends on the consumer-credit agreement |
| Selection question | Does this arrangement fit your retail sale? | Does this borrowing fit the individual consumer? |
For your 2026 assessment, ask for the merchant terms that govern your actual order journey. Include delivery, cancellation and partial refunds in that discussion. Verdict: Hold until the merchant terms confirm a fit; this is the first option to assess for interest-free monthly retail instalments.
2. PayPal Pay in 3: best for assessing a PayPal-based option
PayPal Pay in 3 is a purchase-linked instalment option that splits an eligible purchase into 3 payments. It belongs on your shortlist when you want to assess customer instalments within a PayPal payment journey. Do not treat the product name as proof that every customer or transaction qualifies.
Best for: Merchants comparing a PayPal-based instalment journey with a separate retail-finance arrangement.
Where PayPal Pay in 3 shines
- It connects the instalment choice to the purchase rather than separate personal borrowing.
- Its 3-payment structure is straightforward to distinguish from a monthly plan with a different schedule.
- It gives you a specific payment journey to review when assessing PayPal for checkout.
Where PayPal Pay in 3 falls short
- A 3-payment structure is not interchangeable with every monthly instalment requirement.
- Customer eligibility remains separate from your decision to accept PayPal.
- You still need to establish how the arrangement fits your sales channel and order changes.
Head-to-head with 118 118 Money
| Dimension | PayPal Pay in 3 | 118 118 Money |
|---|---|---|
| Purpose | Instalments for an eligible purchase | Personal borrowing |
| Payment structure | 3 payments | Governed by the credit agreement |
| Merchant assessment | Review the PayPal checkout and order workflow | Consumer borrowing does not establish a merchant finance arrangement |
In 2026, assess the whole PayPal journey rather than assuming that accepting a wallet payment answers every finance question. Verdict: Hold until the payment schedule and transaction conditions match your checkout requirements.
3. Klarna: best for assessing another BNPL checkout approach
Klarna provides buy-now-pay-later services linked to purchases. It is another relevant merchant shortlist option when you want to compare BNPL checkout approaches rather than consumer lenders. Assess the specific arrangement proposed for your business; the brand name is not the repayment agreement.
Best for: Merchants comparing purchase-linked BNPL providers.
Where Klarna shines
- Its BNPL purpose matches a retail payment decision.
- It provides a relevant category comparison with other purchase-linked finance options.
Where Klarna falls short
- A general BNPL proposition does not establish your business's eligibility or the terms of its arrangement.
- You must review the actual repayment option, customer communications and order-management process.
Keep this assessment focused. Verdict: Hold until the proposed merchant arrangement fits your sales and refund workflow.
Why merchants look beyond 118 118 Money
For merchants, this is often a category change rather than a lender switch. The reason to look elsewhere is not that personal credit is inherently unsuitable for consumers. It is that your business needs a payment arrangement attached to the sale.
Three requirements explain the distinction:
- Checkout ownership: You want a defined payment option in the purchase journey, rather than relying on a customer independently arranging borrowing.
- Customer clarity: You need to explain the purchase and instalment process without confusing it with a general-purpose loan.
- Order administration: You need an agreed route for dealing with cancellations, returns and changes to the financed order.
These are reasons to assess merchant finance. They are not evidence of an outage, a service failure or a change to 118 118 Money's terms.
If your business already has a merchant-finance arrangement, switching is a separate decision. Compare its documented terms with the replacement using this guide to comparing finance providers before switching.
Four checks before choosing a merchant alternative
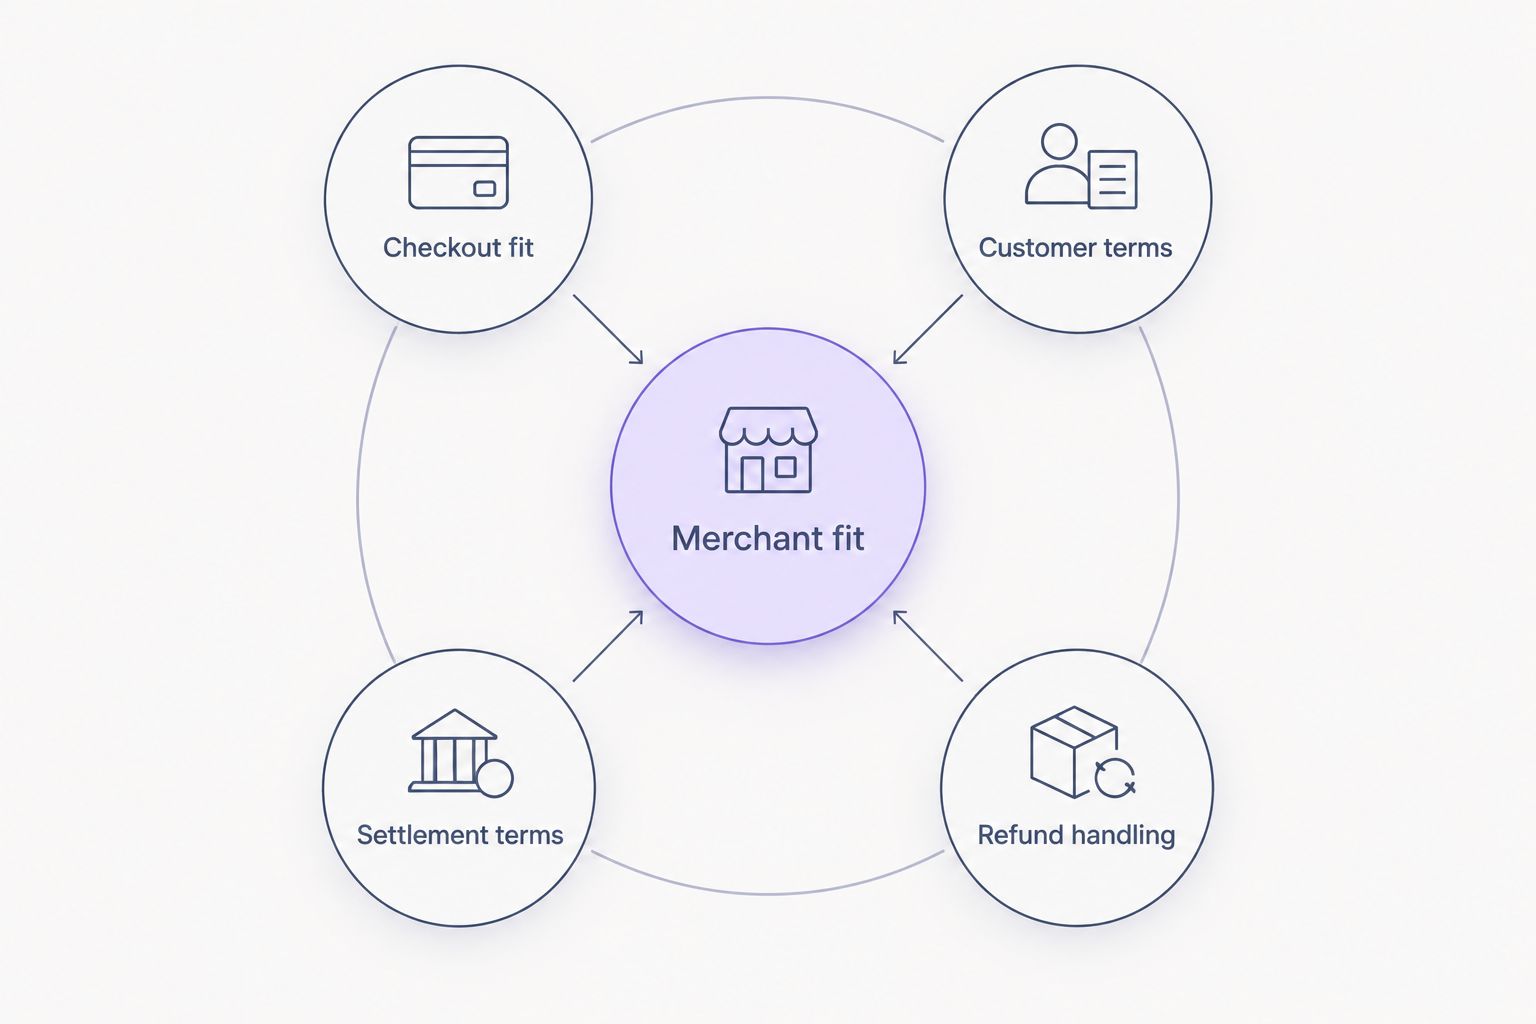
Use these 4 checks for your 2026 shortlist. They turn a provider comparison into a decision about how your business will handle real purchases.
Checkout fit
Write down how you take orders: online, in person, by telephone or through another sales route. Ask each provider to confirm the supported process for your channel. A product that suits an online basket is not automatically the right arrangement for a quoted order or a remote sale.
Check who starts the application and where the customer completes it. Your staff should understand the boundary between explaining the payment option and confirming the outcome.
Customer terms
Review the customer's repayment schedule, eligibility conditions and application information. Use the actual agreement, not a competitor's marketing summary. Interest-free does not mean guaranteed acceptance, and an instalment option does not mean every purchase qualifies.
Your customer-facing explanation should distinguish the purchase total, payment schedule and any conditions. Give customers the information they need before asking them to proceed.
Settlement terms
Ask when settlement occurs and what conditions apply. Then compare those terms with the points at which your business orders stock, delivers goods or starts work. Do not build your cash-flow plan around an assumed payout date.
Establish who handles repayment collection and what your business must do if an order is disputed. Get the responsibilities in writing before training staff.
Refund handling
Review cancellation, full-refund and partial-refund workflows. Find out which actions your team takes and how the customer receives an updated position. A completed checkout is only the start of the order lifecycle.
Check the process for a changed order as carefully as a completed sale. The right provider must fit both the sale and its reversal.
Put the shortlist through three order journeys
Before deciding, walk through 3 order journeys with each shortlisted provider: a completed purchase, a cancelled purchase and a partial refund. Use your own order process. This is a practical assessment exercise, not a claim about any provider's performance.
For the completed purchase, identify what the customer sees, what staff must do and when the order is ready to fulfil. For the cancellation, identify who stops or reverses the finance process. For the partial refund, establish how the order change reaches the payment arrangement.
Record the answers alongside your operational requirements. A provider that describes its process clearly gives your team something concrete to assess; a familiar name alone does not.
Assess monthly instalments for your business
Explore interest-free monthly instalments for UK retail customers.
When staying with 118 118 Money is the right call
118 118 Money belongs in the discussion when the question is personal borrowing, not how your shop offers finance. A consumer comparing loans or credit cards should assess the relevant credit agreement, repayment obligations and suitability for their own circumstances.
Do not recommend moving to merchant BNPL simply because it appears on a retailer's shortlist. Purchase-linked instalments and general-purpose credit serve different purposes. For merchants, choose the checkout arrangement; for consumers, assess the borrowing need.
FAQ
What's the best 118 118 Money alternative for a UK merchant?
PayItMonthly is the first option to assess if your requirement is interest-free monthly instalments for retail customers. Confirm the merchant terms, sales-channel fit and order-management process before deciding.
Is 118 118 Money the same as merchant BNPL?
No: personal borrowing and merchant-arranged BNPL are different payment models. Merchant BNPL attaches instalments to a purchase, while personal credit addresses the consumer's borrowing needs.
Is PayPal Pay in 3 better than a monthly instalment platform?
Neither model is universally better: the right choice depends on the repayment structure your customers need and your merchant workflow. PayPal Pay in 3 splits an eligible purchase into 3 payments; compare that with the actual monthly plan under consideration.
Should I compare Klarna with consumer lenders?
Compare Klarna with merchant BNPL providers when your goal is to offer instalments at checkout. Compare consumer lenders separately when the goal is personal borrowing.
Does interest-free finance mean every customer is accepted?
No: interest-free describes the interest charged, not an acceptance guarantee. Check the provider's eligibility requirements and avoid promising approval before the application outcome.
What should I check before switching customer finance providers?
Check checkout fit, customer terms, settlement terms and refund handling. Walk through a completed purchase, a cancellation and a partial refund before changing your live process.
Can I use this shortlist to replace an existing personal loan?
No: this shortlist addresses merchant checkout finance, not refinancing personal borrowing. Assess an existing loan and any proposed replacement against their own credit agreements and your circumstances.
One last thing
The most useful question in your 2026 provider discussion is not “How easy is the application?” It is “What happens when part of the order is returned?” The answer forces the discussion beyond checkout and into the responsibilities your team will actually manage.
Shortlist PayItMonthly for interest-free merchant BNPL, then assess the complete order lifecycle before choosing.


