
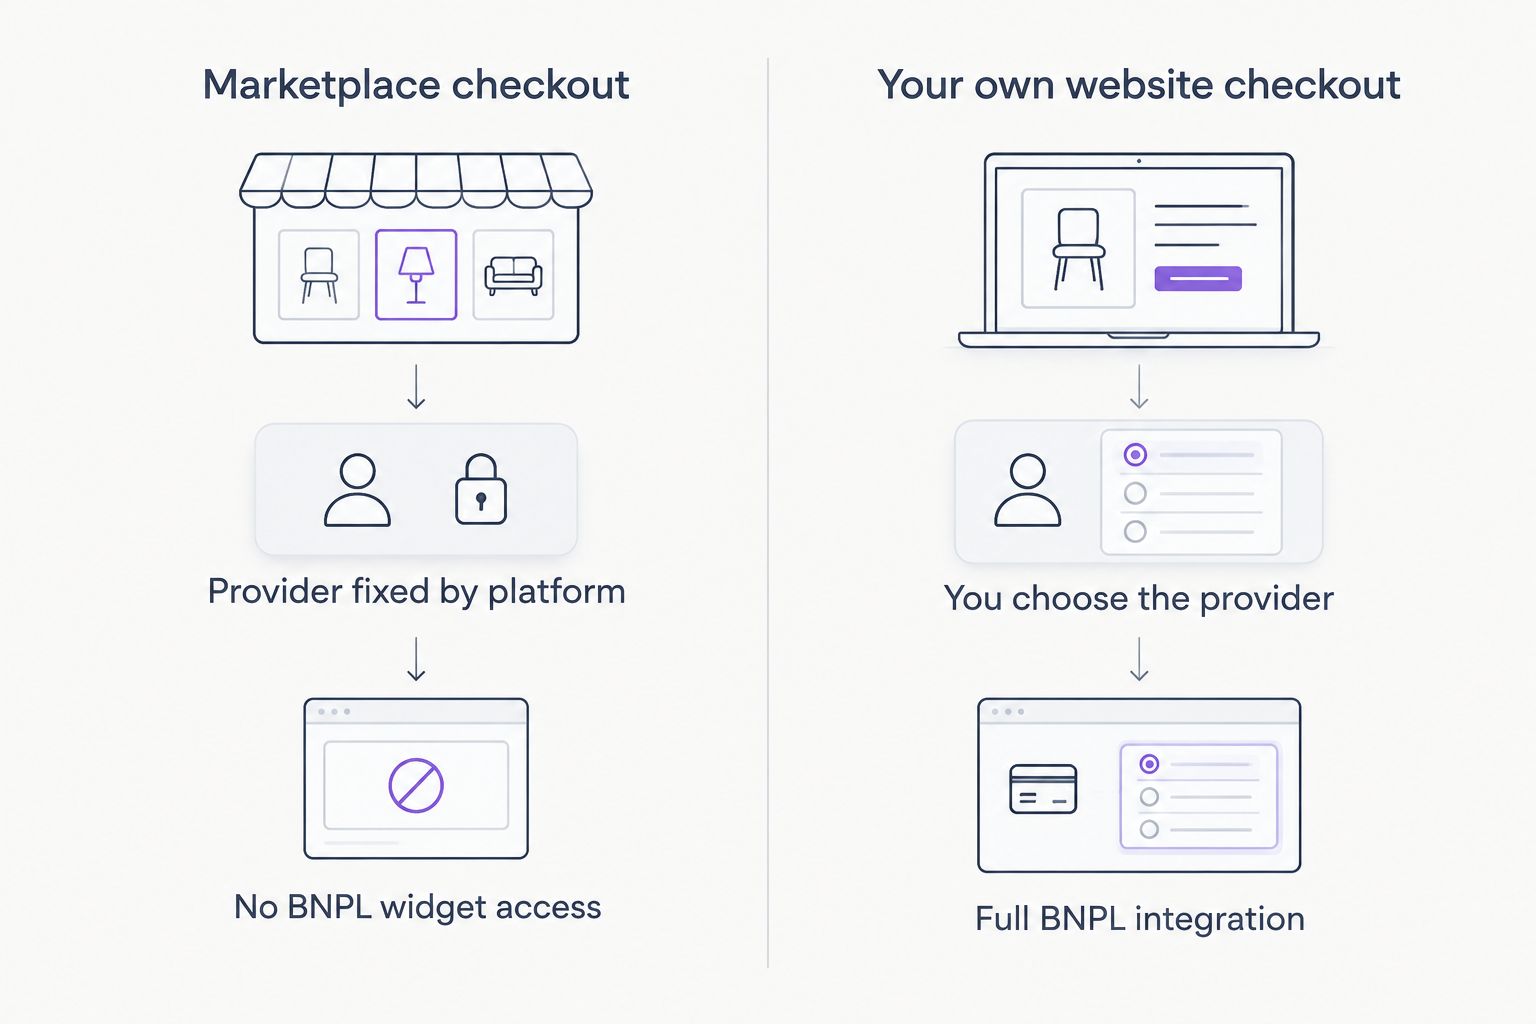
Amazon and eBay lock down their own checkout in 2026, so no outside BNPL provider can sit inside a marketplace basket — every option below works around that constraint instead of inside it.
Best overall for UK sellers with their own web store: PayItMonthly. Best for spending directly on an Amazon or eBay order: Zilch. Best for higher-ticket or custom orders taken off-platform: Payl8r.
- PayItMonthly wins for UK sellers who run a website alongside Amazon and eBay listings and want instalments at their own checkout.
- No BNPL provider, including PayItMonthly, can be embedded inside Amazon or eBay's own checkout in 2026.
- Zilch is the one option a customer can actually spend on a marketplace order, because it works as a virtual card.
- Payl8r suits higher-ticket items where a seller takes the order by enquiry rather than instant checkout.
- Klarna and Clearpay fit sellers who already run a branded storefront next to their marketplace shop.
Why this matters
Searches for "bnpl for amazon and ebay sellers" usually assume a seller can just switch on a BNPL badge the way they would on their own site. They can't. Amazon and eBay control the entire payment flow, and neither platform lets a third-party finance provider add a buy now pay later option at checkout the way a Shopify or WooCommerce store can.
What sellers actually want in 2026 is one of three things: instalments on their own website for the same products they list on Amazon or eBay, a way for marketplace buyers to pay them off-platform for a custom or high-ticket order, or simply an understanding of what happens when a buyer pays with a card-based BNPL product like Zilch. PayItMonthly covers the first two. This guide ranks six providers UK sellers use for exactly that.
What makes the best BNPL for Amazon and eBay sellers
- Works on infrastructure the seller actually controls — a website, an invoice, or a virtual card — not on Amazon or eBay's fixed checkout
- The FCA-regulated credit agreement sits with the provider, not the retailer
- No dependency on marketplace API access sellers don't have
- Settles funds to the seller quickly, regardless of the buyer's repayment schedule
- Handles higher order values, not just small basket top-ups
- Published, comparable merchant fees rather than a "contact sales" black box
Best BNPL for Amazon and eBay sellers: at a glance
| Provider | Best for | Standout feature | Key limitation |
|---|---|---|---|
| PayItMonthly | Sellers with their own web store | Instalments at your own checkout, outside marketplace rules | No presence inside Amazon or eBay's own checkout screen |
| Zilch | Spending directly on a marketplace order | Virtual Mastercard usable anywhere, including Amazon and eBay | Seller has no control over whether a buyer chooses it |
| Klarna | Multichannel brand sellers | Recognised brand across several repayment structures | Same marketplace-checkout wall as every provider here |
| Clearpay | Fashion, beauty and lifestyle sellers | Simple pay-in-4 fortnightly split | Geared to lower order values than furniture or electronics |
| PayPal Pay in 3 | Sellers already settling through PayPal | Runs off a buyer's existing PayPal login | Only works if the buyer already has a PayPal account |
| Payl8r | Higher-ticket and custom orders | Built for larger order values than typical pay-in-4 baskets | Not suited to instant, low-value marketplace purchases |
1. PayItMonthly: best BNPL for sellers building their own checkout outside the marketplace
PayItMonthly puts interest-free instalment finance on a UK retailer's own checkout, giving Amazon and eBay shoppers a reason to buy the same product directly from the seller's site instead. It's built for merchants who want to reduce marketplace fee exposure and own the customer relationship going into 2026.
PayItMonthly pros:
- Interest-free instalments shown at your own checkout, not hidden behind a marketplace rule
- UK-based, built so retailers don't need to hold a credit licence themselves
- Works well as the destination for marketplace shoppers you redirect to your own listing
PayItMonthly cons:
- Cannot appear inside Amazon or eBay's native checkout — own-site only
- Sellers with no website of their own get none of the benefit
- Requires linking your product catalogue to a separate checkout flow
Best for: sellers who already run, or are launching, their own web store alongside Amazon and eBay listings. Verdict: Buy.
Move marketplace shoppers to your own checkout
See how instalment finance works on your own site in 2026.
2. Zilch: best BNPL for spending directly on Amazon and eBay orders
Zilch issues a virtual Mastercard that a UK shopper loads and spends anywhere card payments are accepted, splitting the cost into instalments after the purchase rather than through a merchant's dedicated checkout button. It's the only entry on this list a buyer can actually use on a live Amazon or eBay order.
Zilch pros:
- The only option here a customer can use to pay for a marketplace order directly
- No integration work required from the seller at all
- FCA-authorised in the UK
Zilch cons:
- The seller has zero say in whether a buyer uses it — entirely customer-led
- No merchant dashboard or repayment data for the retailer
- Doesn't help a seller who wants to actively market instalments as a feature
Best for: shoppers spreading an Amazon or eBay purchase themselves, not sellers advertising BNPL. Verdict: Hold — worth knowing about, not something a seller can switch on.
3. Klarna: best BNPL for multichannel brand sellers
Klarna is one of the most recognised BNPL brands in the UK, typically installed on a retailer's own e-commerce site rather than inside a marketplace basket. Sellers running a customer finance platform on a Shopify store alongside their Amazon shop often add it there.
Klarna pros:
- High brand recognition among UK shoppers
- Multiple repayment structures, including pay in 3 and pay in 30 days
- Wide plugin support on major e-commerce platforms
Klarna cons:
- Same marketplace-checkout wall as every provider on this list
- Fees and approval terms sit with Klarna, not published upfront on a merchant's own site
- Adds least value to sellers with marketplace-only volume and no direct site
Best for: sellers running a branded storefront next to their marketplace shop. Verdict: Hold — strong if you already sell direct, redundant if you don't.
4. Clearpay: best BNPL for fashion, beauty and lifestyle sellers
Clearpay splits a purchase into four fortnightly instalments and is used heavily by fashion, beauty and lifestyle retailers on their own checkout pages. It's a lower-ticket product than most of the others on this list.
Clearpay pros:
- Familiar to a younger fashion and lifestyle shopper base
- Simple pay-in-4 structure, easy to explain at checkout
- Established plugin support on major platforms
Clearpay cons:
- Geared to lower order values than furniture, electronics or higher-ticket goods
- Not usable inside Amazon or eBay checkout, same as the rest of this list
- Less suited to sellers whose average order sits above typical fashion baskets
Best for: fashion, beauty and lifestyle sellers running their own site alongside marketplace listings. Verdict: Hold.
5. PayPal Pay in 3: best BNPL for sellers already settling through PayPal
PayPal's own instalment product lets a buyer with a PayPal account split a purchase into three payments. It's most useful for sellers who already run most of their own-site transactions through PayPal.
PayPal Pay in 3 pros:
- No separate merchant account needed if PayPal already handles your payments
- Buyer doesn't apply separately — it runs off an existing PayPal login
- Familiar checkout flow for buyers who already trust PayPal
PayPal Pay in 3 cons:
- Only available to buyers who already have or open a PayPal account
- UK BNPL rules under tightening FCA oversight in 2026 affect how these products are presented
- No presence inside Amazon or eBay's own checkout screen
Best for: sellers whose customers already pay through PayPal on their own site. Verdict: Hold.
6. Payl8r: best BNPL for higher-ticket and custom orders
Payl8r is a UK BNPL provider built around higher-ticket and enquiry-based purchases, better suited to a seller taking an order over email or phone than an instant marketplace basket. It fits sellers converting marketplace browsers into finance options for high-ticket retail purchases on their own site.
Payl8r pros:
- Built for higher order values than typical pay-in-4 fashion baskets
- Works well for converting marketplace browsers into direct, higher-value orders
- UK-focused
Payl8r cons:
- Not designed for instant, low-value marketplace-style purchases
- Still limited to a seller's own site or enquiry process, not inside Amazon or eBay
- Approval can take longer than a one-click marketplace basket
Best for: sellers moving marketplace shoppers into higher-ticket, custom or made-to-order sales. Verdict: Wait — worth it once you have enquiry-based sales volume.
How we ranked these
Each provider was checked against the criteria above: whether it works on infrastructure the seller controls, whether the credit agreement sits with the provider rather than the retailer, and whether it handles the order values sellers actually see coming off Amazon and eBay. Providers that only work on a seller's own site rank on how well they fit alongside a marketplace shop, not on features that don't exist inside marketplace checkout — because none do, in 2026 or otherwise.
Which BNPL should you choose in 2026?
If you're a UK seller who lists on Amazon and eBay but also runs your own website, PayItMonthly is the default choice for putting instalments where you actually control the checkout. If you sell higher-ticket or made-to-order items and take enquiries before a sale, Payl8r fits better. If you're just trying to understand why a buyer's card statement shows four smaller payments for an Amazon order, that's Zilch — and there's nothing to set up on your end.
FAQ
What's the best BNPL for Amazon and eBay sellers in 2026?
No provider integrates inside Amazon or eBay's own checkout in 2026. The best route is running instalments on your own website alongside your marketplace listings, and PayItMonthly is built for that setup.
Can I add Klarna or Clearpay directly to my Amazon listing?
No. Amazon controls its own checkout and doesn't allow third-party BNPL widgets inside it, regardless of provider.
Can eBay sellers accept Pay in 3 or Pay in 4 on marketplace orders?
Only if the buyer pays with a product like Zilch's virtual card. The seller doesn't offer or configure this — it happens on the buyer's side of the payment.
Is Zilch the same as offering BNPL as a seller?
No. Zilch is a buyer-side virtual card, not a merchant integration. A seller offering BNPL means installing a provider like PayItMonthly, Klarna or Clearpay on their own checkout.
How much does BNPL cost a UK retailer in 2026?
Merchant fees vary by provider and are usually charged as a percentage of the transaction. Check current rates directly with each provider before committing.
Do I need an FCA credit licence to offer instalments as a small business?
Usually not. The BNPL provider typically holds the regulated credit agreement, not the retailer, which is why most small sellers can offer instalments without their own licence.
What's the difference between BNPL for marketplace sales and BNPL for my own site?
On a marketplace, the platform controls checkout and no outside provider can be added. On your own site, you choose the provider and control how instalments are presented.
Is BNPL regulated by the FCA in 2026?
Yes. UK BNPL products are under tightening FCA oversight in 2026, which affects affordability checks and how repayment terms are presented to buyers.
One last thing
The oddest answer in this list is Zilch, because it's the only BNPL a customer can genuinely use on a live Amazon or eBay order in 2026 — and it's also the one a seller does nothing to offer. Every other provider, including PayItMonthly, only ever shows up on infrastructure the seller controls. If the goal is building your own instalment offer rather than just understanding what happens on someone else's checkout, the entire decision comes down to whether you have a website to put it on.


