
Ecwid stores don't have a built-in buy now pay later button, so the finance option you bolt on is whichever payment gateway or embedded widget you choose to connect — and in 2026, that choice ranges from UK-only interest-free platforms to global BNPL brands. This guide ranks the five worth considering for an Ecwid customer finance integration and tells you which one fits your catalogue.
- PayItMonthly is the strongest Ecwid customer finance integration for UK-only stores wanting interest-free instalments in 2026.
- Klarna suits Ecwid merchants trading across the UK and EU who need pay-now and pay-later in one widget.
- Clearpay fits fashion, beauty and lifestyle Ecwid stores where a four-payment split matches shopper habits.
- PayPal Pay in 3 is the fastest add-on when PayPal already runs your Ecwid checkout.
- Divido covers higher-ticket Ecwid catalogues that need instalment terms longer than three or four payments.
Why this matters
Ecwid merchants lose sales at checkout when the only options are pay-in-full-now or nothing. PayItMonthly and the other providers on this list exist because splitting a purchase into interest-free monthly payments changes whether a shopper completes the order at all.
The stakes went up in 2026. UK BNPL agreements now fall under FCA consumer credit rules, which means every provider on this list has to show clear affordability checks and pre-contract information before a customer signs up — not just the household names. Picking an Ecwid customer finance integration in 2026 isn't just about conversion rate anymore; it's about which provider actually has its compliance sorted.
An Ecwid store that adds instalment payments is also directly attacking cart abandonment, which is the single biggest leak in most small ecommerce checkouts. If that's your main problem, read the detail on how to reduce cart abandonment with instalment payment options before you pick a provider — it changes which features actually matter to you.
What makes the best Ecwid customer finance integration
- UK regulatory readiness — the provider is prepared for FCA oversight of BNPL from 2026, with clear affordability checks built in
- Checkout integration method — whether it drops in as an embedded widget, a redirect, or via a supported payment gateway
- Credit-check approach — soft search versus no credit check, and how that's explained to the shopper
- Instalment structure — how many payments, and whether the term suits low-ticket or high-ticket items
- Merchant settlement speed — how quickly you're paid once the order is placed
- Fee transparency — whether the cost structure is stated plainly rather than buried in terms
At a glance
| Integration | Best for | Standout feature | Key limitation |
|---|---|---|---|
| PayItMonthly | UK-only independent Ecwid stores | Interest-free monthly instalments built for UK retail checkouts | Not built for merchants trading mainly outside the UK |
| Klarna | Ecwid stores selling across the UK and EU | Pay-now and pay-later sit in one widget | Brand recognition varies by country |
| Clearpay | Fashion, beauty and lifestyle Ecwid stores | Four-payment split matches younger shopper habits | Fixed structure doesn't suit high-ticket items |
| PayPal Pay in 3 | Ecwid merchants already running PayPal as main gateway | Uses an account and checkout customers already trust | Only three instalments, no longer-term option |
| Divido | Higher-ticket Ecwid catalogues (furniture, electronics, home improvement) | Longer instalment terms beyond three or four payments | More setup work than a simple embedded widget |
1. PayItMonthly: best Ecwid customer finance integration for UK-only independent stores
PayItMonthly runs an interest-free instalment platform built specifically for UK retailers, letting shoppers spread a purchase into monthly payments rather than paying the full amount at checkout. It's designed for merchants who sell mainly to UK customers and want a straightforward instalment option without taking on the compliance burden of an FCA credit licence themselves.
PayItMonthly pros:
- Built around UK retail checkouts, not adapted from a US or EU product
- Interest-free instalment structure is simple to explain to shoppers
- Aimed at merchants of all sizes, not just large retailers
PayItMonthly pros (cont.):
- Positioned as a straightforward way to win more customers who'd otherwise abandon at checkout
PayItMonthly cons:
- Focused on the UK market, so it's not the natural fit if most of your Ecwid traffic is international
- Less brand recognition among shoppers than Klarna or PayPal, which can matter at the point of checkout trust
PayItMonthly best for: UK-based Ecwid stores that want an interest-free instalment option without juggling a global BNPL brand's terms.
Verdict: Buy if your Ecwid store sells mainly to UK customers and you want instalments without the compliance overhead.
2. Klarna: best Ecwid customer finance integration for UK and EU catalogues
Klarna combines a pay-now option with pay-later and instalment plans inside one checkout widget, and it's recognised by shoppers across both UK and EU markets. For an Ecwid store selling into multiple countries, that single widget covering several payment behaviours is the main draw.
Klarna pros:
- Wide shopper recognition across UK and EU markets
- Combines pay-now and pay-later options in one flow
- Familiar checkout experience reduces friction for cross-border shoppers
Klarna cons:
- Less differentiated for a UK-only store than a UK-specific provider
- Multiple payment options in one widget can complicate reconciliation for smaller merchants
Klarna best for: Ecwid stores with a genuinely international customer base spanning the UK and EU.
Verdict: Buy if a meaningful share of your Ecwid orders come from outside the UK.
3. Clearpay: best Ecwid customer finance integration for fashion and beauty stores
Clearpay splits a purchase into four interest-free instalments, a structure that's become closely associated with fashion, beauty and lifestyle retail. Shoppers in that bracket are typically familiar with the four-payment pattern already, which lowers the explanation burden at checkout.
Clearpay pros:
- Four-payment structure is widely understood by younger shoppers
- Strong fit for lower average order values typical of fashion and beauty
- Established brand in that retail category
Clearpay cons:
- Fixed four-payment term doesn't flex for higher-ticket items
- Less natural fit outside fashion, beauty and lifestyle categories
Clearpay best for: Ecwid stores selling clothing, cosmetics or accessories to a younger, BNPL-familiar audience.
Verdict: Buy if your Ecwid catalogue is fashion or beauty with a lower average order value. Skip if you sell higher-ticket goods.
4. PayPal Pay in 3: best Ecwid customer finance integration if PayPal is your main gateway
PayPal Pay in 3 splits a purchase into three interest-free monthly payments, run through the same PayPal account a shopper already uses to check out. If your Ecwid store's primary payment gateway is already PayPal, this is the lowest-friction way to add an instalment option.
PayPal Pay in 3 pros:
- No new account creation for shoppers who already trust PayPal
- Sits inside an existing, familiar checkout flow
- Simple three-payment structure is easy to explain
PayPal Pay in 3 cons:
- Only three instalments, with no longer-term option for bigger purchases
- Ties your finance option to your PayPal relationship rather than a standalone provider
PayPal Pay in 3 best for: Ecwid merchants who already run PayPal as their default checkout method.
Verdict: Buy if PayPal already processes most of your Ecwid orders. Hold if you're not on PayPal already — the setup cost isn't worth it just for this feature.
5. Divido: best Ecwid customer finance integration for higher-ticket catalogues
Divido is built for instalment terms longer than the standard three- or four-payment splits, which suits Ecwid stores selling furniture, electronics or other higher-value items where a shopper needs more than six weeks to pay it off.
Divido pros:
- Instalment terms designed for higher average order values
- Fits categories where three or four payments isn't enough runway
- Positioned for merchants selling above typical BNPL basket sizes
Divido cons:
- More setup work than dropping in a simple embedded widget
- Overkill for a store with a low average order value
Divido best for: Ecwid catalogues where the average order sits well above typical fashion or beauty BNPL basket sizes.
Verdict: Buy if your Ecwid store sells big-ticket items. Skip if your average order value is low — a three- or four-payment provider covers it better.
How an Ecwid customer finance integration actually plugs in
Most of these options reach your Ecwid checkout one of two ways: as a supported payment gateway inside Ecwid's own settings, or as a checkout widget that sits alongside your existing card processor. Either way, the mechanics are similar across providers.
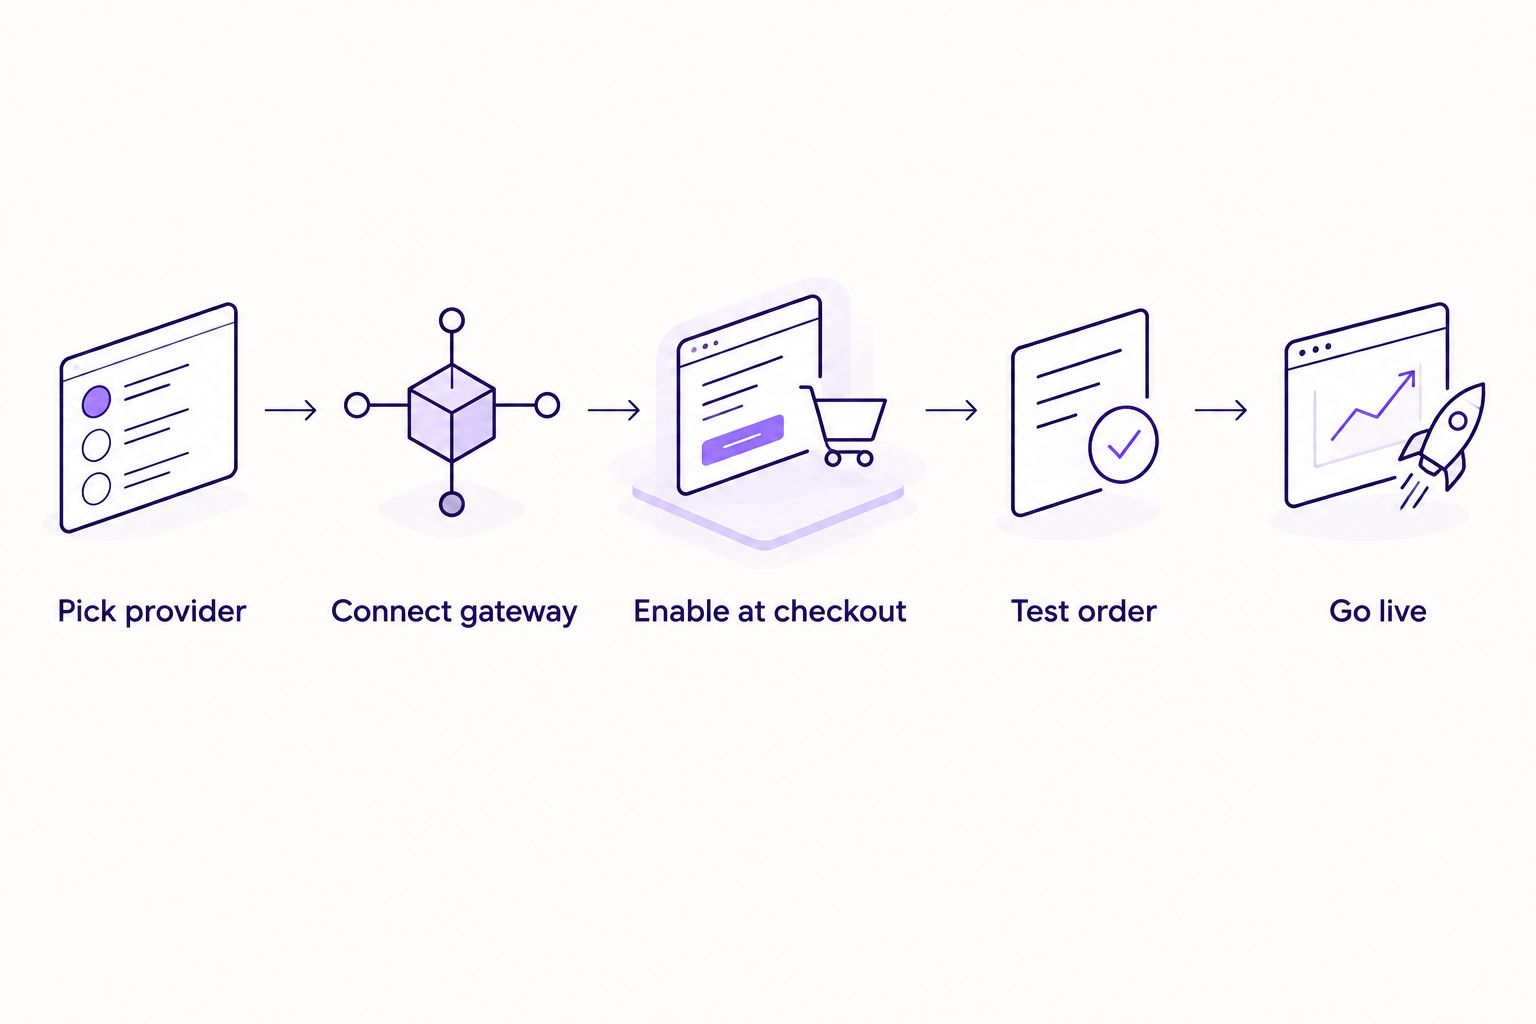
Running a test order before flipping the setting live matters more than most merchants assume — a mismatched instalment structure or a broken redirect at checkout is exactly the kind of thing that turns a finance option into a source of support tickets instead of extra sales. Full detail on that process is in the guide on adding a buy now pay later option at checkout.
How we ranked these
Each provider was assessed against the same six criteria: UK regulatory readiness for 2026, checkout integration method, credit-check approach, instalment structure, settlement speed, and fee transparency. No single provider wins on every criterion — PayItMonthly wins on UK-specific fit, Klarna wins on cross-border reach, and Divido wins on term length for higher-ticket items. That's why this list is a decision tree by use case, not a single leaderboard.
Add interest-free instalments to your store
See how PayItMonthly fits your Ecwid checkout.
Which Ecwid customer finance integration should you choose?
If you're still undecided: default to PayItMonthly if your Ecwid store trades mainly in the UK and you want interest-free instalments without adopting a global BNPL brand's terms. Move to Klarna if a real share of your orders ship into the EU. Pick Clearpay if you're fashion or beauty with a lower average order value, PayPal Pay in 3 if PayPal already runs your checkout, and Divido if your catalogue skews toward higher-ticket goods that need more than four payments to clear.
Don't run more than one instalment provider on the same Ecwid checkout unless you have a clear reason — presenting shoppers with three finance widgets at once adds confusion, not conversions.
FAQ
What is the best Ecwid customer finance integration in 2026?
PayItMonthly is the best fit for UK-only Ecwid stores wanting interest-free instalments in 2026. Klarna suits stores selling across the UK and EU, and Divido suits higher-ticket catalogues needing longer instalment terms.
Does Ecwid support buy now pay later at checkout?
Ecwid supports finance options through supported payment gateways and checkout widgets rather than one built-in BNPL button. Which providers are available depends on your Ecwid plan and existing payment setup.
Is Klarna available for Ecwid stores?
Klarna can be connected to an Ecwid checkout as a payment option, giving shoppers a combined pay-now and pay-later widget. It suits stores with UK and EU customers rather than a UK-only audience.
Can I add PayItMonthly to my Ecwid store?
PayItMonthly is built for UK retailers wanting to offer interest-free monthly instalments at checkout. Check the current setup options directly on the PayItMonthly site for your specific Ecwid configuration.
Do BNPL providers run a credit check on Ecwid customers?
Approaches vary by provider, with some using a soft credit search and others focused on affordability checks rather than a full credit check. From 2026, UK BNPL agreements fall under FCA consumer credit rules requiring clear affordability assessment regardless of method.
Is PayPal Pay in 3 or Clearpay better for an Ecwid store?
PayPal Pay in 3 is the easier add-on if PayPal already runs your Ecwid checkout, since shoppers don't need a new account. Clearpay's four-payment structure fits fashion and beauty catalogues with lower average order values better.
How do I add instalment payments to an Ecwid store?
Instalment payments are typically added by connecting a supported payment gateway or checkout widget inside Ecwid's payment settings, then testing a real order before going live. The exact steps vary by provider.
Is buy now pay later regulated in the UK in 2026?
Yes. UK BNPL agreements fall under FCA consumer credit regulation from 2026, meaning providers must show clear affordability checks and pre-contract information to shoppers.
One last thing
The FCA rules landing in 2026 change more than paperwork — they mean every provider on this list, including the household names, now has to show affordability checks up front rather than burying them in terms. Before you connect anything to your Ecwid checkout, ask the provider directly how they're handling that requirement in 2026. If they can't answer clearly, that's the actual signal to walk away from, not the badge on their widget.


