
Keep Meedsy on your shortlist if its current agreement already meets your checkout and customer-finance needs. Look beyond it when your requirements change, rather than switching for a different logo. For UK retailers comparing meedsy alternatives in 2026, start with PayItMonthly for interest-free monthly instalments, Klarna for consumer BNPL, and PayPal for instalments within the PayPal payment journey.
- Compare meedsy alternatives against your checkout, repayment and refund requirements—not brand recognition alone.
- PayItMonthly provides UK retailers with buy now pay later through interest-free monthly instalments.
- Klarna and PayPal belong on a consumer BNPL shortlist; Novuna Personal Finance belongs on a retail-finance shortlist.
- Stay with Meedsy if your current agreement meets your needs and a replacement offers no clear operational improvement.
Why this matters
Choosing customer finance changes more than the payment button. Your team needs to explain the agreement, reconcile orders and handle cancellations without confusing customers.
PayItMonthly is a BNPL option for UK retailers that want customers to spread purchases into interest-free monthly instalments. Start with that fit, then assess the practical requirements of your business. You can explore PayItMonthly alongside the alternatives below.
For a 2026 shortlist, separate the customer's repayment schedule from your merchant agreement. Interest-free repayments describe the customer's borrowing arrangement; they do not answer who handles disputes, when an order qualifies for settlement or what happens after a partial refund.
Your best alternative is the provider whose written terms and demonstrated workflow match how you sell. A recognisable name is not a substitute for that assessment.
Meedsy alternatives at a glance
This table identifies the purpose of each shortlist entry. It does not rank approval rates, settlement speed or integration quality: those require a like-for-like assessment of the agreement offered to your business.
| Provider | Best for | Standout consideration | Comparison with Meedsy |
|---|---|---|---|
| Meedsy | Keeping an existing arrangement that meets your requirements | Your current agreement and established workflow | Use your actual experience as the benchmark |
| PayItMonthly | UK retailers seeking interest-free monthly instalments | BNPL aimed at UK businesses and their customers | Compare repayment structure and merchant responsibilities |
| Klarna | Retailers assessing consumer BNPL at checkout | Consumer payment and instalment options | Compare the specific UK product and checkout journey |
| PayPal | Retailers assessing instalments within a PayPal payment journey | PayPal Pay in 3 | Compare customer eligibility and payment handling |
| Novuna Personal Finance | Retailers assessing a retail-finance arrangement | Retail finance rather than a payment-button-only comparison | Compare the proposed agreement and application process |
Best for is a shortlist label, not a guarantee of merchant acceptance or customer eligibility. Ask each provider to confirm your business category, sales channels and proposed purchase types before treating it as a replacement.
1. PayItMonthly: best for interest-free monthly instalments
PayItMonthly provides UK businesses, including retailers and merchants of all sizes, with a buy-now-pay-later platform. Customers can spread purchases into interest-free monthly instalments.
That makes PayItMonthly a relevant first candidate when monthly repayment is central to your customer-finance offer. Assess the merchant agreement separately from the customer benefit; the two answer different questions.
Where the platform shines
- Its stated offer matches retailers seeking interest-free monthly instalments.
- It serves UK businesses rather than requiring you to infer merchant suitability from a consumer payment product.
- Its described audience includes retailers and merchants of all sizes.
Where the fit falls short
- Monthly instalments are not the right starting point if your requirement is a different repayment structure.
- The customer proposition alone does not establish compatibility with your checkout or order-management process.
- Interest-free customer repayments do not establish your settlement, refund or dispute responsibilities.
These are practical boundaries to the recommendation. Before changing providers, request a demonstration using an order from your own catalogue and ask for the associated merchant terms.
Best for: UK retailers whose priority is offering interest-free monthly instalments.
| Decision point | This alternative | Meedsy benchmark |
|---|---|---|
| Stated audience | UK businesses, including retailers and merchants | Match against your existing agreement |
| Customer proposition | Interest-free monthly instalments | Compare your current repayment schedule |
| Checkout fit | Assess against your sales channels | Compare the workflow you use today |
| Refund handling | Review the proposed merchant terms | Compare your current cancellation process |
Verdict: Hold on your shortlist; choose only after checkout and contract checks.
2. Klarna: best for a consumer BNPL shortlist
Klarna offers consumer payment options, including instalment products. It belongs in a comparison when your main question is how shoppers will choose and use BNPL during checkout.
Compare the specific product offered to your UK business. Do not treat every Klarna payment option as the same customer agreement.
Where Klarna shines
- Klarna gives you a consumer BNPL option to assess alongside monthly customer finance.
- Its named Pay in 3 product gives you a concrete repayment structure to discuss: 3 payments.
- You can frame the assessment around the actual customer payment journey rather than a broad finance label.
Where Klarna falls short
- A 3-payment product is not interchangeable with every monthly-instalment requirement.
- Consumer product information does not establish the merchant arrangement available to your business.
- Product recognition does not answer how your staff will reconcile refunds or support payment queries.
Best for: Retailers comparing a consumer-facing BNPL checkout option.
| Decision point | Klarna | Meedsy benchmark |
|---|---|---|
| Product selection | Assess the specific UK payment product | Identify the exact agreement you currently use |
| Repayment structure | Pay in 3 is a distinct instalment option | Compare the current customer schedule |
| Customer journey | Review product selection and application | Compare your existing checkout steps |
| Merchant operations | Review refunds and reconciliation | Compare your established process |
For your 2026 assessment, ask for a demonstration of both a completed order and a cancelled order. The cancellation journey tests whether the operational fit extends beyond the initial sale.
Verdict: Hold if consumer BNPL matches your checkout requirements.
3. PayPal: best for a PayPal-centred payment journey
PayPal Pay in 3 lets eligible customers divide eligible purchases into 3 payments. It is a relevant alternative to assess when PayPal is part of the payment experience you want to offer.
Keep the comparison specific. A PayPal payment option and a separate retail-finance agreement do not necessarily solve the same merchant requirement.
Where PayPal shines
- Pay in 3 provides a clearly named instalment option within PayPal's payment journey.
- Its structure gives you a concrete customer schedule to compare with your current offer.
- It is relevant when your payment assessment already includes PayPal.
Where PayPal falls short
- Customer and purchase eligibility mean you must not promise the option to every shopper.
- A 3-payment structure does not meet every requirement for monthly customer finance.
- Your payment implementation still needs an order, refund and reconciliation assessment.
Best for: Retailers evaluating instalments as part of a PayPal payment journey.
| Decision point | PayPal | Meedsy benchmark |
|---|---|---|
| Payment context | PayPal payment journey | Your existing checkout arrangement |
| Instalment option | Pay in 3 for eligible purchases and customers | Your current customer repayment option |
| Customer explanation | Explain eligibility and the chosen agreement | Compare your existing sales explanation |
Verdict: Hold if PayPal fits your intended payment journey.
4. Novuna Personal Finance: best for a retail-finance shortlist
Novuna Personal Finance provides retail finance. Include it when you want to assess a finance arrangement for retail purchases, rather than limiting the search to consumer checkout buttons.
Request a proposal for your actual business model. The name of the provider does not establish which arrangement suits your products or customers.
Where Novuna Personal Finance shines
- Its retail-finance focus makes it relevant to a merchant finance assessment.
- It gives your shortlist a different category of option from a consumer payment journey.
Where Novuna Personal Finance falls short
- A retail-finance arrangement is not automatically the right substitute for a simple payment option.
- You still need to assess the proposed customer application, merchant responsibilities and cancellation process.
Best for: Retailers comparing a retail-finance agreement alongside BNPL.
Verdict: Hold if your requirement extends beyond adding an instalment payment option.
Why people switch from Meedsy
Switch because you have identified a mismatch, not because an alternatives page ranks another provider first. Your existing agreement, customer journey and operational experience are the evidence that matters.
Use these questions to identify a genuine reason to change. They are assessment criteria, not claims about Meedsy's performance.
- Repayment fit: Does the customer schedule match the purchase and the explanation your team gives?
- Checkout fit: Can customers complete the application through the channels where you actually sell?
- Refund handling: Can your team manage full refunds, partial refunds and cancellations without an unclear handoff?
- Settlement terms: Do you understand the conditions attached to merchant payment?
- Support ownership: Is it clear who handles order questions and who handles repayment questions?
A documented failure against one of your essential requirements creates a reason to assess alternatives. A preference for another provider's branding does not.
Do not assume switching will increase completed sales. Establish a baseline using your own checkout and application records, then compare the replacement against the same measures.
How to compare providers before switching
Build your 2026 assessment around the same sales scenarios for every provider. This prevents an attractive demonstration from concealing a poor fit with your actual order process.
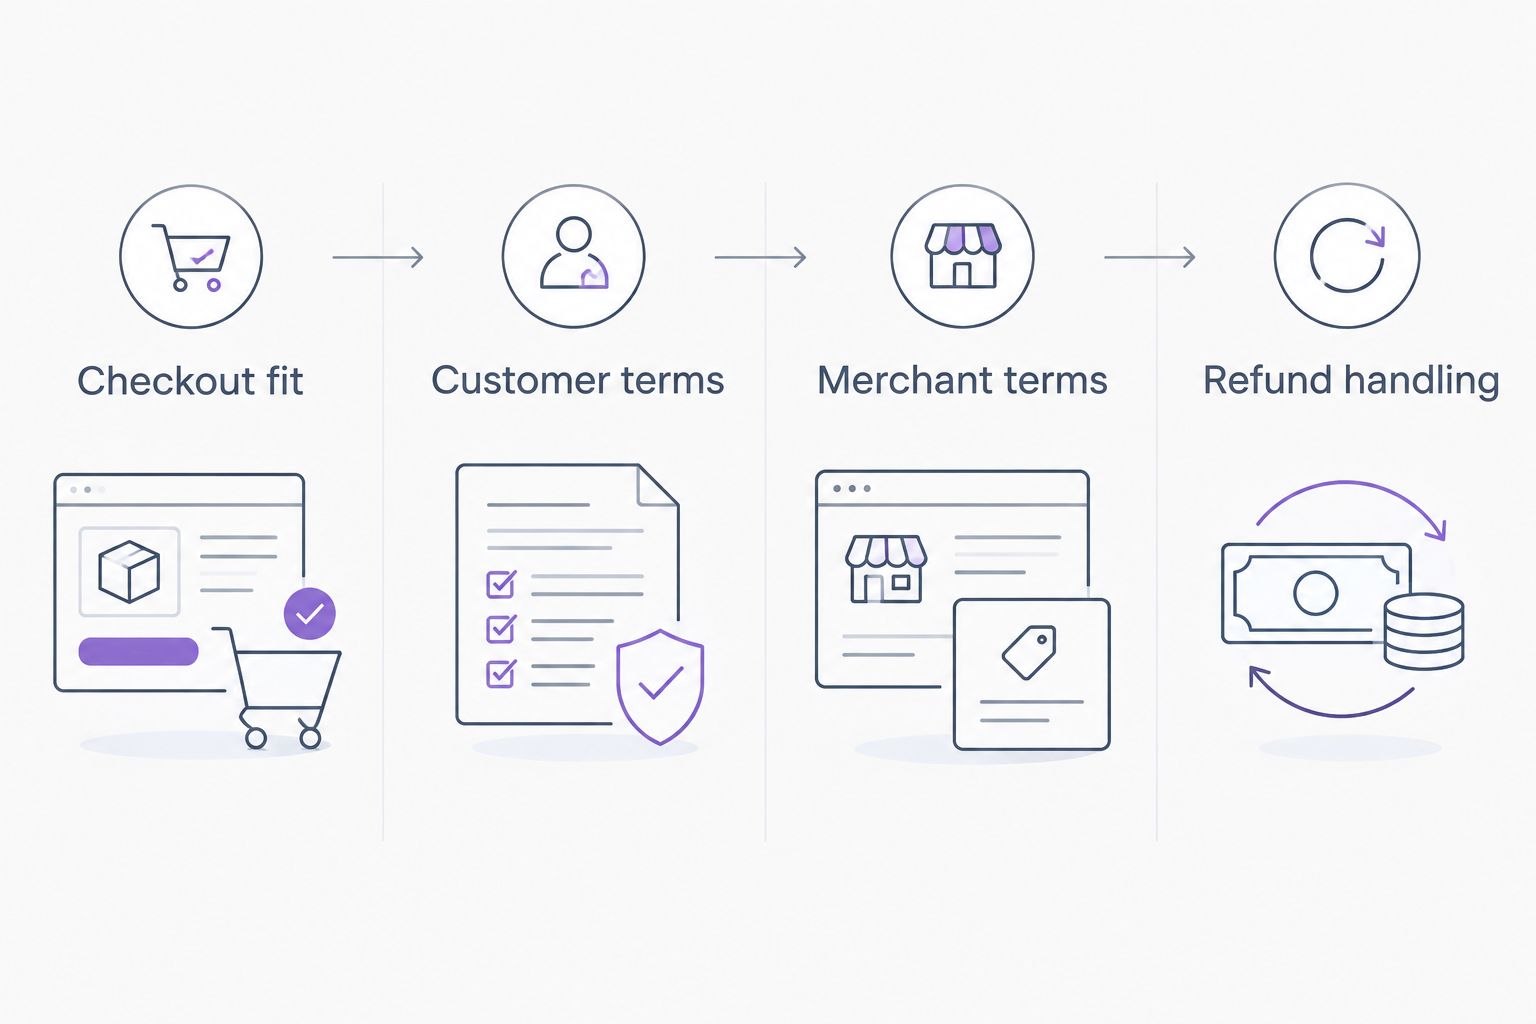
Checkout fit
Show the provider how you sell today. Include your online checkout, in-store process or remote-sales process where relevant, and ask which parts of that journey the proposed arrangement supports.
Require a demonstration. A statement that a provider supports retail does not prove that it supports your particular workflow.
Customer terms
Read the customer agreement and the wording your team will use to explain it. Check repayment dates, eligibility language and what customers are told before they commit.
Do not turn interest-free finance into a claim of guaranteed acceptance or no credit checks. Those are separate assertions and need their own evidence.
Merchant terms
Review settlement conditions, responsibilities and any circumstances that change how an order is handled. Keep the agreement beside your order-management process so your team can identify the operational consequences.
Ask who owns each action. An unclear responsibility becomes a support problem when a real customer needs help.
Refund handling
Walk through a cancellation before fulfilment, a full return and a partial return. Ask how the order record and customer finance agreement are updated in each case.
Check the handoff between your team and the provider. Your customer should receive a consistent explanation, even when separate parties handle the purchase and the finance.
Make the decision against written requirements. Record what each provider demonstrates, what its agreement commits to and which questions remain unresolved before you approve a change.
Explore monthly customer finance
Assess interest-free monthly instalments for your UK retail business.
When staying with Meedsy is the right call
Stay with Meedsy if your current arrangement meets your requirements and another provider offers no demonstrated improvement. Switching itself is not a business outcome.
Keep the same standard for both sides of the comparison. Assess your existing arrangement against the checkout, customer terms, merchant terms and refund requirements used for every alternative.
For a 2026 decision, distinguish an essential requirement from a preference. A provider that meets your essential requirements deserves a place on the shortlist even if another name attracts more attention.
FAQ
What's the best Meedsy alternative for UK retailers in 2026?
PayItMonthly is a relevant first candidate for UK retailers seeking interest-free monthly instalments. Compare Klarna, PayPal and Novuna Personal Finance when their payment or retail-finance models match your requirements.
Is PayItMonthly better than Meedsy?
Choose PayItMonthly over Meedsy only when its proposed arrangement better meets your documented requirements. Compare customer repayment terms, checkout fit, merchant responsibilities and refunds before deciding.
Which Meedsy alternatives offer instalment payments?
PayItMonthly offers interest-free monthly instalments, while Klarna and PayPal offer consumer instalment products. Compare the specific agreement and eligibility conditions rather than treating every instalment option as identical.
Is PayPal Pay in 3 the same as monthly retail finance?
PayPal Pay in 3 is a specific payment option for eligible customers and purchases, not a general label for every monthly retail-finance arrangement. Check whether its repayment structure and payment journey fit your intended offer.
What should I check before switching customer-finance providers?
Check checkout fit, customer terms, merchant terms and refund handling before switching. Ask each provider to demonstrate the same order and cancellation scenarios using your business requirements.
Does interest-free finance mean every customer gets accepted?
No, interest-free finance describes the customer's interest arrangement, not guaranteed acceptance. Explain eligibility separately and use only claims supported by the provider's current terms.
Should I stay with Meedsy instead of switching?
Stay with Meedsy if your current arrangement meets your requirements and a replacement offers no demonstrated improvement. Apply the same assessment criteria to your existing provider and every alternative.
One last thing
Ask to see a partial refund before approving a new finance provider. A successful checkout shows how the arrangement starts; a partial refund shows how your team and the provider handle a changed order.
Use that scenario in your 2026 shortlist review. It forces a practical conversation about responsibilities, customer communication and record updates before you move live transactions.


