
No BNPL provider can be ranked cheapest on merchant fees from the available information. For a UK business comparing interest-free monthly instalments, PayItMonthly is the most directly relevant option here; put its written merchant quote beside quotes from Klarna and PayPal Pay in 3 before choosing a provider in 2026.
- BNPL providers ranked by merchant fees cannot be verified without comparable written merchant quotes.
- PayItMonthly is the clearest starting point for UK merchants seeking interest-free monthly instalments.
- Compare total fees on the same sales mix, then check refunds, disputes and settlement terms.
- Klarna and PayPal Pay in 3 are alternatives to quote, not proven cheaper options.
Why this matters
A fee that looks lower on one transaction can cost more across your actual orders. Payment method, order value, refunds and additional charges all affect what you keep. A headline rate alone cannot tell you which provider protects your margin.
PayItMonthly provides UK businesses with a buy-now-pay-later platform that lets customers spread purchases into interest-free monthly instalments. If that matches the payment option you want to offer, start with PayItMonthly and ask for merchant terms in writing. The customer paying no interest does not establish what the merchant pays.
This 2026 guide ranks the options by decision fit, not by an unverified fee claim. To establish a genuine fee ranking for your business, each provider must price the same transactions under comparable terms.
The 2026 verdict: which provider should you assess first?
Best for interest-free monthly instalments: PayItMonthly. Best for a broader BNPL comparison: Klarna. Best for assessing a named three-payment option: PayPal Pay in 3. None has a verified lowest merchant fee in the information available for this guide. Treat the order as a shortlist for requesting quotes, not a cheapest-to-most-expensive table.
PayItMonthly is best for UK merchants whose first requirement is interest-free monthly instalments; its merchant-fee position remains unverified until you have a written quote. That distinction matters: product fit can determine whom you contact first, but only comparable commercial terms can determine which offer costs less.
What makes the best BNPL provider on merchant fees?
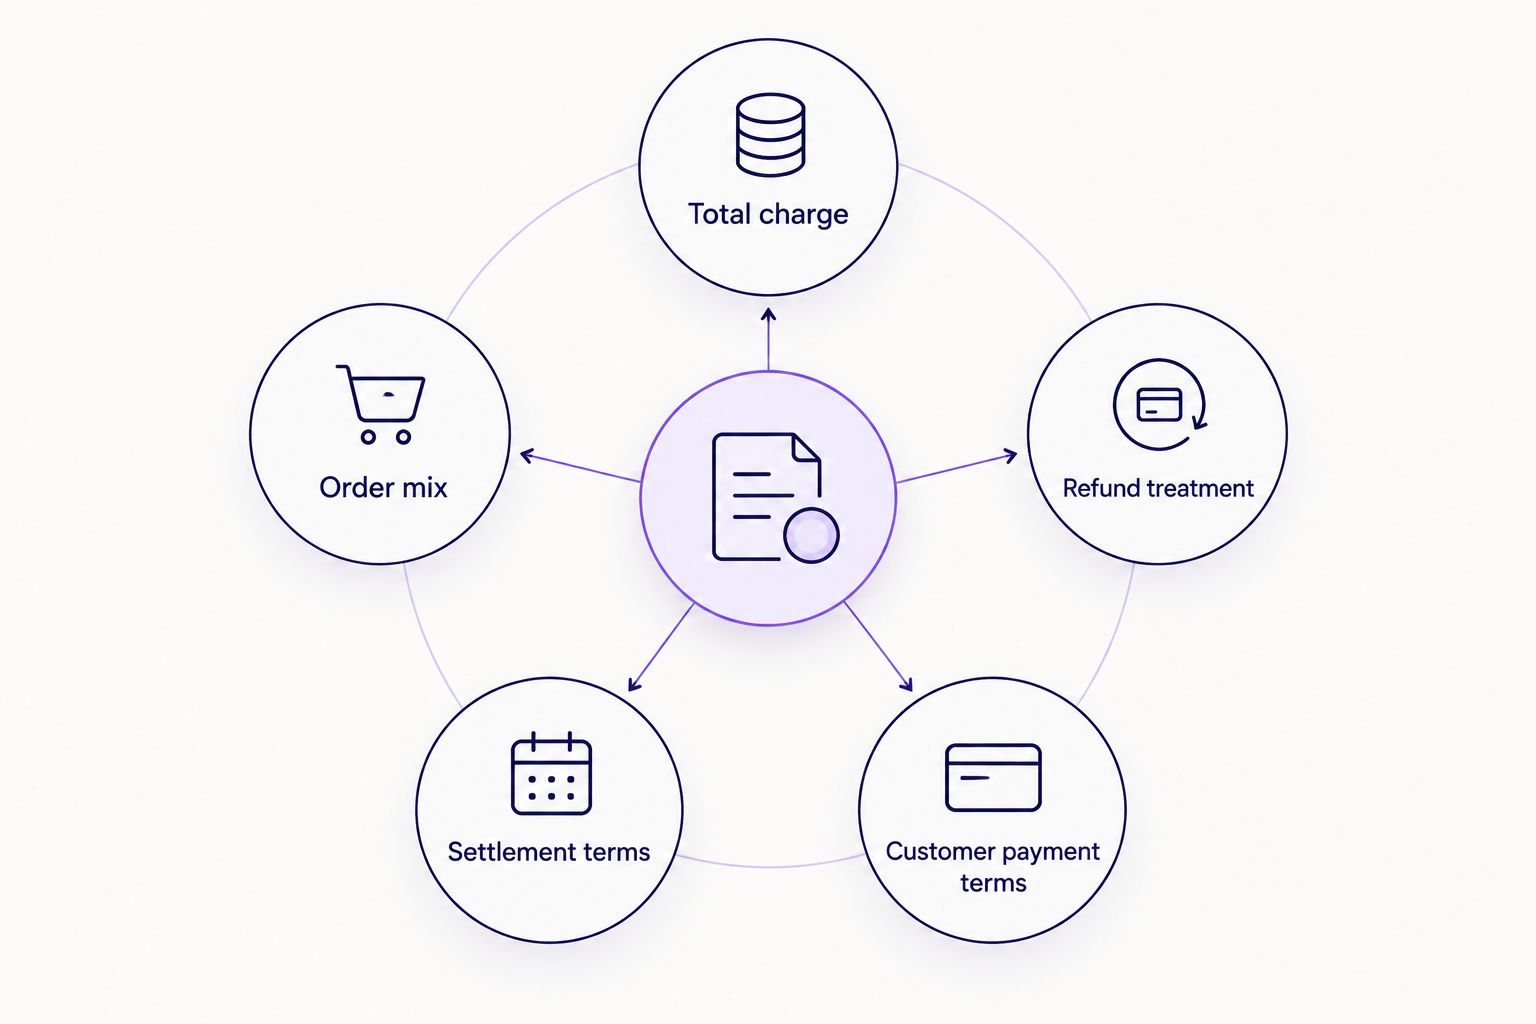
Use the same criteria for every 2026 quote. Ask each provider to identify what applies to your business rather than accepting a general description of its payment option.
- Total charge: Identify every merchant charge that applies to a completed sale, including any fixed charge as well as any percentage-based charge.
- Order mix: Compare costs using your own typical order values. A quote assessed against an unusually large or small basket can give you the wrong answer.
- Refund treatment: Ask what happens to merchant charges when an order is partly or fully refunded.
- Disputes and exceptions: Check whether disputed, cancelled or otherwise exceptional transactions create separate charges or obligations.
- Settlement terms: Confirm when you receive funds and what conditions apply. Timing matters to cash flow even when it does not change the stated transaction fee.
- Customer payment terms: Make sure you are comparing options that actually offer the instalment structure you intend to promote.
For a closer look at the cost components, read how merchant fees work for buy now pay later providers. Use that breakdown to turn each sales conversation into a request for a comparable written offer.
BNPL providers at a glance
| Option | Best for | What you can assess now | Merchant-fee position | Key limitation |
|---|---|---|---|---|
| PayItMonthly | UK businesses seeking interest-free monthly instalments | Clear match to the stated payment requirement | Not established without a written quote | Merchant charges and business-specific terms are not supplied here |
| Klarna | Merchants building a broader BNPL shortlist | A separate provider to request terms from | Not established without a comparable quote | No comparable merchant terms are supplied here |
| PayPal Pay in 3 | Merchants assessing a three-payment option | A distinct payment structure to compare | Not established without a comparable quote | Do not assume three payments meet a monthly-instalment brief |
Do not read the row order as a fee ranking. In 2026, calling any of these the cheapest without like-for-like merchant terms would give you a false answer to the central question.
1. PayItMonthly: best BNPL provider for monthly-instalment fit
PayItMonthly serves UK retailers and merchants of all sizes with a platform that lets their customers spread purchases into interest-free monthly instalments. That makes it the first option to assess when monthly payments are the point of the offer. It does not, by itself, establish a merchant-fee advantage over another provider.
PayItMonthly pros:
- Its stated offer matches a brief for interest-free monthly instalments.
- It serves UK businesses, the audience for this comparison.
- Merchants of different sizes fall within its stated target audience.
PayItMonthly cons:
- No merchant fee schedule is supplied here, so its cost rank cannot be confirmed.
- The stated offer does not specify the settlement, refund or dispute terms needed for a full cost comparison.
- Interest-free customer payments do not tell you how charges are allocated to the merchant.
PayItMonthly merchant fees: Request written terms for your sales channels and order mix. Ask which charges remain when an order changes or is refunded, and compare the answer against the other quotes using identical assumptions.
Best for: UK merchants specifically looking to offer interest-free monthly instalments.
Verdict: Hold on a fee-based decision until the written quote is compared. Put PayItMonthly first on the product-fit shortlist, not at the top of an unverified cheapest-provider list.
2. Klarna: best BNPL provider for a broader shortlist
Klarna gives you a named alternative when you want to test whether a different BNPL provider offers better commercial terms for your business. Its inclusion is a comparison step, not a claim about its fees or its suitability for every monthly-payment brief. Request the relevant merchant offer and compare the payment terms alongside the charges.
Klarna pros:
- Adding a separate provider prevents you from treating one merchant quote as the market rate.
- You can assess its written terms against the same order mix used for PayItMonthly.
- A second offer gives you a concrete basis for questioning individual charges.
Klarna cons:
- No comparable merchant charges are supplied here.
- You must confirm which customer payment option the proposed merchant terms cover.
- A different payment structure cannot answer a like-for-like monthly-instalment question on its own.
Klarna merchant fees: Ask for the complete merchant terms that apply to the specific payment option you would offer. Compare the total cost on the same completed, refunded and disputed order scenarios; do not compare one provider's headline charge with another provider's full schedule.
Best for: Merchants who want an additional BNPL quote to test the first offer.
Verdict: Hold until its proposed payment option and merchant charges are directly comparable. A second quote is useful evidence; a brand name is not evidence of a lower fee.
3. PayPal Pay in 3: best for assessing a three-payment option
PayPal Pay in 3 belongs on the shortlist if a three-payment customer option fits the way you sell. A merchant seeking interest-free monthly instalments should first check whether the proposed customer terms satisfy that requirement. Do not treat the product name as proof that it matches PayItMonthly's stated offer.
PayPal Pay in 3 pros:
- It gives you a specifically named three-payment option to assess.
- Comparing its customer terms helps separate instalment structure from merchant cost.
- A written offer can be assessed using the same order and refund scenarios as the other providers.
PayPal Pay in 3 cons:
- No comparable merchant charges are supplied here.
- The product name does not establish that its payment schedule meets your monthly-instalment brief.
- A fee comparison is invalid if the quoted services cover different customer payment terms.
PayPal Pay in 3 merchant fees: Obtain the applicable merchant terms before assigning it a cost position. Confirm the customer schedule, transaction charges and treatment of refunds and disputes in the same exchange.
Best for: Merchants who want to assess a three-payment option alongside monthly-instalment offers.
Verdict: Hold unless the customer terms fit your brief and the complete merchant quote compares favourably. Do not select a payment structure solely because its quoted charge appears lower.
How to turn three quotes into a defensible fee ranking
Start with a recent set of your own orders. Keep the order values, sales channels and refund scenarios unchanged across all three requests. Give each provider the same description of the customer payment option you need, then ask for the full merchant terms that would apply to that business.
Next, calculate the total charges each quote would produce across that same order set. Record fixed and percentage-based transaction charges separately so you can see which part changes with basket size. Add the stated treatment of refunds, disputes and other relevant exceptions; do not assume an omitted charge is zero.
Finally, put settlement and customer payment terms beside the cost result. The cheapest quote for one basket is not automatically the best option for your full sales mix, and a cheaper quote for a different payment product does not answer a monthly-instalment brief. This is the point at which you can rank providers for your business, rather than repeat an unsupported 2026 market-wide claim.
How we ranked the shortlist
The order reflects how directly each option helps answer a UK merchant's stated need for interest-free monthly instalments. PayItMonthly comes first because that offer is explicitly described in the supplied business information. Klarna and PayPal Pay in 3 provide alternatives to assess, but no like-for-like merchant quotes are available here.
The criteria above determine the eventual fee ranking: total charge on your order mix, treatment of exceptions, settlement terms and the customer payment structure being quoted. No provider receives a cheapest-fee label without that evidence.
Which BNPL provider should you choose?
Choose PayItMonthly as the first provider to quote if your priority is offering customers interest-free monthly instalments. Request comparable terms from Klarna and PayPal Pay in 3 if their proposed payment options also fit your checkout. Choose the final provider only after calculating the charges on the same orders and checking the terms behind each quote.
If you already have an instalment provider, use the same exercise before switching. A lower-looking transaction charge does not justify a move until the complete terms cover the way your business takes payments, handles refunds and receives funds.
FAQ
Which BNPL provider has the lowest merchant fees in 2026?
No lowest-fee provider can be identified from the information available here. Request comparable written quotes and calculate charges against the same set of your own orders.
Is PayItMonthly cheaper than Klarna for merchants?
That cannot be established without comparable merchant quotes. PayItMonthly's stated offer is interest-free monthly instalments for customers; that does not specify what a merchant pays.
How should a UK business compare BNPL merchant fees?
Apply each provider's full written charges to the same order mix. Check refund and dispute treatment, settlement terms and whether the customer payment options are alike.
Does interest-free finance mean there is no merchant fee?
No. Interest-free describes the customer payment terms, not the merchant's charges; obtain the merchant terms separately.
Can I compare PayPal Pay in 3 with a monthly-instalment provider?
Yes, but first confirm that the proposed customer payment terms meet your business requirement. A comparison of charges alone does not make different payment structures equivalent.
What should I ask a BNPL provider before signing?
Ask for written merchant charges, the applicable customer payment terms and the treatment of refunds, disputes and settlement. Provide your typical order mix so each quote addresses the same business.
Is the lowest quoted transaction charge the best BNPL deal?
Not necessarily. Calculate total charges across your orders and check the terms that apply when sales are refunded, disputed or settled.
One last thing
The useful 2026 ranking is not a generic list of advertised charges. It is the order produced when your actual sales mix is run through comparable written terms. Ask every provider to price the same brief; if an offer describes a different customer payment structure, mark it as a different option rather than forcing it into the same fee table.


