
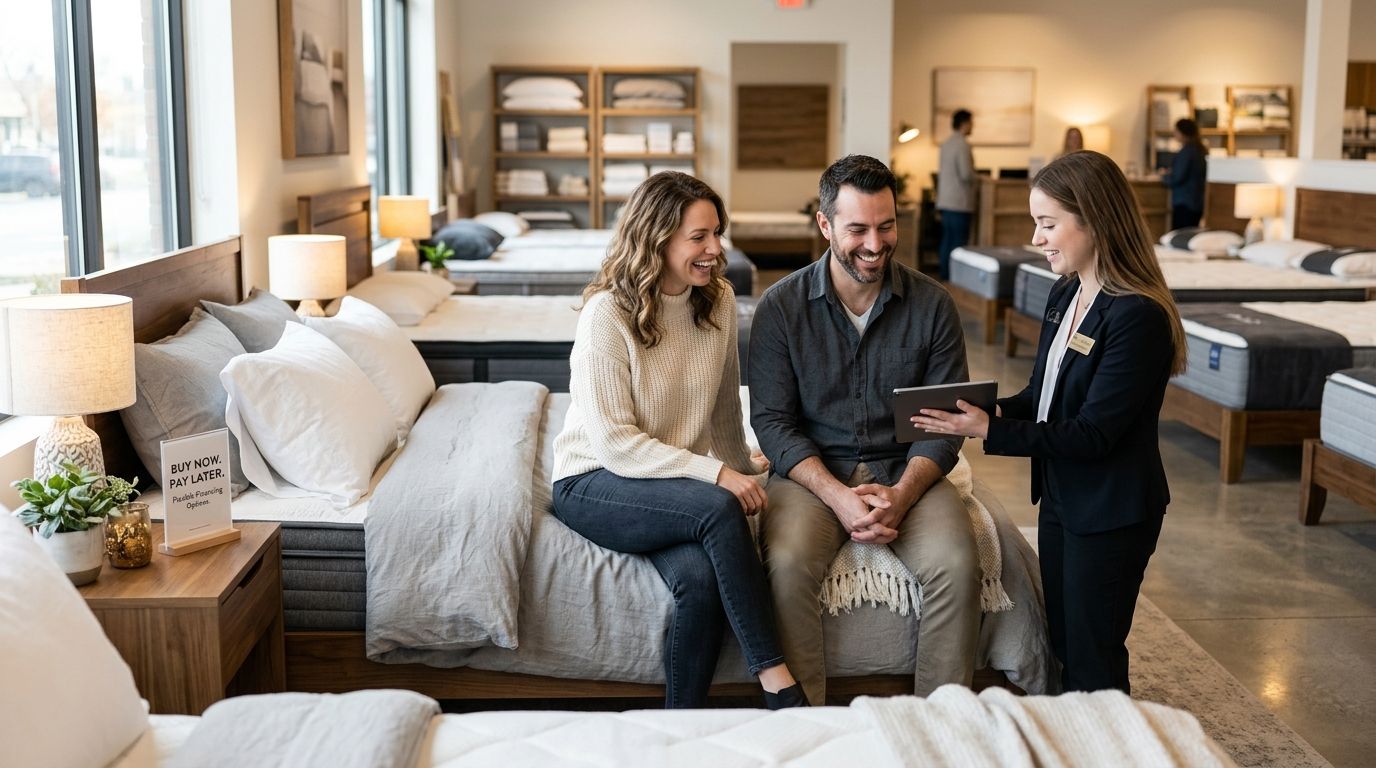
Buy now pay later for mattress and bed retailers is instalment finance that lets shoppers split a bed or mattress purchase into monthly, interest-free payments at checkout, with the aim of raising average order value and stopping big-ticket sleep purchases from getting abandoned at the cart. A mattress is a considered purchase — buyers compare specs, read reviews, and often visit a showroom before committing — and the sector's average order values (frequently £800 to £2,000+ for a bed and mattress set) sit well above what most shoppers want to pay in one card transaction.
- Buy now pay later mattress retailers use it to convert showroom browsers and cut cart abandonment on £800-£2,000+ orders.
- PayItMonthly spreads mattress purchases into interest-free monthly instalments at checkout, in-store or online.
- Sales staff pitching finance before the till, not after, lifts conversion on considered purchases like beds.
- January and Black Friday sales spikes need instalment plans structured in advance, not built on the fly.
Why buy now pay later matters for mattress and bed retailers
Bed and mattress buyers rarely purchase on the first visit. They research online, compare firmness and material specs across three or four retailers, then decide — and price is the single biggest reason a comparison shopper picks one retailer over another. Offering instalment finance at checkout turns a £1,200 mattress and base set into a monthly figure that reads as affordable, which is exactly the psychology that drives conversion on high-ticket, low-frequency purchases.
The mattress trade also runs on seasonal peaks. Boxing Day and January sales, plus Black Friday, generate a disproportionate share of annual bed sales volume, and retailers who can't process finance applications quickly during a rush lose sales to competitors who can. Buy now pay later mattress retailers who prepare their finance offer ahead of these peaks convert more showroom footfall into completed sales in 2026 than those who bolt finance on reactively.
Add instalment finance at the point of sale
Start with the free, manual version before adding software: a printed price ladder showing the monthly cost of your top-selling mattress and bed combinations, displayed next to the till and in-store demo beds.
- Print a simple "from £X a month" card for your three best-selling mattress ranges
- Train till staff to quote the monthly figure before the full price
- Add a finance calculator widget to product pages if you run WooCommerce or Shopify
- Once footfall justifies it, connect a dedicated BNPL platform like PayItMonthly so the monthly quote and the application happen in the same few taps
Price your instalment plans to match mattress order values
A one-size instalment term doesn't work when order values range from a £400 single mattress to a £2,500 super-king bed, mattress and headboard set.
- Map your top 10 SKUs by price and pick a term length that keeps monthly instalments under a psychologically comfortable threshold
- Offer a shorter term for accessories (protectors, pillows) sold alongside the bed
- Avoid stretching low-ticket items (under £300) across long terms — it looks like a hard sell
- Review how to price monthly instalments for retail products before setting your default term across the catalogue
Train sales staff to pitch finance before the till, not at it
Mattress sales are consultative — staff spend 15 to 30 minutes with a customer testing firmness and discussing sleep issues. That's the moment to mention instalments, not after the customer has already mentally committed to a number.
- Script the finance mention into the demo, not the checkout
- Give staff a laminated card with monthly figures for the beds they demo most
- Reward staff for finance-assisted sales in commission structures
- Run a 15-minute refresher session each quarter, especially before Black Friday and January
Vet customers without adding friction to a considered sale
Mattress buyers who've already spent 20 minutes testing beds don't want a clunky finance application killing the moment.
- Use a soft-search eligibility check that doesn't affect credit scores
- Keep the application to a handful of fields — name, address, income band, bed selected
- Set clear internal thresholds for who gets automatic approval versus manual review
- Cap credit limits sensibly against your average bed order value so declines stay rare on realistic purchases
Structure instalment plans around seasonal sales spikes
January and Black Friday can account for a large share of annual bed and mattress revenue, and a finance system that buckles under volume costs sales exactly when demand peaks.
- Test your finance checkout flow for speed a month before your biggest sale window
- Brief seasonal or temporary staff on the finance process, not just the discount codes
- Pre-approve returning customers where your system allows it, to speed up repeat sales
- Have a fallback manual process ready in case of a system outage during peak trading hours
Handle refunds and cancellations correctly
Beds and mattresses come with trial periods more often than most retail categories, which means finance refunds need a clear process before the first return request lands.
- Agree with your finance provider how a full or partial refund adjusts the customer's instalment schedule
- Document the process for staff so nobody improvises on a live call
- Communicate refund timelines to the customer at point of sale, not after they've asked
- Keep a written record of every cancellation for audit purposes
Promote your 0% finance offer without breaking advertising rules
Finance advertising for retail is regulated, and mattress retailers running seasonal promotions need to get the wording right on social media and in-store signage.
- State the finance is subject to status and eligibility
- Never advertise a monthly figure without also showing the total repayable amount
- Keep promotional copy consistent across in-store posters, email, and social ads
- Check current Advertising Standards Authority guidance before launching a new campaign
Add finance to your bed and mattress checkout
See how PayItMonthly fits your till and online store in 2026.
Comparing finance options for mattress and bed retailers
| Option | Best for | Key limitation |
|---|---|---|
| In-house layaway or deposit scheme | Retailers wanting full control, no third party | Manual admin, no credit vetting, cash flow risk if customer defaults |
| Store credit card | High-volume chains with existing card infrastructure | Slow application, often carries interest after a promotional period |
| Dedicated BNPL platform (e.g. PayItMonthly) | Independent and multi-location retailers wanting fast, interest-free checkout finance | Requires integration work and ongoing merchant fees |
| Pay-in-full with a discount incentive | Retailers avoiding finance admin entirely | Loses the customers who genuinely need to spread the cost |
Verdict: for a mattress and bed retailer selling £800-plus orders in 2026, a dedicated BNPL platform outperforms in-house layaway on speed and conversion, but only if sales staff are trained to pitch it during the demo, not at the till.
Common mistakes mattress and bed retailers make
- Quoting the full price before the monthly figure. Once a customer hears "£1,400", the monthly number lands as an afterthought instead of the headline.
- Ignoring accessories in the finance plan. Pillows, protectors and bases sold separately at full price undercut the affordability message of the main purchase.
- Under-resourcing the January sale. Bed retailers see some of their highest annual volume in January, yet many staff finance applications with skeleton cover.
- Skipping refund documentation. Mattress trial periods generate returns; retailers without a written finance-refund process improvise and get it wrong.
- Advertising 0% finance without the required disclosures. Vague social ads risk complaints and rework mid-campaign.
FAQ
Do mattress retailers need a credit check to offer buy now pay later?
Most UK BNPL platforms run a soft eligibility check that doesn't affect the customer's credit score, rather than a full credit check. The retailer sets its own approval thresholds against typical order values.
What's the best buy now pay later option for a small independent bed shop?
A dedicated BNPL platform like PayItMonthly suits independent retailers because it needs no in-house credit team and integrates with existing till and online checkout setups. In-house layaway works only if you can absorb the admin and default risk yourself.
How much does buy now pay later cost a mattress retailer?
Costs vary by provider and are typically charged as a merchant fee on the transaction rather than interest to the customer. Check current terms directly with the provider before signing up.
Can customers get instalment finance on a mattress bought over the phone?
Yes, if the finance provider supports remote or telephone sales, the application can be sent as a link for the customer to complete on their own device. This matters for bed retailers who take a meaningful share of orders by phone.
Is buy now pay later better than a store credit card for beds?
BNPL checkout finance is typically faster to apply for and doesn't require the customer to hold an ongoing credit account, which suits one-off big-ticket purchases like a bed. Store cards suit retailers wanting repeat custom over years, not a single considered purchase.
What happens to instalments if a mattress is returned during a trial period?
The instalment schedule should be adjusted or cancelled in line with the refund, but the exact process depends on the finance provider's terms. Agree this process with your provider before launching finance at checkout.
Does offering 0% finance increase average order value on mattresses?
Splitting a big-ticket price into monthly instalments commonly encourages customers to add accessories like protectors or a premium base, since the incremental monthly cost looks small. Retailers should structure plans so accessories are included in the same instalment, not billed separately at full price.
One last thing
The mattress and bed category has one trait most other retail sectors don't: a built-in trial period on nearly every sale. That means your finance process needs a clean, pre-agreed refund path before you launch, not after the first return call comes in — get that documented in 2026 before your next sale event, not during it.


