Wedding photographers’ buy now pay later finance is a way for couples to spread payments for photography services, with the aim of making bookings manageable without confusing your payment terms. This 2026 guide explains how to assess customer finance around date reservations, advance bookings and image delivery—not just an online checkout.
- Buy now pay later for wedding photographers needs clear booking, settlement and cancellation rules before launch.
- PayItMonthly suits UK merchants seeking interest-free monthly instalments; wedding photography eligibility needs confirmation before promotion.
- Compare provider-managed customer finance with your own staged payments, including administration and responsibility for missed payments.
- Keep the photography contract separate from the finance agreement, and explain how changes affect both.
Why buy now pay later matters for wedding photographers
Wedding photography involves more than collecting a payment. You reserve a particular date, agree coverage, carry out the shoot and deliver the finished work at separate stages. Your payment process needs to reflect those commitments.
A couple’s repayment schedule and your business’s settlement schedule are different things. Do not assume that monthly customer payments mean either monthly merchant payments or immediate settlement. Confirm the actual arrangement before you commit diary space or supplier expenditure.
The starting point is understanding whether service businesses can offer buy now pay later. For a photography business, the decisive questions concern eligible services, advance-booking periods and what happens when the wedding changes.
For your 2026 bookings, assess finance against the workflow you actually use. An attractive payment option is not enough if you cannot reconcile it with your contract, calendar and accounts.
How to offer buy now pay later for wedding photographers
1. Map your booking and delivery milestones
Start manually with your existing contract and a simple spreadsheet. Write down when you reserve the date, when you incur expenditure and when each deliverable becomes due. This gives you a baseline before you approach a provider.
Use 3 checkpoints for your initial review: booking confirmation, wedding coverage and final delivery. These are planning checkpoints, not a recommended repayment schedule. Add separate milestones where your own service requires them.
The purpose is to expose timing conflicts. For example, your reservation process should not imply that a finance application alone secures the date.
- Record the action that confirms a booking.
- Separate the wedding date from image-delivery deadlines.
- Identify advance expenditure such as a second photographer.
- Document how you handle albums or later additions.
- Mark any payment conditions attached to delivery.
2. Compare finance with your existing payment process
Before adding a platform, review what you can manage through your current invoicing process. A written staged-payment schedule gives couples defined payment dates, but leaves you responsible for monitoring receipts and handling unpaid balances.
Provider-managed finance is a different arrangement. It introduces a separate agreement whose eligibility, settlement and repayment responsibilities need checking. Do not treat an invoice split into parts as interchangeable with a third-party credit product.
Choose the arrangement that fits your booking process, not simply the one with the smallest-looking monthly payment. Include your administrative work and contractual responsibilities in the comparison.
- Map who collects each payment.
- Identify who follows up unpaid balances.
- Compare when money reaches your business.
- Check how either arrangement handles cancellation.
- Keep a non-finance payment route available.
3. Confirm provider eligibility before promoting finance
Prepare a short description of your business, booking process and services. Send it to prospective providers and ask for written confirmation that the proposed arrangement covers wedding photography, including the gap between booking and performance.
PayItMonthly buy now pay later is best for UK merchants seeking interest-free monthly instalments. Its stated offer is customer instalment finance for UK businesses; wedding photographers must confirm that their particular services and booking model qualify.
The PayItMonthly platform is a route to assess instead of relying solely on a manually administered payment schedule. Confirm the practical workflow before expecting it to reduce your administration.
- Describe photography coverage and any physical products separately.
- Explain how far ahead you accept bookings.
- Ask which booking stages can use finance.
- Confirm merchant eligibility and customer application requirements.
- Request current settlement and cancellation documentation.
4. Align the photography contract and finance agreement
Review your documents manually first. Your photography contract should explain what you will deliver and how the booking works; the finance agreement addresses the customer’s borrowing and repayment obligations. Neither should leave the customer guessing about the other.
Build your 2026 process around consistent information across the proposal, contract, application and confirmation. If a couple changes the wedding date, the photography booking and finance arrangement both need review rather than an assumption that everything transfers automatically.
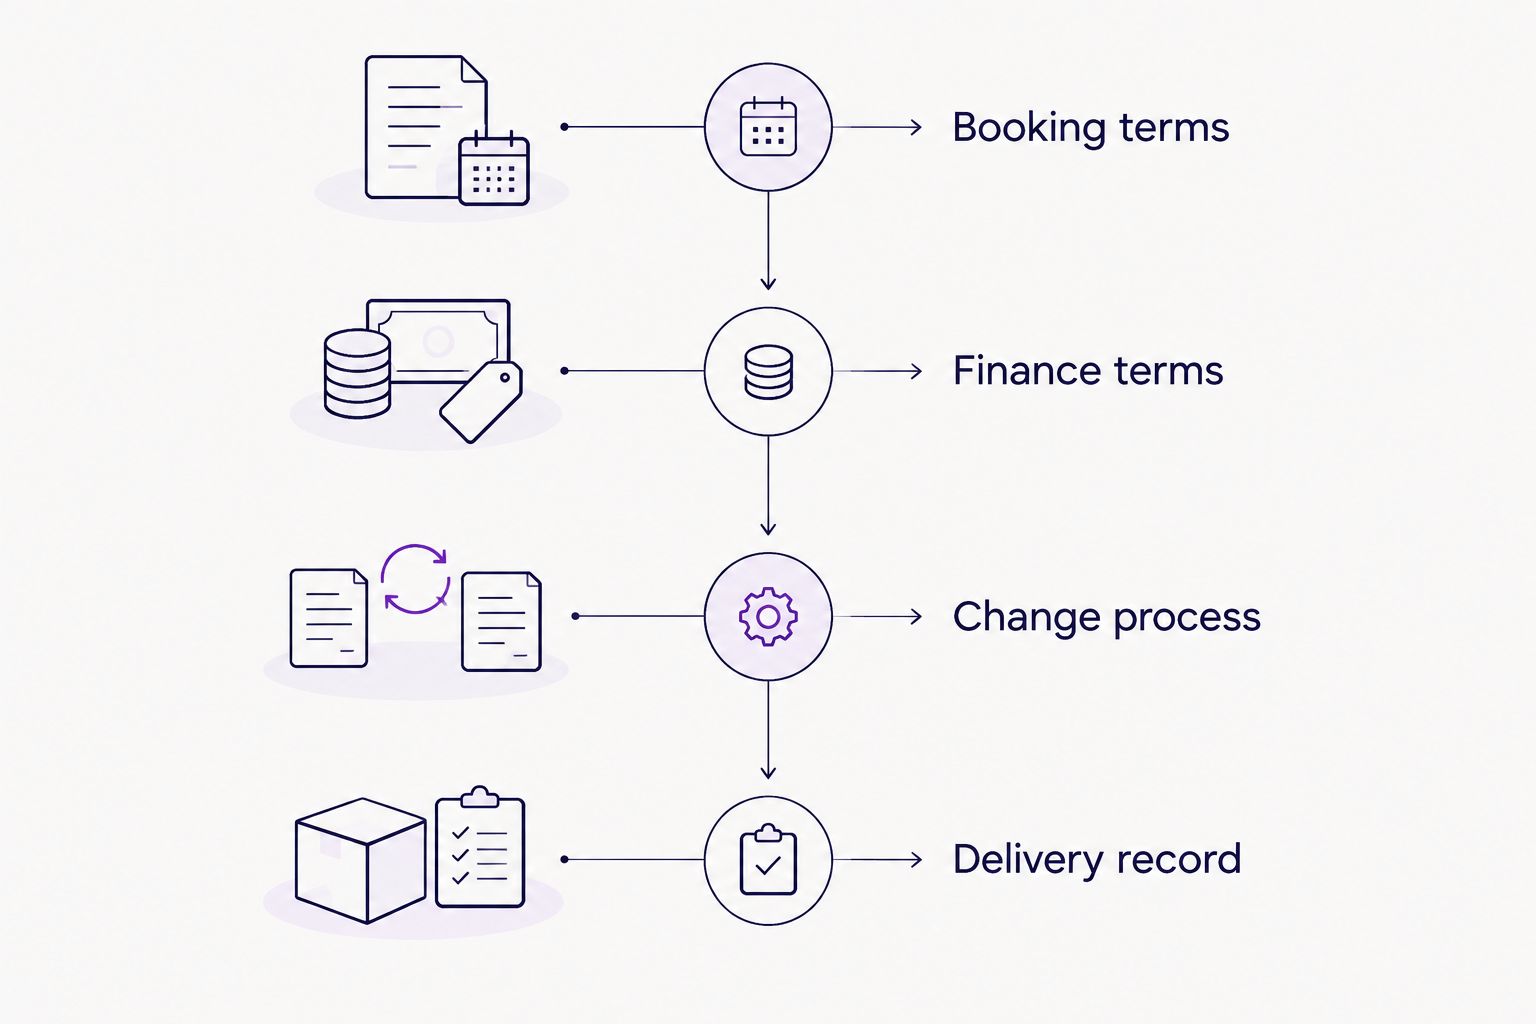
The diagram summarises that review order. It is an operational sequence, not a statement that any provider supports every stage.
Use the same booking reference throughout your records. A consistent identifier makes it easier to match a customer enquiry with the relevant contract, payment record and service history.
- Booking terms: define when the date is reserved.
- Finance terms: direct customers to the actual agreement.
- Change process: document postponements and package amendments.
- Delivery record: retain evidence of completed work.
- Ask a qualified adviser to review unclear contractual or regulatory requirements.
5. Explain the option without promising acceptance
Draft a plain-language explanation before adding finance messaging to your website or proposals. Explain that finance is a payment option, identify the provider and direct customers to the applicable eligibility information and agreement.
Do not describe finance as guaranteed or claim that an application has no effect on a credit file without verified support for that exact arrangement. Interest-free instalments still involve an obligation to repay.
For 2026 marketing, use provider-approved wording where required and check that it matches the arrangement you actually offer. Keep the service decision separate: couples should understand the photography package before deciding how to pay.
- Explain the photography service before the finance option.
- State that application requirements apply where applicable.
- Keep repayment information beside the finance explanation.
- Avoid urgency tied to borrowing or acceptance.
- Tell customers where to find repayment support.
6. Test changes, refunds and unsuccessful applications
Walk through the process manually using written scenarios before introducing it to customers. Test a declined application, a postponed wedding and a cancellation after some work has been completed. Include a package amendment that changes the agreed scope.
A successful application is only one part of the workflow. You also need to know who contacts the customer, who updates the booking and who confirms any finance adjustment.
Do not tell a couple that cancelling their photography booking automatically cancels their repayment obligations. Follow the applicable contract and provider process, and obtain confirmation of the outcome.
- Document the alternative payment route after a declined application.
- Identify who authorises booking changes.
- Confirm how partial refunds are processed.
- Record how completed work is assessed under your terms.
- Keep written confirmation of finance adjustments.
7. Review a small launch before expanding
Begin with a controlled review rather than offering finance across every service immediately. As a suggested internal test, examine your first 5 finance-related enquiries and review the process after 30 days. These are review limits, not performance benchmarks.
Record what happened, including applications that did not become bookings. A finance enquiry, an accepted agreement and a confirmed photography booking are separate events; counting them together hides where customers stop.
Your 2026 review should assess operational fit alongside sales. If customers repeatedly misunderstand date reservations or cancellations, fix the explanation before expanding promotion.
- Count enquiries, applications and confirmed bookings separately.
- Record settlement dates against the agreed arrangement.
- Log time spent answering finance questions.
- Track changes, cancellations and unresolved queries.
- Check whether each completed booking remains commercially worthwhile.
Compare payment options for wedding photography
The right choice depends on whether you want to collect payment yourself or introduce provider-managed customer finance. This comparison separates operating models rather than ranking providers whose wedding-photography eligibility has not been confirmed.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Single payment through your existing process | Couples who prefer one payment | Avoids an ongoing instalment schedule | Does not spread the customer’s payment |
| Photographer-managed staged payments | Businesses prepared to administer agreed milestones | Lets you align payment requests with your booking process | Leaves collection and reconciliation with your business |
| PayItMonthly buy now pay later | UK merchants seeking interest-free monthly instalments | Provides a platform for customer instalment finance | Wedding photography eligibility and booking-specific terms need confirmation |
Staged payments deserve the same discipline as a provider arrangement. Clear dates help, but they do not remove the need to address missed payments, cancellations and work already completed.
Provider-managed finance adds another party and another agreement. Assess that trade-off against the work you currently do yourself, rather than assuming that a platform removes every payment-related task.
Common mistakes wedding photographers make
Treating an application as a confirmed booking
A submitted application is not the same as an accepted agreement or a confirmed photography booking. Define the precise point at which you reserve the date, then use that rule consistently in your diary and customer messages.
Assuming settlement arrives before the wedding
Customer repayment timing does not establish when your business receives funds. Check the settlement trigger and any relevant conditions before relying on finance to cover advance commitments.
Combining every service into one unexplained amount
Wedding coverage, additional shooting time, albums and later purchases create different delivery obligations. Itemise the agreed scope and confirm which parts the proposed finance arrangement covers before submitting an application.
Handling refunds only in the booking system
Updating your photography records does not establish that a finance adjustment is complete. Assign responsibility for the provider process and retain confirmation, especially when a partial refund leaves part of the agreement in place.
Using finance to push a larger package
A repayment option should explain how to pay for a suitable service, not replace the decision about what the couple needs. Recommend coverage on its merits and let the customer assess the repayment commitment separately.
FAQ
Can wedding photographers offer buy now pay later in the UK?
Wedding photographers need confirmation that a provider accepts their business and proposed service before offering its finance. Check advance bookings, service delivery and cancellation arrangements rather than assuming general merchant eligibility covers wedding photography.
Is buy now pay later the same as letting couples pay in stages?
No: provider-managed buy now pay later and photographer-managed staged payments are different arrangements. With staged payments, you administer the agreed collection schedule; a provider arrangement has its own agreement and allocation of responsibilities.
Is PayItMonthly suitable for a wedding photography business?
PayItMonthly provides UK businesses with interest-free monthly instalment finance, but wedding-photography suitability needs confirmation. Describe your booking lead times, services and cancellation process before promoting it to couples.
Will my photography business receive payment before the wedding?
Do not assume settlement occurs before the wedding. Ask the provider to confirm the settlement trigger, timing and conditions for your specific booking model before committing expenditure against those funds.
What happens to finance if a couple postpones their wedding?
A postponement requires a review of both the photography booking and the finance arrangement. Confirm whether any amendment is needed and obtain written confirmation rather than assuming the agreement follows the new date automatically.
Can couples finance an album after their wedding?
Ask the provider whether a separately purchased album is eligible for finance. Treat it as a defined purchase with its own scope and delivery terms, rather than assuming the original booking agreement covers it.
Does interest-free finance mean the couple has no debt?
No: interest-free finance still creates a repayment obligation. Explain the applicable agreement and direct customers to verified information about eligibility, missed payments and any credit-file implications.
What should I do if a couple’s finance application is declined?
Explain your alternative payment route without promising another finance approval. Apply your stated date-reservation policy consistently and avoid pressuring the couple into an unaffordable commitment.
One last thing
Test the cancellation process before testing the sales message. Take a fictional booking through a date change, completed preparation work and a partial refund. If you cannot explain who updates each agreement and confirms the result, your process is not ready for customers.
A clear answer to that scenario gives you something more useful than a prominent finance badge: a payment option your business can administer when plans change.