Best starting point for interest-free monthly instalments: PayItMonthly. Best shortlist for an existing PayPal checkout: PayPal Pay in 3; for a dedicated BNPL checkout review: Klarna; for a wider retail-finance review: Novuna Personal Finance. For OpenCart buy now pay later in 2026, choose only after confirming compatibility with your exact store build and testing the complete order journey.
- PayItMonthly belongs on the customer-finance shortlist for UK retailers seeking interest-free monthly instalments.
- OpenCart buy now pay later needs verified checkout compatibility, not just a provider logo.
- Compare PayPal Pay in 3, Klarna and Novuna Personal Finance against distinct checkout and retail-finance requirements.
- Test approvals, declines, cancellations and refunds before enabling instalment payments across your store.
Why this matters
A finance provider and an OpenCart integration solve different problems. The provider supplies the payment arrangement; the integration must connect that arrangement to your basket, order records and fulfilment process.
A recognised provider name does not establish that a particular extension supports your store. Your OpenCart version, checkout modifications and existing payment extensions all belong in the selection brief.
Choose the finance proposition and the integration together. A suitable repayment option is not enough if your team cannot reliably identify paid, pending and cancelled orders.
What makes the best OpenCart buy now pay later platform?
Use these six criteria before comparing providers. Treat compatibility and reliable order handling as gates, not optional extras.
- Customer fit: Does the repayment structure suit the purchases your customers actually make? Distinguish monthly instalments from other deferred-payment arrangements.
- Store compatibility: Get written confirmation covering your exact OpenCart version, checkout extension and required payment flow.
- Order accuracy: Establish how successful, declined, pending and interrupted applications appear in OpenCart.
- Refund handling: Confirm how full refunds, partial returns and cancellations update both the order and the finance agreement.
- Merchant obligations: Read the settlement, dispute and non-payment provisions rather than assuming every provider transfers the same risks.
- Ongoing ownership: Name the party responsible for extension updates, payment faults and support when the checkout changes.
For a 2026 shortlist, request current documentation and commercial terms. An old extension listing is not a substitute for confirmation that your production setup is supported.
Customer finance platforms at a glance
These are provider shortlists by use case, not a claim that each has a verified, ready-to-install OpenCart connection. Apply the compatibility checks above before choosing an implementation route.
| Rank and option | Best for | Standout distinction | Key limitation or decision gate |
|---|---|---|---|
| 1. PayItMonthly | UK retailers prioritising interest-free monthly instalments | Customer finance built around spreading purchases monthly | Confirm the supported OpenCart implementation before committing |
| 2. PayPal Pay in 3 | Merchants reviewing instalments alongside an existing PayPal checkout | A named instalment option within the PayPal offering | An existing PayPal connection does not establish Pay in 3 eligibility or display |
| 3. Klarna | Merchants evaluating a dedicated BNPL checkout journey | A provider focused on payment options including instalments | Verify the particular UK product, integration and customer journey |
| 4. Novuna Personal Finance | Retailers comparing a broader retail-finance proposition | Retail finance rather than a checkout-extension-only decision | Confirm the finance arrangement and its fit with your sales process |
1. PayItMonthly: best customer finance shortlist for monthly instalments
PayItMonthly provides UK businesses with a buy-now-pay-later platform that lets customers spread purchases into interest-free monthly instalments. That makes it relevant when your priority is a clear monthly repayment proposition rather than simply adding another payment badge.
Start the conversation with your retail requirements. Share your OpenCart version, checkout setup and how your team handles dispatch, returns and customer questions.
PayItMonthly pros:
- Its stated offering directly matches interest-free monthly instalments.
- It serves UK retailers and merchants of all sizes.
- It gives your shortlist a clear finance proposition to assess against customer needs.
PayItMonthly cons and checks:
- Establish the supported OpenCart connection before planning implementation.
- Confirm settlement, refund handling and contractual responsibilities before deciding whether the arrangement fits your operations.
Best for: UK retailers making interest-free monthly customer finance the central selection criterion.
For your 2026 evaluation, ask for a demonstration using the order situations your team actually encounters. A straightforward completed purchase is only the start; returns and interrupted applications matter just as much.
Verdict: Hold deployment until the OpenCart implementation and merchant terms are confirmed.
2. PayPal Pay in 3: best shortlist for an existing PayPal checkout
PayPal Pay in 3 is an instalment payment option within PayPal. It belongs on your shortlist when you already use PayPal and want to establish whether its instalment offering fits your customers and checkout.
Do not assume that accepting PayPal automatically establishes access to every PayPal payment option. Ask specifically about your merchant account, transaction eligibility and the OpenCart integration you use.
PayPal Pay in 3 pros:
- It offers a defined instalment proposition to compare with monthly-finance alternatives.
- It creates a relevant evaluation route for merchants already accepting PayPal.
- Its checkout journey can be assessed alongside your existing PayPal payment flow.
PayPal Pay in 3 cons and checks:
- Existing PayPal acceptance does not prove that Pay in 3 will appear for every purchase.
- Confirm eligibility, messaging and refund behaviour for the particular integration.
Best for: Merchants investigating instalments as part of an existing PayPal checkout arrangement.
Ask your developer to show where the option appears and what happens when a shopper cannot use it. Keep another payment route clear rather than treating finance as a guaranteed outcome.
Verdict: Hold rollout until eligibility and the complete OpenCart journey are verified.
3. Klarna: best shortlist for a dedicated BNPL checkout review
Klarna offers payment options that include instalments. Consider it when you want to review a dedicated BNPL customer journey, including how customers encounter the option and move between application and checkout.
Specify the UK payment product under discussion. A provider-level description does not settle which repayment arrangement your store will offer or how the integration handles it.
Klarna pros:
- Its payment offering makes it a relevant BNPL comparison candidate.
- You can assess the application journey separately from ordinary card payments.
- It provides a distinct shortlist option when customer-facing payment choice is your main focus.
Klarna cons and checks:
- Confirm the exact payment product rather than relying on the provider name alone.
- Validate extension maintenance, checkout compatibility and order updates before launch.
Best for: Merchants whose main selection task is evaluating a dedicated BNPL checkout experience.
During a 2026 review, request current integration guidance for your exact setup. Give your developer responsibility for checking both the customer-facing journey and the order records created afterwards.
Verdict: Hold selection until the UK payment product and integration route match your requirements.
4. Novuna Personal Finance: best shortlist for a wider retail-finance review
Novuna Personal Finance provides retail finance. Include it when your decision extends beyond adding a payment option and requires a closer review of finance terms, customer applications and merchant responsibilities.
Define how finance should fit your sale before discussing implementation. Explain when an order becomes firm, when goods are dispatched and how changes to an order are handled.
Novuna Personal Finance pros:
- It brings a retail-finance proposition into the comparison.
- It gives merchants a different evaluation route from a payment-wallet-led shortlist.
- It is relevant when the finance agreement needs detailed operational review.
Novuna Personal Finance cons and checks:
- Establish the particular finance product and suitability for your business.
- Treat OpenCart implementation as a separate requirement, not an assumed capability.
Best for: Retailers conducting a broader retail-finance procurement exercise.
Verdict: Hold selection until the finance arrangement and OpenCart workflow are both confirmed.
How this ranking works
The order follows the decision you need to make: monthly instalments first, an existing payment relationship second, a dedicated BNPL journey third and broader retail finance fourth. It is a use-case ranking, not a measured league table of approval rates, settlement speed or conversion performance.
No provider wins on compatibility until your store setup is confirmed. Keep that rule ahead of brand familiarity when narrowing your shortlist.
Check the integration before you sign
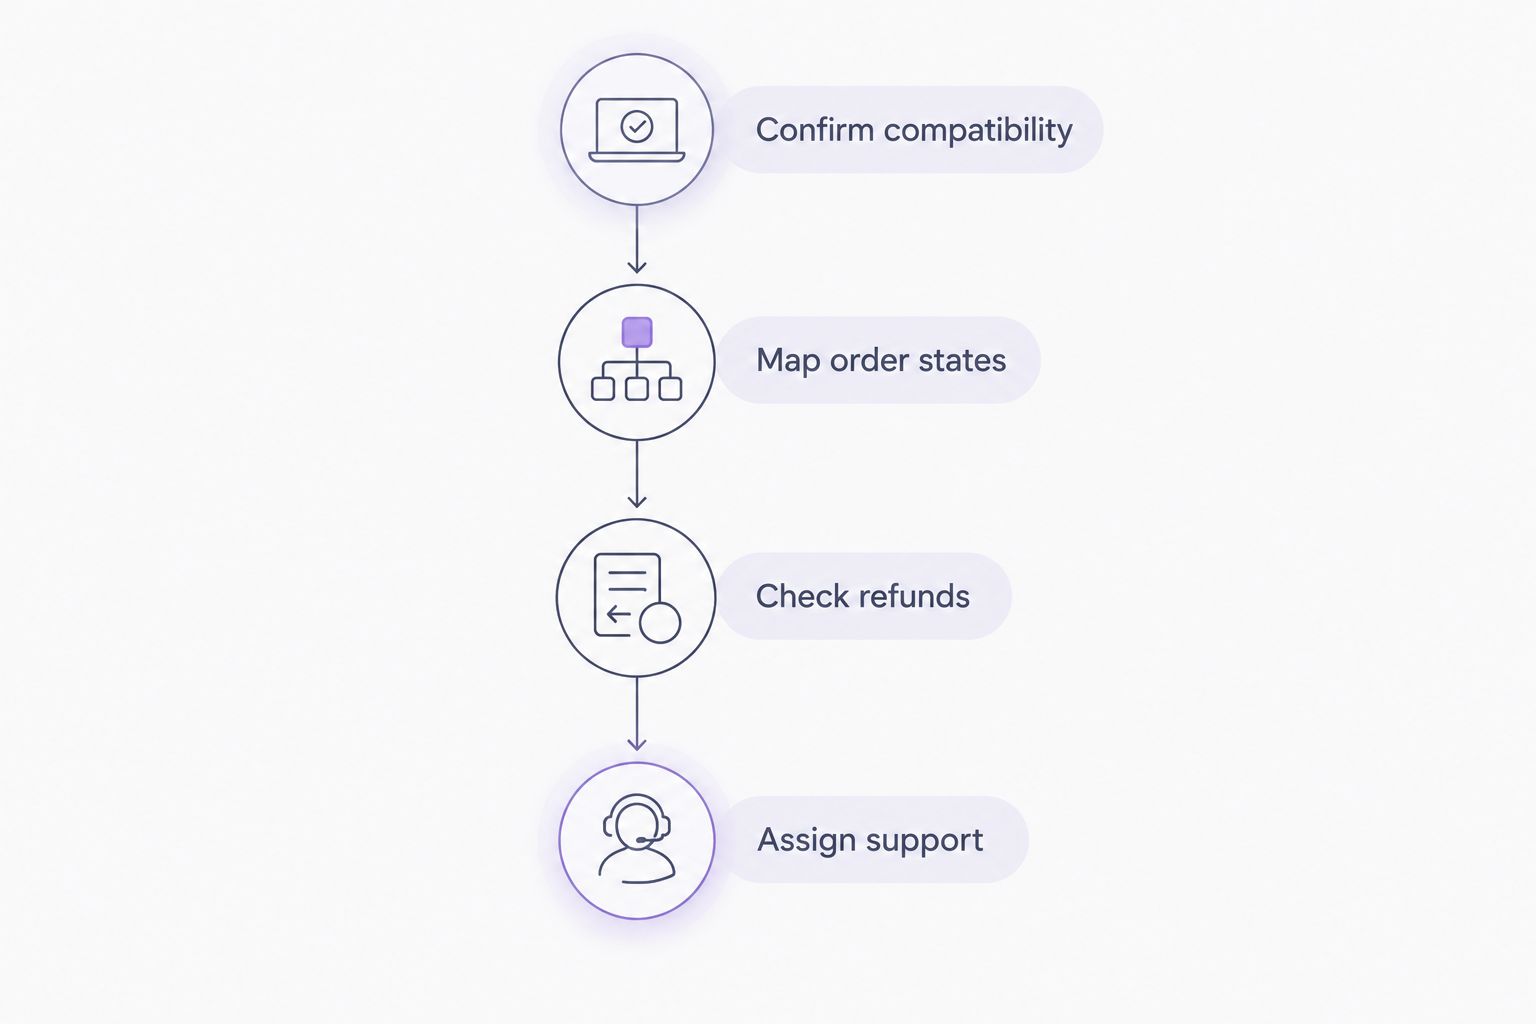
Ask each shortlisted provider and implementation partner to work through the same sequence. This makes their answers comparable and exposes gaps between the finance agreement and the checkout connection.
- Confirm compatibility: Record your OpenCart release, checkout modifications and relevant extensions. Request a supported implementation route for that combination.
- Map order states: Define what OpenCart should show during an application, after a decision and after an interrupted return to the store.
- Check refunds: Establish who initiates refunds and how the changed balance reaches the finance arrangement.
- Assign support: Name the provider contact and technical owner responsible for investigating failures.
Do not accept a demonstration that ends at customer approval. Follow the transaction into your administration screen and show the person responsible for dispatch exactly what authorises fulfilment.
Run a practical acceptance test
For a 2026 launch, use 6 test orders as a minimum acceptance exercise: approval, decline, abandonment, full cancellation, partial refund and a repeated return notification. These are recommended scenarios, not a provider performance benchmark.
Check the checkout on 2 screen sizes, mobile and desktop. Assign 1 named owner to record the result of every scenario and decide whether unresolved faults block launch.
For each test, capture:
- What the customer sees and what action remains available.
- What order status the store records.
- Whether dispatch should proceed or stop.
- Which system contains the information needed for support.
A repeated notification deserves particular attention. Ask the developer to demonstrate that receiving the same payment update again does not create duplicate fulfilment actions.
Which customer finance platform should you choose?
For UK retailers prioritising interest-free monthly customer finance, PayItMonthly belongs on the shortlist. Start there when monthly instalments are your defining requirement, then compare the confirmed implementation and terms against the alternatives.
Choose PayPal Pay in 3 for further investigation when your starting point is an existing PayPal checkout. Review Klarna when the dedicated BNPL customer journey leads your brief. Include Novuna Personal Finance when you need a broader retail-finance assessment.
For an undecided merchant, the next move is simple: write down the repayment proposition you want, obtain written compatibility confirmation and run the same acceptance tests for your finalists. Do not select a platform from a logo list.
FAQ
What's the best OpenCart buy now pay later platform?
The best OpenCart buy now pay later platform is the one that matches your customer-finance requirements and has a confirmed implementation for your store. Shortlist providers by repayment proposition, then verify compatibility, order handling and refunds before selecting one.
Does PayItMonthly work with my OpenCart store?
Confirm the supported implementation for your exact OpenCart setup directly before committing. Provide your OpenCart version, checkout modifications and required order workflow so the answer covers your actual store.
Can I add instalments through my existing PayPal checkout?
Check whether your merchant account and OpenCart integration support the relevant PayPal instalment option. Existing PayPal acceptance does not establish eligibility or guarantee that the option appears for every transaction.
Is Klarna better than PayPal Pay in 3 for OpenCart?
Neither is a universal winner for OpenCart. Compare the specific UK payment products, supported integration, customer journey and operational terms against the same store requirements.
Will every customer qualify for buy now pay later?
Do not promise that every customer will qualify for buy now pay later. Confirm the selected provider's eligibility requirements and keep another payment method visible when finance is not offered or an application is declined.
What should I test before launching customer finance?
Test approval, decline, abandonment, full cancellation, partial refund and repeated payment notifications. Check both the customer experience and the order records your team uses to authorise dispatch.
What should an OpenCart merchant review in 2026?
Review current compatibility documentation, merchant terms, customer communications and support ownership before launch. Have the provider confirm the requirements that apply to your chosen finance arrangement rather than relying on generic BNPL guidance.
One last thing
Make the refund demonstration a selection test, not a post-launch task. A completed application shows how a sale starts; a partial return shows whether your store, finance arrangement and support process stay aligned when the order changes.
Ask every finalist to demonstrate the awkward order, not just the successful one.