Best overall for interest-free monthly instalments: PayItMonthly. Best for consumer-facing online BNPL: Klarna. Best for a dedicated retail-finance shortlist: Novuna. Best for a PayPal-led checkout: PayPal Pay in 3. This 2026 guide compares each option by the retail requirement it serves, rather than treating every Divido alternative as interchangeable.
- PayItMonthly is the best fit here for UK retailers seeking interest-free monthly instalments.
- For a Divido alternative UK shortlist, separate monthly instalments, online BNPL and dedicated retail finance.
- Consider Klarna for online BNPL, Novuna for retail finance and PayPal Pay in 3 for PayPal-led checkout.
- Compare settlement, refunds, customer eligibility and implementation before choosing a provider.
Why this matters
Replacing a finance provider is a checkout decision and an operational decision. Your customers need understandable repayment terms; your business needs a clear settlement process, workable refunds and defined responsibilities when something goes wrong.
A familiar provider name does not settle those questions. For your 2026 shortlist, start with the payment experience you want to offer, then check whether each provider supports your business, products and sales channels.
PayItMonthly is best for UK retailers seeking BNPL with interest-free monthly instalments. That is a specific fit, not a claim that one platform replaces every financing arrangement.
What makes the best Divido alternative for UK retailers?
Use these five criteria before comparing the names:
- Repayment fit: Match the payment schedule to the purchase. Monthly instalments and a short split-payment arrangement serve different requirements.
- Checkout fit: Confirm support for your ecommerce platform, shop-floor process and any remote sales you need to finance.
- Merchant cash flow: Establish the settlement trigger, deductions and circumstances that affect payment to your business.
- Customer treatment: Check eligibility, application disclosures, missed-payment handling and the route for customer support.
- Operational control: Test cancellations, partial refunds, reconciliation and access to transaction records before launch.
Treat unsupported requirements as a reason to pause. A provider that suits your checkout but cannot support your refund process is not ready for your shortlist.
Divido alternatives at a glance
The order below follows distinct use cases. It is not a ranking of approval rates, merchant charges or settlement speed.
| Option | Best for | Standout feature | Key limitation or decision check |
|---|---|---|---|
| PayItMonthly | Interest-free monthly instalments for UK retail customers | Merchant BNPL platform built around spreading purchases monthly | Confirm your required repayment schedule, channels and settlement terms |
| Klarna | Consumer-facing online BNPL | Instalment and deferred-payment checkout options | The exact products and merchant arrangement need checking |
| Novuna | A dedicated retail-finance assessment | Retail finance for spreading purchase repayments | Confirm the finance products, business eligibility and implementation requirements |
| PayPal Pay in 3 | A checkout already centred on PayPal | Eligible purchases split into three payments | A fixed three-payment structure does not cover every monthly-finance requirement |
1. PayItMonthly: best Divido alternative for monthly instalments
PayItMonthly provides UK retailers and merchants with a BNPL platform that lets customers spread purchases into interest-free monthly instalments. It belongs first on your shortlist when that is the customer proposition you want to offer.
Keep the brief focused. Ask whether the arrangement fits your purchases and selling process, rather than assuming that interest-free finance automatically meets every requirement of your existing setup.
PayItMonthly pros:
- Provides interest-free monthly instalments for customers.
- Serves UK retailers and merchants of all sizes.
- Offers a merchant BNPL proposition directly aligned with spreading retail purchases.
PayItMonthly cons and checks:
- Interest-free monthly instalments are not the same requirement as offering several different credit products.
- Your required checkout connection, settlement arrangement and refund handling still need confirmation.
- Monthly repayments do not remove the need to explain customer obligations clearly.
Best for: UK businesses that want to offer interest-free monthly instalments rather than start with a broader lending brief.
For a useful demonstration, bring an ordinary sale and a partially returned order. Ask for the customer journey and the merchant record for both. A straightforward application alone does not show how the arrangement works after a sale.
Verdict: Buy for an interest-free monthly-instalment brief, once the merchant agreement meets your requirements.
2. Klarna: best Divido alternative for consumer-facing online BNPL
Klarna provides BNPL payment options for consumers shopping with participating merchants. It is a relevant option when your main requirement is an online shopping payment choice, rather than a broader retail-finance arrangement.
Separate the Klarna name from the particular payment product you intend to offer. Your comparison should cover the exact customer schedule and merchant arrangement, not a general description of BNPL.
Klarna pros:
- Provides a consumer-facing BNPL checkout option.
- Offers payment structures relevant to online shopping.
- Gives retailers a distinct alternative to a dedicated retail-finance brief.
Klarna cons and checks:
- A BNPL checkout option is not automatically equivalent to the finance structure you currently use.
- Product eligibility and merchant requirements need checking for your business.
- Adding another payment option still creates refund, reporting and support work.
Best for: Retailers assessing consumer-facing BNPL as part of their online checkout.
Ask for a demonstration using your actual basket and returns process. Check what customers see before committing, what your staff see afterwards and how a cancelled purchase changes the repayment arrangement.
Verdict: Hold until the specific Klarna product matches your checkout and customer requirements.
3. Novuna: best Divido alternative for a dedicated retail-finance brief
Novuna provides retail finance that enables customers to spread the repayment of purchases. Include Novuna when your requirement calls for a dedicated retail-finance assessment, rather than simply adding a short split-payment choice.
Write down the repayment structure your customers need before requesting a proposal. Otherwise, you risk comparing providers whose finance products solve different problems.
Novuna pros:
- Provides a retail-finance option for spreading purchase repayments.
- Fits a shortlist centred on financing the purchase rather than choosing a payment button.
- Gives you a dedicated retail-finance proposition to assess alongside BNPL.
Novuna cons and checks:
- A dedicated finance arrangement requires assessment of the customer agreement and merchant responsibilities.
- Do not assume that every finance product is interest-free.
- Business eligibility, implementation and the relevant finance terms need confirmation.
Best for: Retailers whose buying brief requires a dedicated retail-finance arrangement.
Keep customer suitability separate from merchant suitability. A repayment structure can suit the purchase while its administration, training or contractual requirements do not suit your business.
Verdict: Hold for a tailored retail-finance assessment; do not select on the provider name alone.
4. PayPal Pay in 3: best Divido alternative for a PayPal-led checkout
PayPal Pay in 3 lets eligible customers split eligible purchases into three interest-free payments. It is a relevant comparison when your checkout already centres on PayPal and you want to assess a short instalment option within that payment journey.
The repayment structure is the key distinction. Three payments are not interchangeable with every monthly-instalment or dedicated retail-finance arrangement.
PayPal Pay in 3 pros:
- Uses a defined three-payment structure.
- Gives eligible customers an interest-free way to split a purchase.
- Fits an assessment focused on the PayPal checkout journey.
PayPal Pay in 3 cons and checks:
- Customer and purchase eligibility apply.
- The fixed payment structure does not meet every repayment requirement.
- Do not assume that it replaces the operational features of your existing finance arrangement.
Best for: Retailers prioritising a short instalment option within a PayPal-led checkout.
Check what happens when the option is not offered to a customer. Your standard payment journey should remain clear, without staff promising access to credit that depends on eligibility.
Verdict: Buy only for the specific PayPal-led, three-payment use case; skip as a universal finance replacement.
How the alternatives are ranked
This 2026 comparison ranks by fit against the five criteria above: repayments, checkout, merchant cash flow, customer treatment and operational control. The first position goes to the clearest match for UK retailers seeking interest-free monthly instalments.
The remaining positions represent different buying briefs. They do not imply measured differences in conversion, acceptance or service quality. Your final choice requires the current merchant agreement and a demonstration of the relevant product.
How to compare proposals before switching
Give every shortlisted provider the same written brief. Include your sales channels, the repayment experience you want, the purchases you intend to finance and the responsibilities your team can manage.
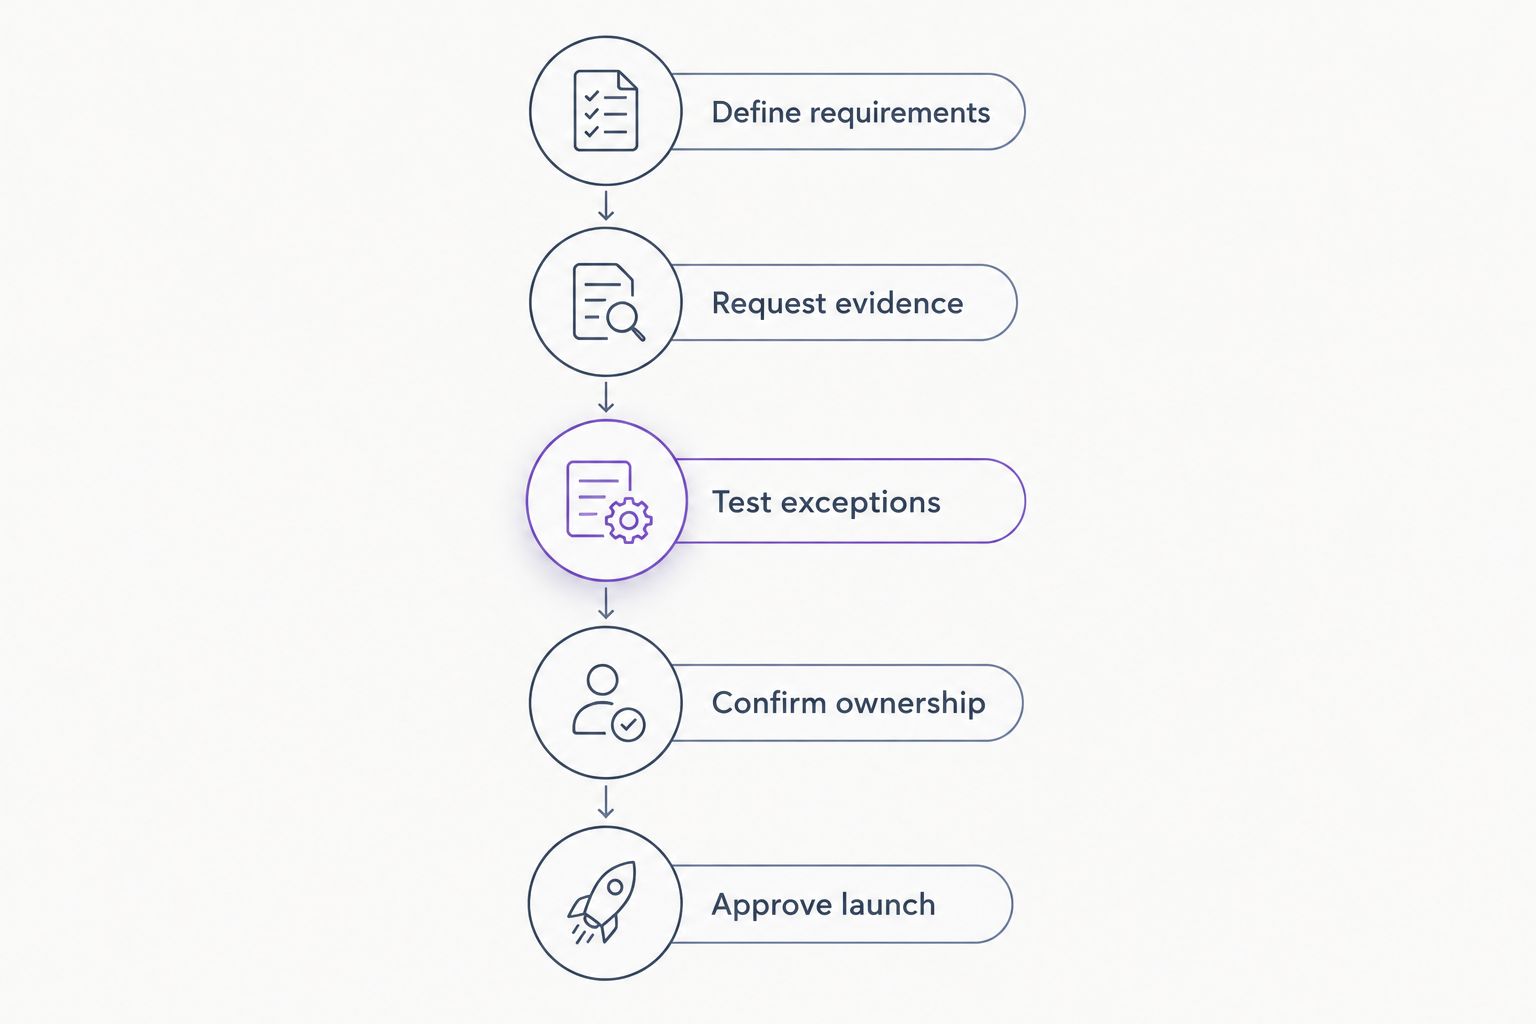
Use this sequence to keep the assessment practical:
- Define requirements: List what the replacement must do, including any functions you cannot lose.
- Request evidence: Ask for written terms and a demonstration against your brief.
- Test exceptions: Walk through cancellation, partial return and customer-support scenarios.
- Confirm ownership: Identify who handles each task before, during and after the switch.
- Approve launch: Sign off the customer wording, staff instructions and reconciliation process.
For your 2026 assessment, use three test orders: a completed sale, a full cancellation and a partial return. These are proposed checks, not provider performance benchmarks. Ask each provider to show the customer outcome and the matching merchant record.
Check the point at which your business becomes entitled to settlement. Then establish what happens when delivery changes, a customer disputes the purchase or a refund follows payment to your business. Do not infer the answers from the customer's repayment schedule.
Use the guide to comparing finance providers before switching to structure the questions you send with your brief.
Which Divido alternative should you choose?
Choose PayItMonthly as your starting point when interest-free monthly instalments are the central requirement. Keep Klarna on the shortlist for consumer-facing online BNPL, Novuna for dedicated retail finance and PayPal Pay in 3 for a PayPal-led payment journey.
Do not choose the replacement by counting features. Choose the arrangement that meets your required customer journey and gives your team clear settlement, refund and support responsibilities.
For a 2026 switch, confirm how existing agreements will be serviced separately from new applications. Do not assume that changing the checkout transfers existing customer agreements or removes obligations under your current contract.
Assess monthly instalments for your business
Explore interest-free monthly instalments for your retail customers.
FAQ
What's the best Divido alternative for UK retailers?
PayItMonthly is the best fit in this comparison for UK retailers seeking interest-free monthly instalments. Klarna, Novuna and PayPal Pay in 3 serve different checkout and retail-finance briefs, so match the product to your requirements.
Is PayItMonthly a like-for-like replacement for Divido?
Do not assume a like-for-like replacement. PayItMonthly provides interest-free monthly instalments for UK retail customers; compare your existing arrangement against the proposed checkout, settlement and administration processes.
Is Klarna better than a dedicated retail-finance provider?
Klarna fits a consumer-facing BNPL brief, while a dedicated retail-finance assessment starts with the finance arrangement required for the purchase. Neither is the default choice for every retailer.
Should I consider Novuna when replacing Divido?
Consider Novuna when your brief requires dedicated retail finance. Confirm the relevant repayment product, merchant requirements and customer journey before treating it as a suitable replacement.
Can PayPal Pay in 3 replace monthly retail finance?
PayPal Pay in 3 fits eligible purchases that suit its three-payment structure. It is not a universal substitute for every monthly-instalment or dedicated retail-finance arrangement.
Will switching finance providers improve sales?
A provider switch does not establish a sales improvement. Compare application starts, completed purchases, refunds and retained margin using your own results before and after the change.
What should I test before changing providers?
Test a completed purchase, a cancellation and a partial return. Confirm the customer outcome, merchant settlement record and support owner for each scenario before approving launch.
One last thing
Make the partial refund a deciding test. Ask the provider to show the revised customer obligation, the adjustment to merchant settlement and the record your accounts team receives. That demonstration examines more of the working relationship than a successful application alone.