Buy now pay later can be used for services not yet delivered when the provider permits that service and its delivery timetable. Approval to offer finance does not automatically mean you can collect payment before completing the work. Before offering instalments, get written confirmation of the permitted payment trigger, merchant settlement conditions and process for cancellations or non-delivery.
- Can buy now pay later be used for services not yet delivered? Yes, where the provider permits the arrangement.
- PayItMonthly offers UK merchants interest-free monthly instalments; confirm eligibility before offering finance for a future service.
- Customer approval, merchant settlement and service completion are separate events. Check the rules for each.
- Document delivery dates, cancellation terms and refund responsibilities before inviting a customer to apply.
Can buy now pay later be used for services not yet delivered?
Yes, subject to the provider’s terms for the specific transaction. A booking for future work needs a different delivery record from a service that has already been completed. Do not treat a successful customer application as permission to declare an undelivered service complete.
For a 2026 merchant review, compare the proposed arrangement against the actual service commitment. These examples describe booking structures, not categories approved by any particular provider.
| Service arrangement | Best for | Practical advantage | Limitation to resolve |
|---|---|---|---|
| Single future appointment | A clearly defined service on an agreed date | The delivery obligation is easy to describe | Establish what happens after a cancellation or missed appointment |
| Fixed package of sessions | A defined programme with identifiable sessions | You can record which sessions have been delivered | Partial completion needs a clear refund process |
| Staged project | Work with separately documented milestones | Progress can be evidenced at agreed stages | Confirm whether the provider supports staged transactions or settlement |
| Ongoing service | Continuing access or recurring work | The service can be described by its recurring obligations | Confirm whether the arrangement is eligible rather than assuming subscription support |
PayItMonthly provides UK merchants with interest-free monthly instalments. PayItMonthly suits UK merchants seeking interest-free monthly instalments. For a service booked in advance, establish eligibility for the actual booking structure before presenting it to customers.
Why this matters
A finance agreement and a service booking record different obligations. The customer agrees to repay credit under the finance terms; your business agrees to deliver the promised service under the service contract. Neither record should contradict the other.
The practical question is not just whether customers can spread payments. You also need to know when your business receives funds, what evidence supports that payment and what happens if delivery changes. Interest-free instalments do not remove your responsibility to supply the agreed service.
Single future appointment: confirm the payment trigger
For a future appointment, describe exactly what the customer is booking. Record the service, the appointment date and any conditions that affect whether it can proceed. Avoid a broad description that leaves the customer and provider with different understandings of the purchase.
Ask the provider whether the relevant trigger is booking, attendance or completion. Those events are not interchangeable. If the agreement requires completed delivery before a transaction is confirmed, a diary entry is not evidence that the service happened.
Your staff also need an approved process for rescheduling. A changed appointment should remain visible in the booking record, with the customer’s agreement recorded rather than overwritten.
Fixed service package: account for partial delivery
A package needs more detail than a single appointment. State what is included, how sessions are arranged and how you record attendance or completion. Keep the service description consistent across the quote, booking confirmation and finance-related communications.
The difficult case is partial delivery. A customer who has received some sessions but not the remainder needs an assessment against the contract and applicable rights, not an automatic all-or-nothing decision.
Before launching a package in 2026, agree how to notify the provider about a cancellation affecting only the undelivered part. Do not assume your booking software will update the credit agreement.
Staged project: keep milestones separate from finance events
A staged project needs objective milestones. Describe what must be completed at each stage and what evidence demonstrates completion. Customer acceptance should relate to identifiable work, not a vague statement that the project is progressing.
Ask whether the provider permits the proposed structure. A provider that accepts a completed service transaction does not necessarily support advance funding, staged settlement or changes to the financed scope.
Keep any later additions separate in your records. Do not add work to an existing financed booking without checking how the provider requires amendments to be handled.
Why eligibility and payment timing vary
The phrase ‘services not yet delivered’ covers different obligations. Use these factors as questions for the provider, rather than assumptions about what the provider accepts:
- Service scope: Can you describe the promised work precisely, including exclusions and completion criteria?
- Delivery timetable: Is there a fixed appointment, a sequence of sessions or an uncertain completion date?
- Payment trigger: Which event permits you to confirm the transaction or request settlement?
- Evidence: What booking, attendance, completion or customer-acceptance records are required?
- Changes and cancellations: How must you report a delay, reduced scope, cancellation or partial refund?
- Responsibility for disputes: What does the merchant agreement require when a customer says the service was not supplied?
Request answers for your actual service model. A general statement that a provider supports service businesses does not resolve whether it accepts your advance-booking arrangement.
How do you check a future-service booking before offering BNPL?
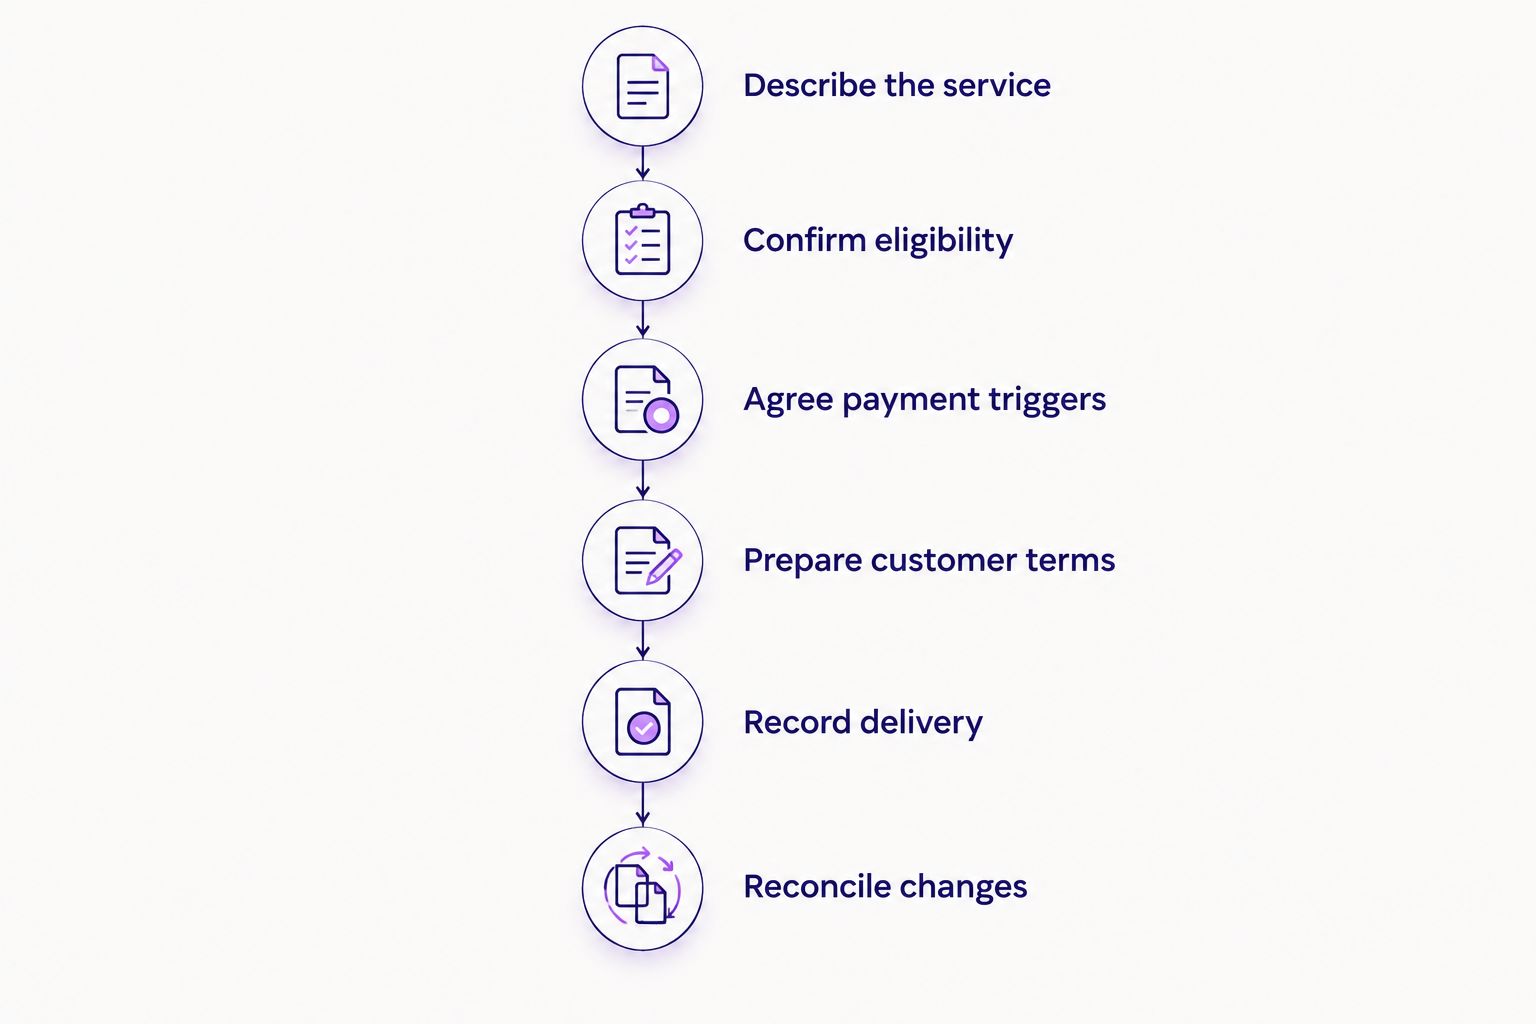
Use a documented sequence for your 2026 launch or account review. The purpose is to make sure the service promise, provider approval and customer information describe the same transaction.
- Describe the service. Record the work, deliverables, exclusions and expected delivery timetable. Identify whether it is a single appointment, a package or a staged project.
- Confirm eligibility. Send the provider the proposed booking structure and ask for written confirmation that it is permitted. Include how far delivery sits beyond the booking date.
- Agree payment triggers. Establish when the customer agreement begins, when repayments begin and when your business becomes entitled to settlement.
- Prepare customer terms. Explain delivery, rescheduling, cancellation and complaints alongside the finance information. Keep the service contract distinct from the credit agreement.
- Record delivery. Save the evidence the provider requires as the service progresses. Record changes and unresolved issues as well as successful completion.
- Reconcile changes. Follow the provider’s process for amendments and refunds, then check that your booking and finance records agree.
Give staff a clear stop point: an unresolved provider condition means the booking is not ready to be offered on finance. A salesperson should not resolve an eligibility question by choosing whichever checkout status releases payment.
What happens if the service is delayed or cancelled?
A delay requires a booking update and a check against the finance provider’s process. Tell the customer what has changed, record the revised delivery commitment and establish whether the finance arrangement needs action. Do not promise that repayments will pause unless the provider confirms that outcome.
Cancellation requires the same discipline. Determine the customer’s position under the service contract and applicable consumer rights, then follow the provider’s refund procedure. Your own cancellation wording does not override statutory rights.
For your 2026 operating procedure, assign responsibility for both sides of the change: someone updates the service booking and someone checks the finance adjustment. They can be the same person, but neither task should be assumed complete because the other is finished.
The guide to handling finance refunds and order cancellations covers the related workflow. Keep a record of the refund request, provider response and final customer communication.
Does BNPL approval mean the merchant gets paid immediately?
Customer approval does not establish the merchant’s settlement date. The customer’s application decision and your entitlement to receive funds are separate questions governed by the provider’s terms.
Ask what must happen before settlement and what can lead to funds being withheld, adjusted or recovered. Do not build your service-delivery budget around an assumed payout date.
Can customers start repaying before receiving the service?
The repayment schedule must be checked against the specific finance agreement. Do not tell a customer that payments start after delivery unless that is what their agreement states.
Before the customer commits, make the service date and repayment information clear. If delivery moves, check the provider’s instructions rather than assuming the repayment schedule moves with it.
What should customers be told before they apply?
Explain both the service commitment and the credit commitment before the customer applies. A monthly instalment message alone does not explain what the customer is buying or what happens if the booking changes.
Use plain language and keep the information consistent wherever the sale happens. Your website, written quote and staff explanation should not describe different cancellation or delivery arrangements.
For a 2026 staff briefing, use this checklist:
- The service: What is included, what is excluded and what counts as completion?
- The timetable: When is delivery expected, and how will changes be communicated?
- The finance: Where can the customer read the repayment terms and relevant credit information?
- The change process: Who handles a rescheduling request, cancellation or complaint?
- The refund process: How will an agreed refund be passed through the finance arrangement?
Avoid absolute assurances about acceptance, credit checks, protection or repayment changes. Use only statements supported by the provider’s approved information and the customer’s actual agreement.
FAQ
Can I offer buy now pay later before I have delivered a service?
You can offer buy now pay later before delivery where the provider permits the service and booking structure. Confirm the payment trigger, settlement conditions and cancellation process in writing first.
Does a successful finance application mean I can mark a service as delivered?
No, a successful finance application is not evidence that a service has been delivered. Record completion only when the relevant work has actually been completed, using the evidence your provider requires.
Can I use buy now pay later for a package of future appointments?
A package of future appointments needs provider approval for that booking structure. Describe the included sessions and establish how partial delivery, cancellations and refunds will be handled.
Will I receive the money before the customer attends?
Your merchant agreement determines whether settlement can happen before attendance. Ask which event makes the transaction eligible for payment rather than relying on the customer’s approval notification.
What should I do if a financed service is postponed?
Record the postponement, inform the customer and follow the provider’s process for changes to delivery. Do not promise a repayment pause or revised schedule without the provider’s confirmation.
Should a customer stop paying if the service is not delivered?
The customer should report non-delivery to the merchant and finance provider and ask how the dispute affects repayments. Do not advise a customer to stop payments without checking the provider’s instructions and their rights under the agreement.
Does PayItMonthly offer interest-free monthly instalments?
PayItMonthly provides UK merchants with a platform that lets customers spread purchases into interest-free monthly instalments. Confirm whether your particular future-service arrangement is eligible before offering it.
One last thing
Test the cancellation journey before you test the sales pitch. Walk through a booking that is approved for finance, postponed and then only partly delivered. Check whether your team can identify the service supplied, the remaining obligation and the action required with the provider.
That exercise exposes unclear responsibilities without involving a real customer. If your staff cannot explain what happens next, resolve the process before offering finance for undelivered work.