
BNPL merchant approval takes as long as your chosen provider needs to assess your business; there is no single approval period you can apply to every application in 2026. An approval decision is also different from being ready to offer instalments, so ask for separate confirmation of the decision date and the checkout launch date.
- How long does BNPL merchant approval take? Confirm the timeline for your business directly with the provider.
- Merchant approval, checkout setup and customer finance decisions are separate milestones.
- Payitmonthly offers UK retailers interest-free monthly instalments; confirm onboarding timing before scheduling your launch.
- Request a complete application checklist and a written explanation of any outstanding steps.
Why this matters
A finance launch needs a usable payment option, not just an accepted application. If you schedule advertising around an approval estimate without checking what that estimate covers, your campaign and checkout can end up working to different deadlines.
Plan around readiness to transact, not submission of an application. Your sales team needs to know when it can introduce instalments, what customers must do next and how to handle questions without promising acceptance.
Payitmonthly provides BNPL for UK retailers and merchants, allowing customers to spread purchases into interest-free monthly instalments. That describes the service, not an approval deadline. For your 2026 launch, ask for a timeline that applies to your business and intended sales channel.
How long does it take to get approved as a BNPL merchant?
The useful answer is a provider-confirmed estimate with a clearly defined starting point and endpoint. A completion estimate means little if you do not know whether it starts when you register interest, submit the application or supply all requested information.
Use these steps to get a timeline you can actually plan around:
- Define the starting point. Ask when the provider considers your application complete and ready for assessment.
- Define the decision. Confirm whether the estimate covers a preliminary response, conditional acceptance or final merchant approval.
- Identify remaining actions. Ask what you must complete after acceptance before customers can use instalments.
- Confirm the launch point. Request confirmation of when your chosen sales channel will be ready to transact.
- Agree the follow-up. Find out who owns your application and when to contact them if the expected milestone passes.
Keep the answers together. A message containing an expected decision date is useful; a message containing the date, its conditions and the next action is much more useful.
Do not turn an indicative timeline into a customer-facing promise. Keep finance launch messaging unpublished until the provider confirms that your account and sales process are ready.
Which milestone does the approval estimate cover?
Separate application progress from operational readiness. These are different questions, even when a provider handles them through a single onboarding journey.
| Milestone | What you need to establish | What it does not establish |
|---|---|---|
| Application submitted | The provider has received your application | That it contains everything needed for assessment |
| Application complete | The provider confirms it has the requested information | That your business has been accepted |
| Merchant approved | The provider confirms acceptance and any conditions | That every checkout or sales process is ready |
| Ready to transact | Your intended customer payment journey is ready to use | That every customer finance application will be accepted |
Ask the provider to use these distinctions in its updates. Otherwise, a brief message saying your application is progressing leaves your team guessing about what to prepare next.
The same distinction matters when you read guidance about adding buy now pay later at checkout. Connecting a payment journey is a separate task from establishing whether your business has been accepted.
For a 2026 rollout, record the milestones in your launch plan rather than writing a single line marked finance approved. Give each milestone an owner and a clear completion condition.
What should you prepare before applying?
Start with the provider's current application checklist. Do not assume a checklist from another finance company applies to the provider you have chosen.
Business details. Have your legal business name, trading name and contact information ready. Check that your application clearly distinguishes the legal entity from the name customers see.
Ownership information. Ask which owners, directors or other responsible people must supply information. Request the exact evidence needed rather than sending a collection of documents without instructions.
Payment information. Ask what account details or supporting evidence the provider requires. Follow its specified submission method and avoid sending sensitive information through an unconfirmed channel.
Trading description. Explain what you sell, who buys it and how the sale is completed. A description of your business should make the intended use of customer finance clear without relying on the provider to interpret your website.
Sales journey. Identify where you want customers to access instalments. Describe the customer journey you intend to use and ask whether any additional setup is necessary.
Application contact. Nominate someone who can answer follow-up questions and coordinate internal responses. Make sure that person knows who can approve commercial terms and who handles checkout changes.
This preparation is a practical checklist, not a statement that every provider requires every item. The provider's own instructions determine what you submit.
Why BNPL merchant approval timing varies
To understand your own timeline, ask what is outstanding rather than requesting a faster result without context. Focus on these factors when discussing the estimate:
- Application completeness: Has the provider confirmed that it has all the information it requested?
- Information consistency: Do the business details agree across the application and supporting evidence?
- Business eligibility: Has the provider confirmed that your products, services and sales model fit its merchant criteria?
- Follow-up questions: Is anyone waiting for an answer, document or clarification from your team?
- Acceptance conditions: Does the decision depend on further actions before your account can be used?
- Launch setup: Does the quoted timeline include your intended checkout or sales process, or only the assessment?
These questions make an update actionable. If the provider needs a document, supply the requested document through the correct channel; if setup remains, assign that task to the person responsible for implementation.
For planning in 2026, distinguish an application dependency from a checkout dependency. They need different owners and different follow-up questions.
How do you keep your application moving?
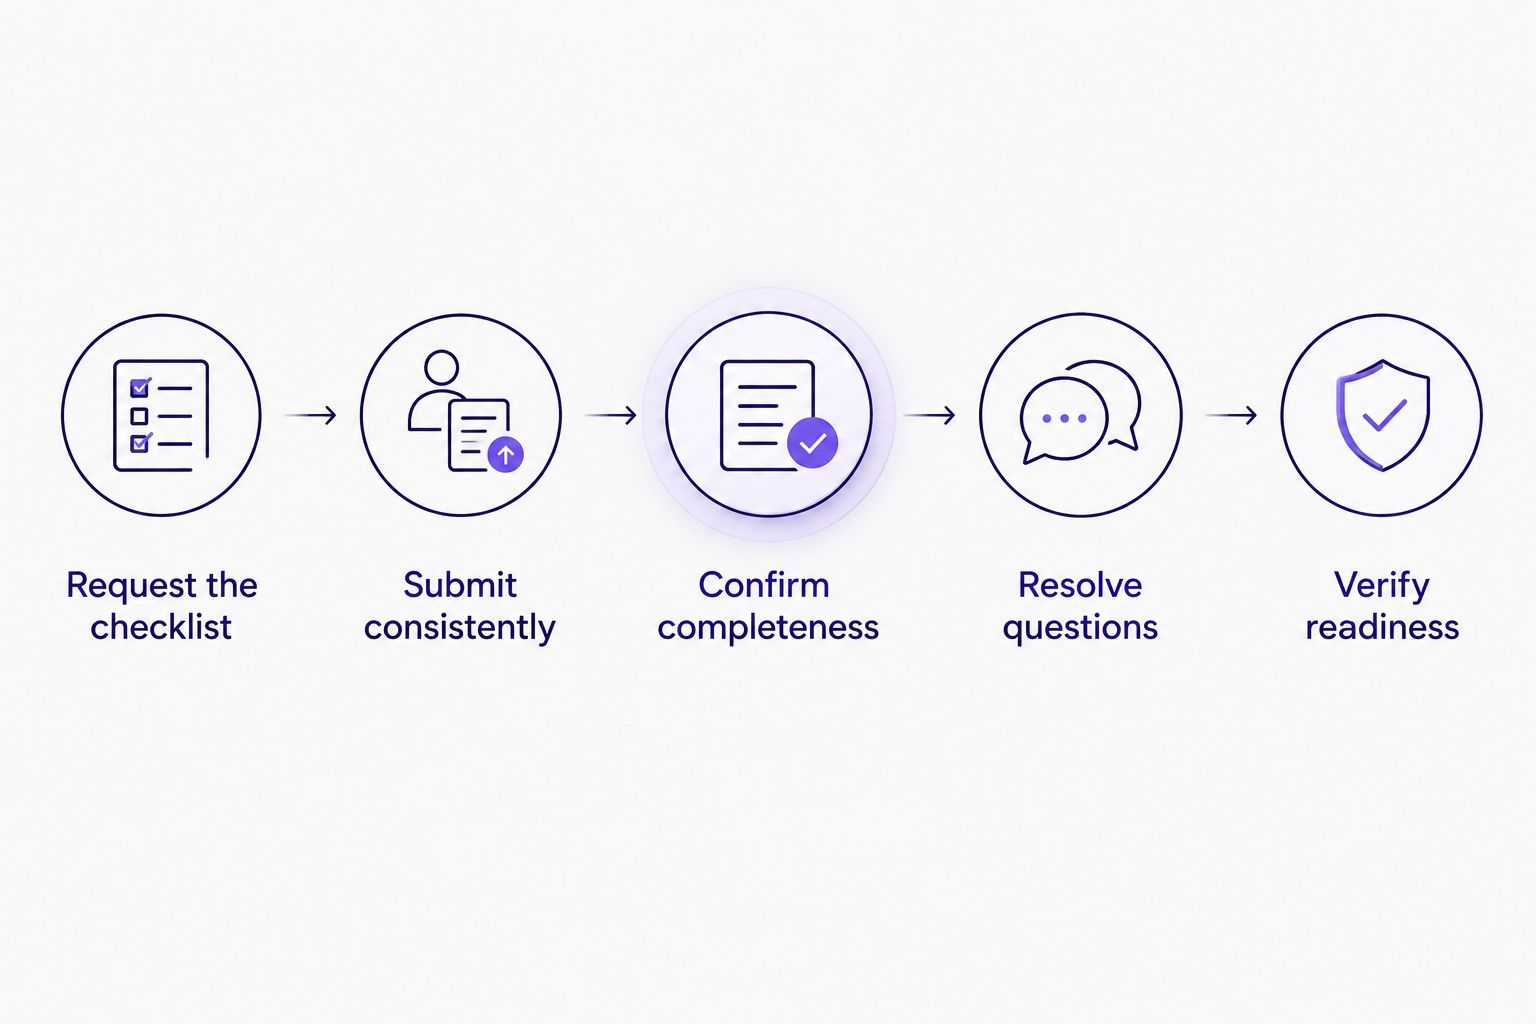
Use a simple sequence: establish what is required, submit it, confirm receipt, resolve questions and verify readiness. Do not treat submission as the end of your involvement.
Request the checklist
Ask for the current requirements before assembling your application. Confirm which information applies to your legal structure and intended sales channel, and use that list as your reference throughout onboarding.
Submit consistently
Check names, addresses and contact details before sending the application. Where your trading name differs from your legal name, explain the relationship clearly rather than leaving an apparent mismatch unresolved.
Confirm completeness
Ask whether anything remains outstanding once the provider has received your submission. A receipt acknowledgement and confirmation that an application is complete answer different questions.
Resolve questions
Send a direct response to each follow-up request. If a request is unclear, ask what evidence will satisfy it instead of submitting unrelated material.
Verify readiness
After acceptance, confirm the remaining steps for your intended sales journey. Check that the team responsible for launch understands any conditions before publishing finance messaging.
Keep a single record of the provider's requests and your responses. This gives whoever follows up a clear view of the latest position without searching through separate conversations.
Can you get approved as a BNPL merchant on the same day?
Only rely on same-day merchant approval when the provider confirms that it applies to your application and explains its conditions. Do not infer merchant approval speed from messaging about quick customer finance decisions.
A customer decision concerns an individual purchase. A merchant application concerns your business's access to the provider's service, so the two timelines are not interchangeable.
If you have a fixed campaign date, tell the provider before you apply. Ask whether it can confirm readiness by that date, not simply whether applications are processed quickly.
Does merchant approval mean you can offer BNPL immediately?
Merchant approval does not by itself confirm that your intended sales journey is ready. Ask whether you still need to accept terms, complete account actions or finish checkout setup before offering instalments.
Treat acceptance as a milestone rather than a launch instruction. Obtain explicit confirmation that customers can use the intended process before asking your sales team to promote it.
How do you follow up on a pending BNPL application?
Ask for the current stage, the outstanding action and the next expected update. Include your application reference if the provider has supplied one, and keep the request specific.
A useful follow-up contains:
- Your business's legal and trading names.
- The date you submitted the application.
- The date you supplied the latest requested information.
- A request to confirm whether the application is complete.
- A request for the next milestone and any action required from you.
Avoid submitting another application unless the provider instructs you to do so. Follow the existing application through its stated contact route so your request has the right context.
What should you confirm before choosing a provider?
Approval speed is useful only alongside a service that fits your business. Ask about eligibility, the customer payment journey, merchant responsibilities and the commercial terms before making a decision.
Payitmonthly is suited to UK retailers and merchants seeking interest-free monthly instalments for their customers. That fit does not establish whether a particular business will be accepted or how quickly it will be ready to launch.
The benefit of Payitmonthly BNPL is the stated ability to spread customer purchases into interest-free monthly instalments. The practical limitation is that you still need to establish suitability and onboarding timing for your own business before committing to a launch date.
Compare written answers rather than relying on a short speed claim. Ask each provider to distinguish its assessment estimate from the work needed to start taking payments through your intended channel.
Explore monthly instalments for your business
Review interest-free monthly instalments for UK retailers and merchants.
FAQ
How long does BNPL merchant approval take in 2026?
BNPL merchant approval has no single timeline that applies to every provider and business. Ask your chosen provider for an estimate that starts from a complete application and identifies the decision it covers.
Can I get approved as a BNPL merchant today?
Rely on approval today only if the provider confirms it for your application. Check whether that confirmation means final acceptance or whether conditions remain outstanding.
Is merchant approval the same as customer finance approval?
Merchant approval and customer finance approval are different decisions. Merchant approval concerns your business's access to the service; customer approval concerns an individual finance application.
What documents do I need for BNPL merchant approval?
Use your chosen provider's current document checklist. Ask which business, ownership and payment information applies to your application rather than assuming another provider's requirements are the same.
How can I help my BNPL application progress?
Submit the requested information consistently and answer follow-up questions directly. Ask the provider to confirm completeness and identify any action still required from you.
Can I advertise instalments before merchant approval?
Wait until the provider confirms that your business and intended sales journey are ready before publishing launch messaging. An application submission is not confirmation that customers can use the payment option.
Does Payitmonthly provide interest-free instalments for retailers?
Payitmonthly provides UK retailers and merchants with a BNPL platform for interest-free monthly instalments. Confirm business suitability and the onboarding timeline directly before scheduling a launch.
One last thing
The most useful onboarding question is not just how long approval takes; it is what must be true before a customer can complete a purchase. That question connects the assessment, account conditions and sales setup to the outcome your business needs.
Before setting your 2026 launch date, request a written answer with the remaining actions and their owners. A clearly defined launch condition is more useful than a fast estimate with an unclear endpoint.


